Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
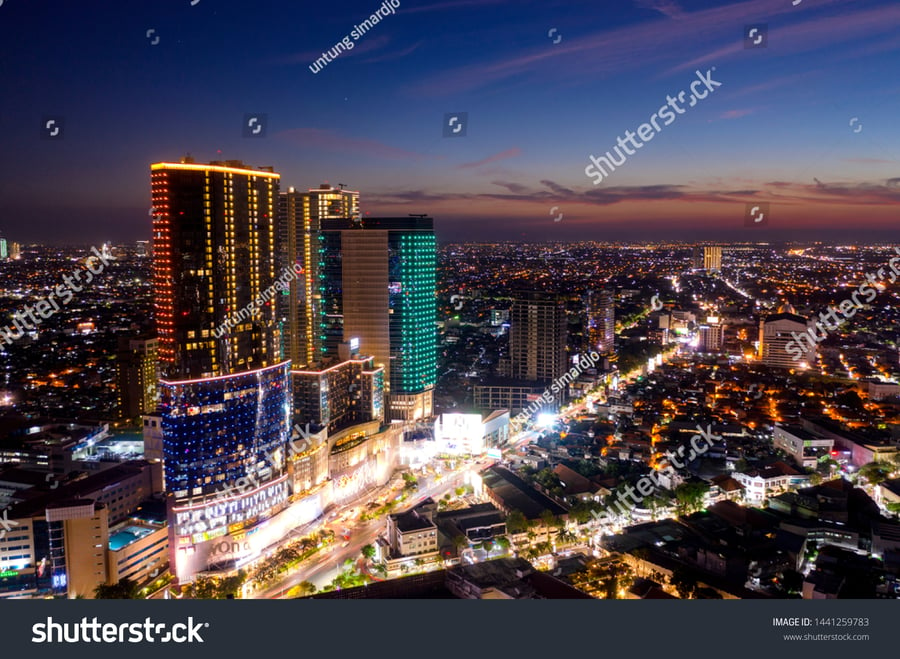
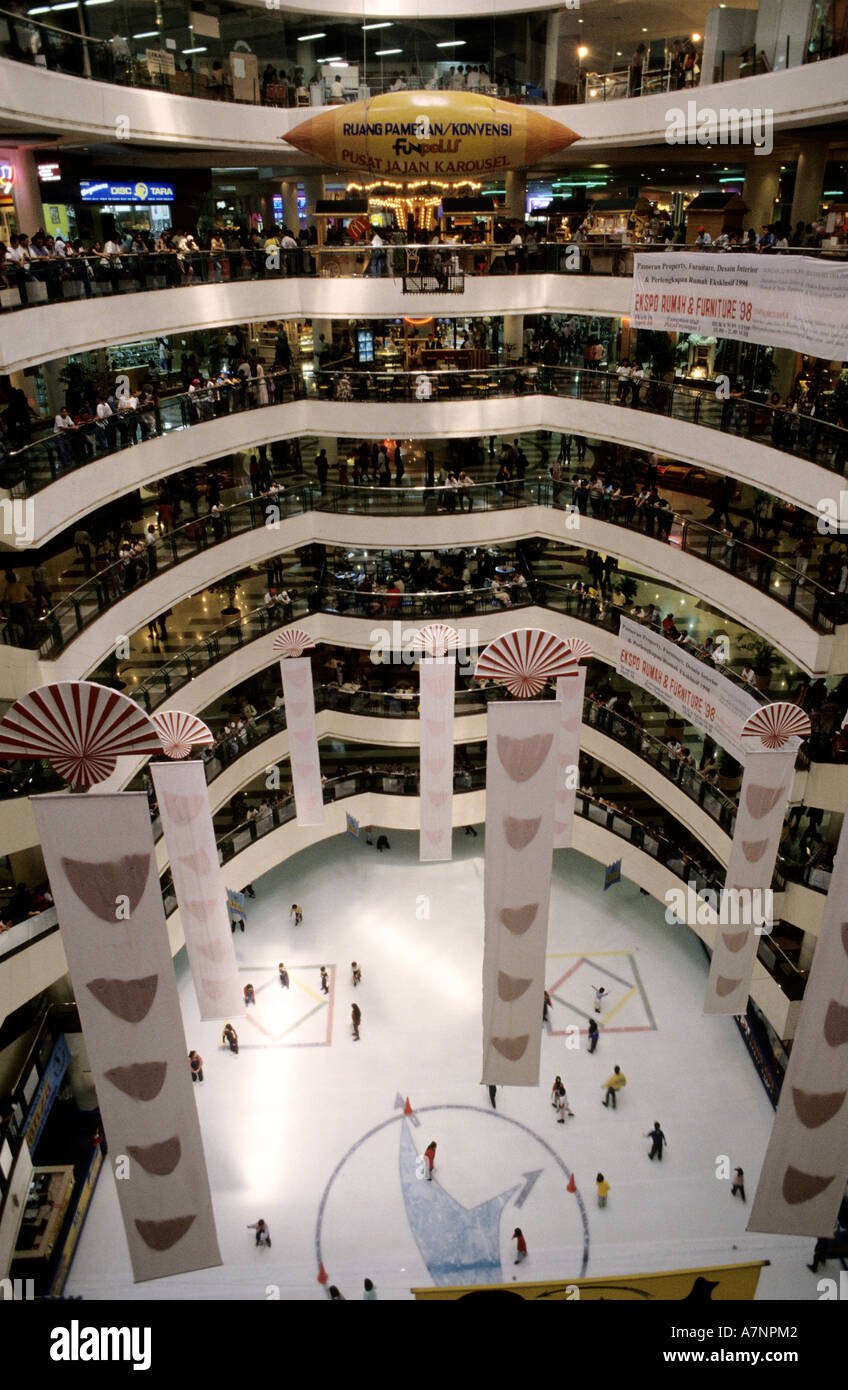
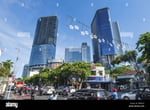
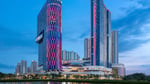
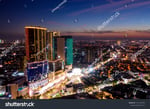
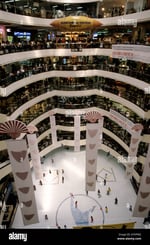
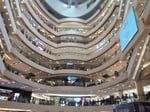
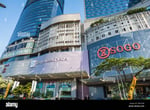
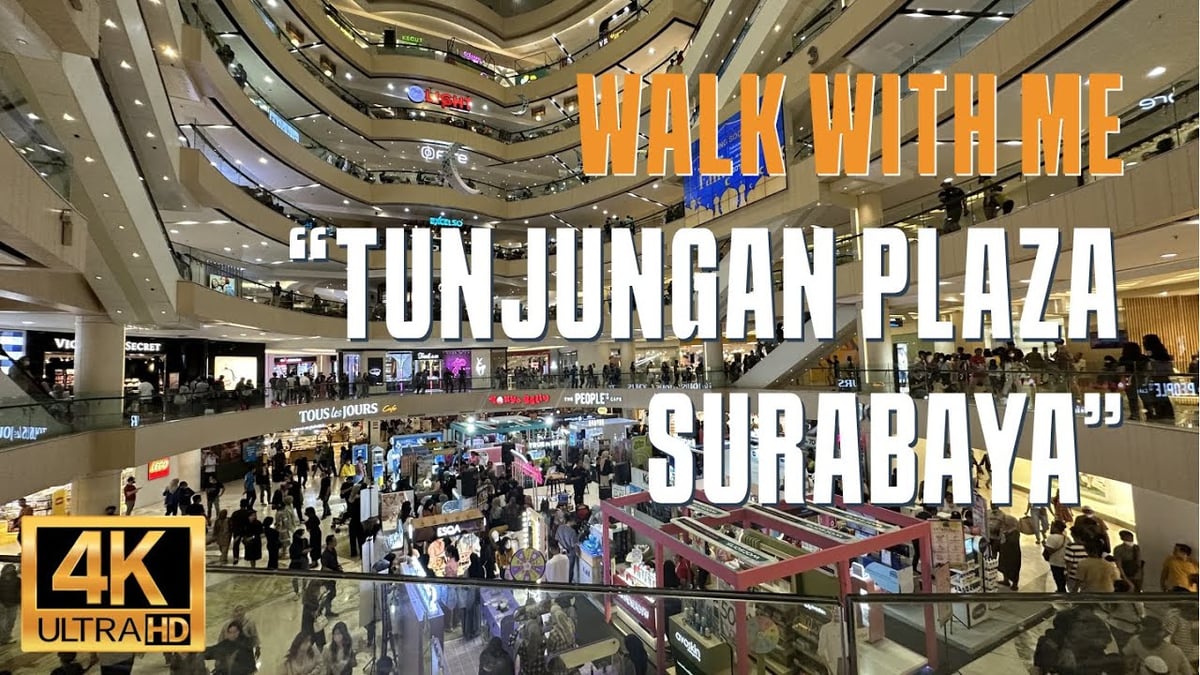
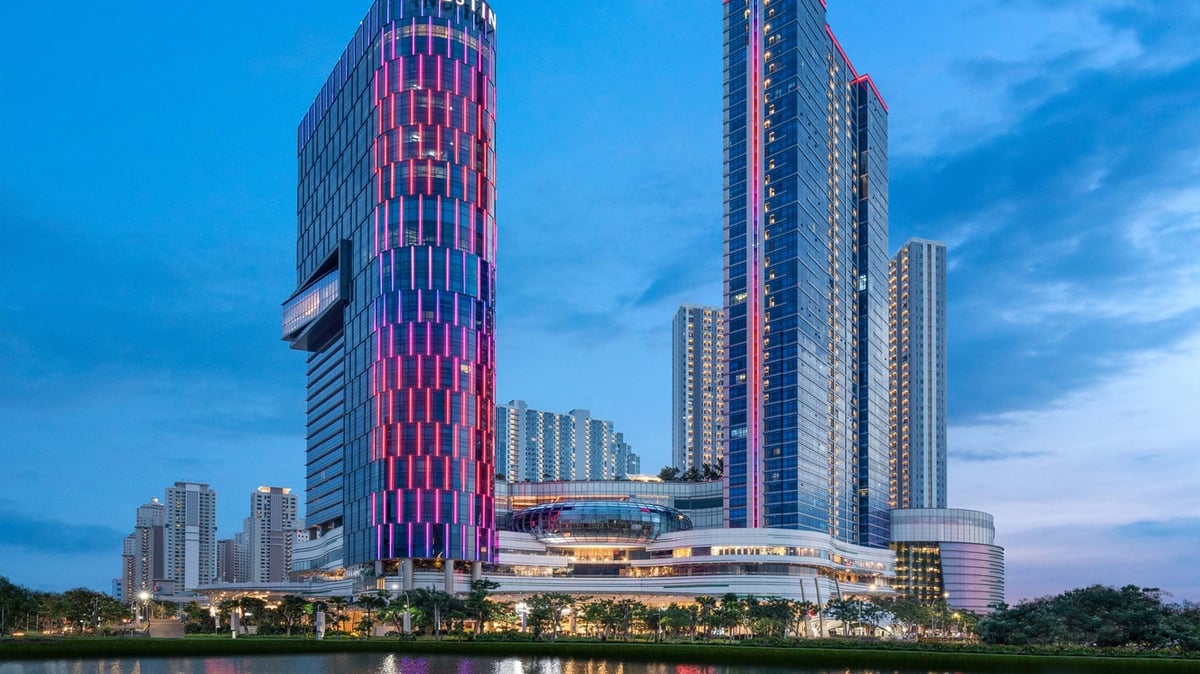
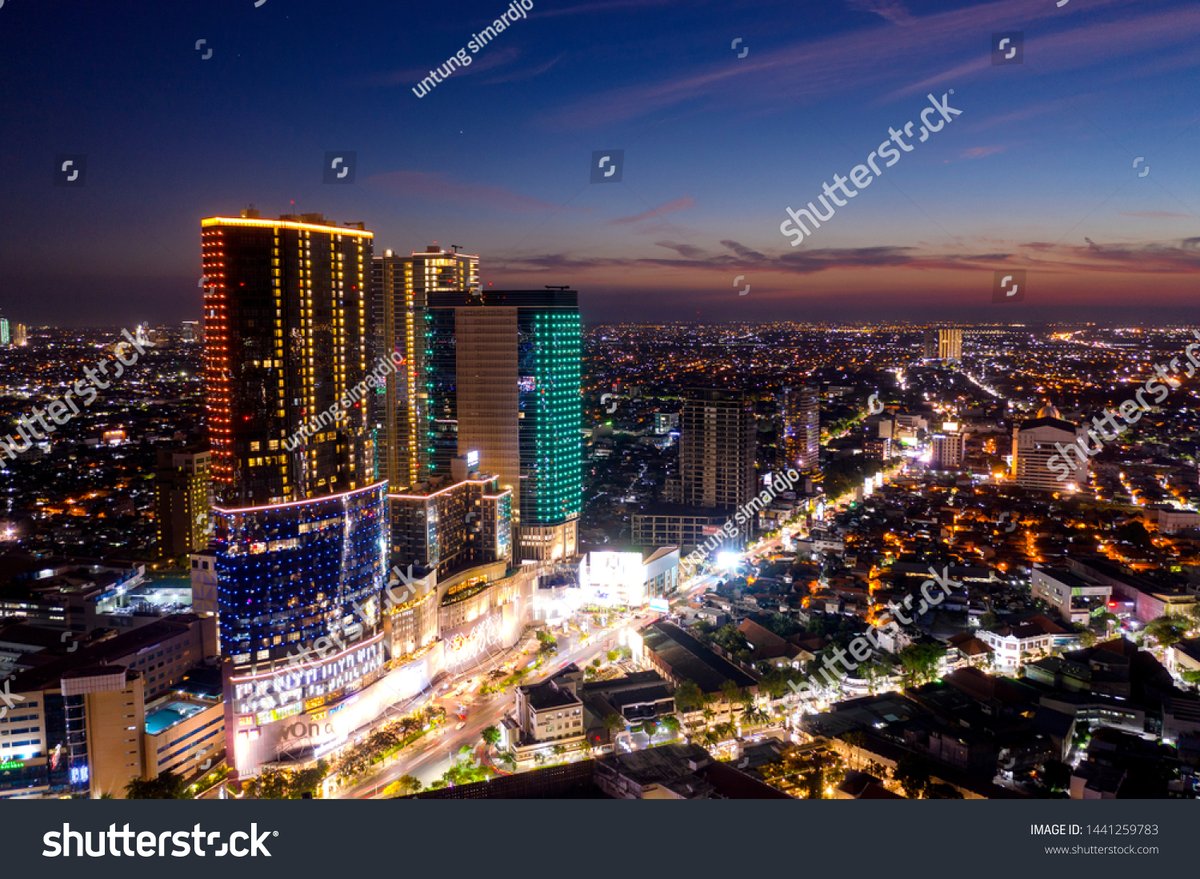
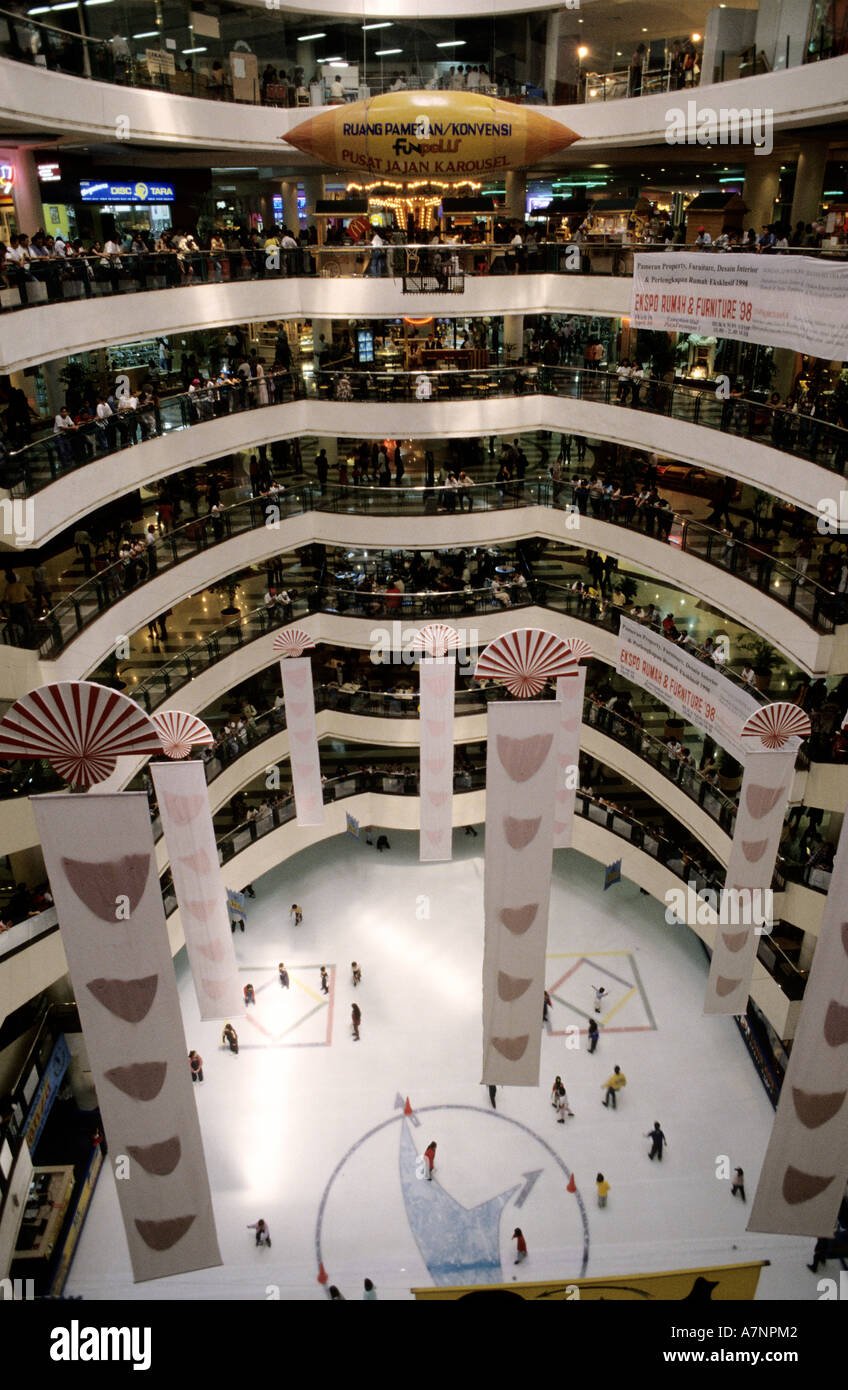
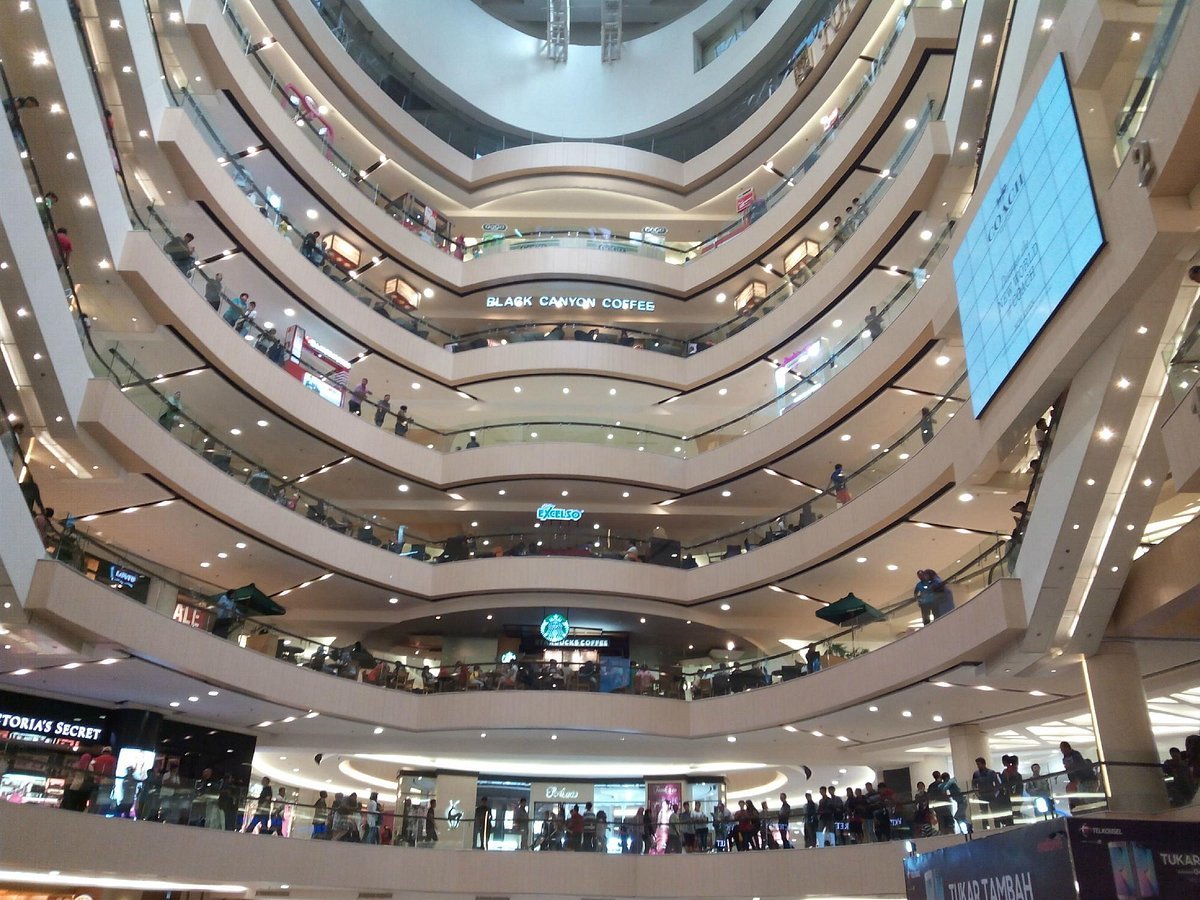
Surabaya Town Square, situated at Jl. Hayam Wuruk No. 6 in the Wonokromo district of Surabaya, East Java, operates as a four-floor mid-tier retail center completed in 2008 by PT. Graha Megaria Raya. It functions primarily as a lifestyle, entertainment, and hangout destination targeting middle-class families and young adults in the residential surroundings, rather than a high-volume shopping venue. The tenant mix comprises approximately 150 outlets focused on food and beverage (around 40%), casual fashion and accessories (30%), and entertainment facilities including cinemas and play areas, with notable anchors like Trans Studio Mall integration for amusement and brands such as A&W, Bread Talk, Baskin Robbins, and local retailers.
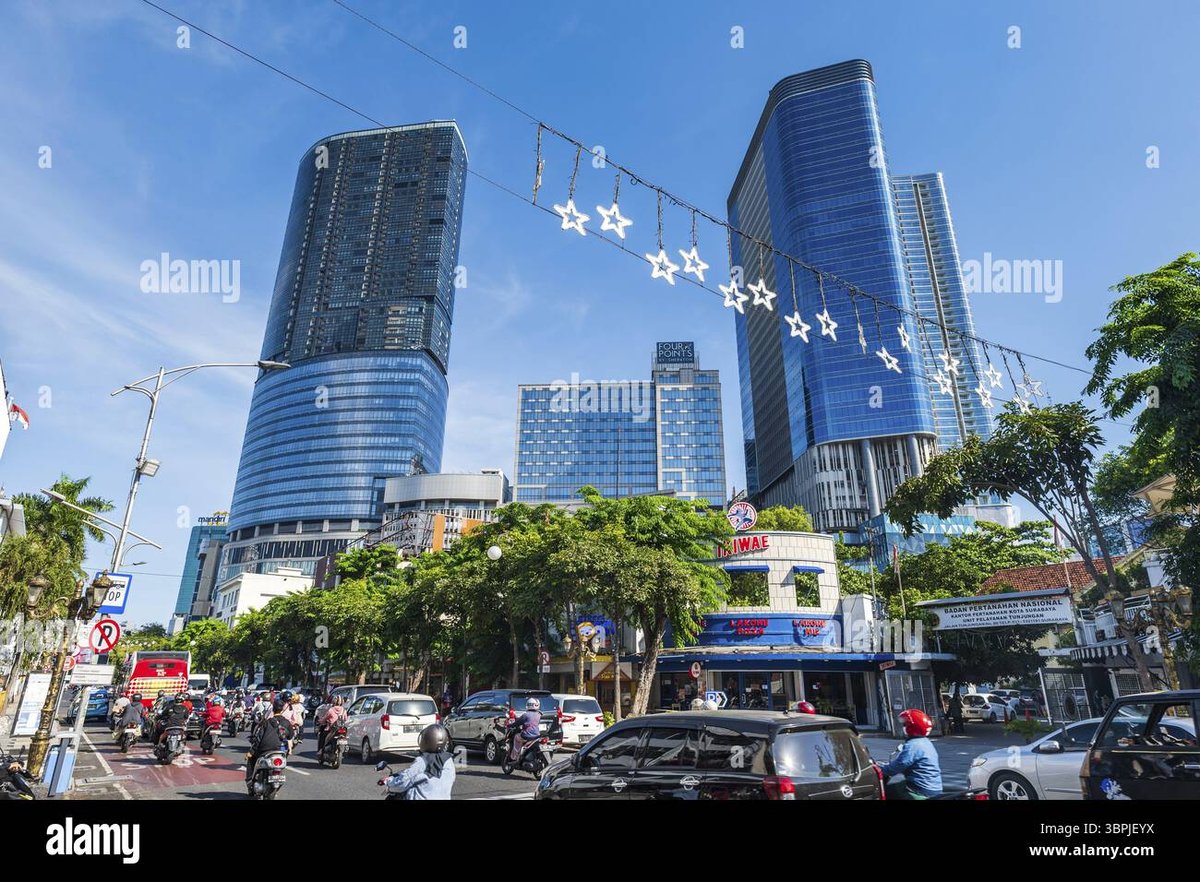
Accessibility benefits from its position on a major arterial road, with proximity to public transport routes, ample parking for over 1,000 vehicles, and connections to the citys toll roads, though traffic congestion during peak hours presents minor challenges. In the Surabaya retail landscape, where overall occupancy reached 72.5% in H2 2024 per Colliers International reports, the property holds a stable market position among community malls, supported by a demographic of 2.92 million residents citywide with a minimum wage of IDR 4.96 million monthly.
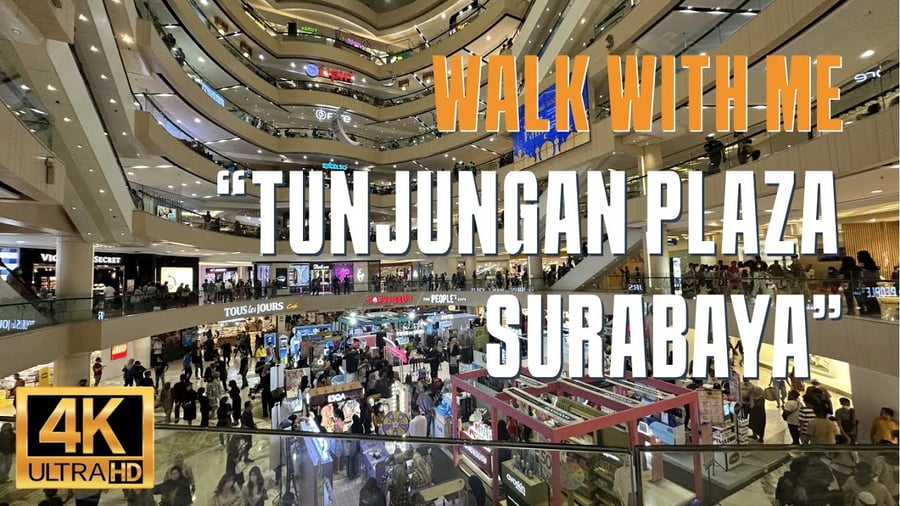
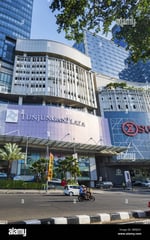
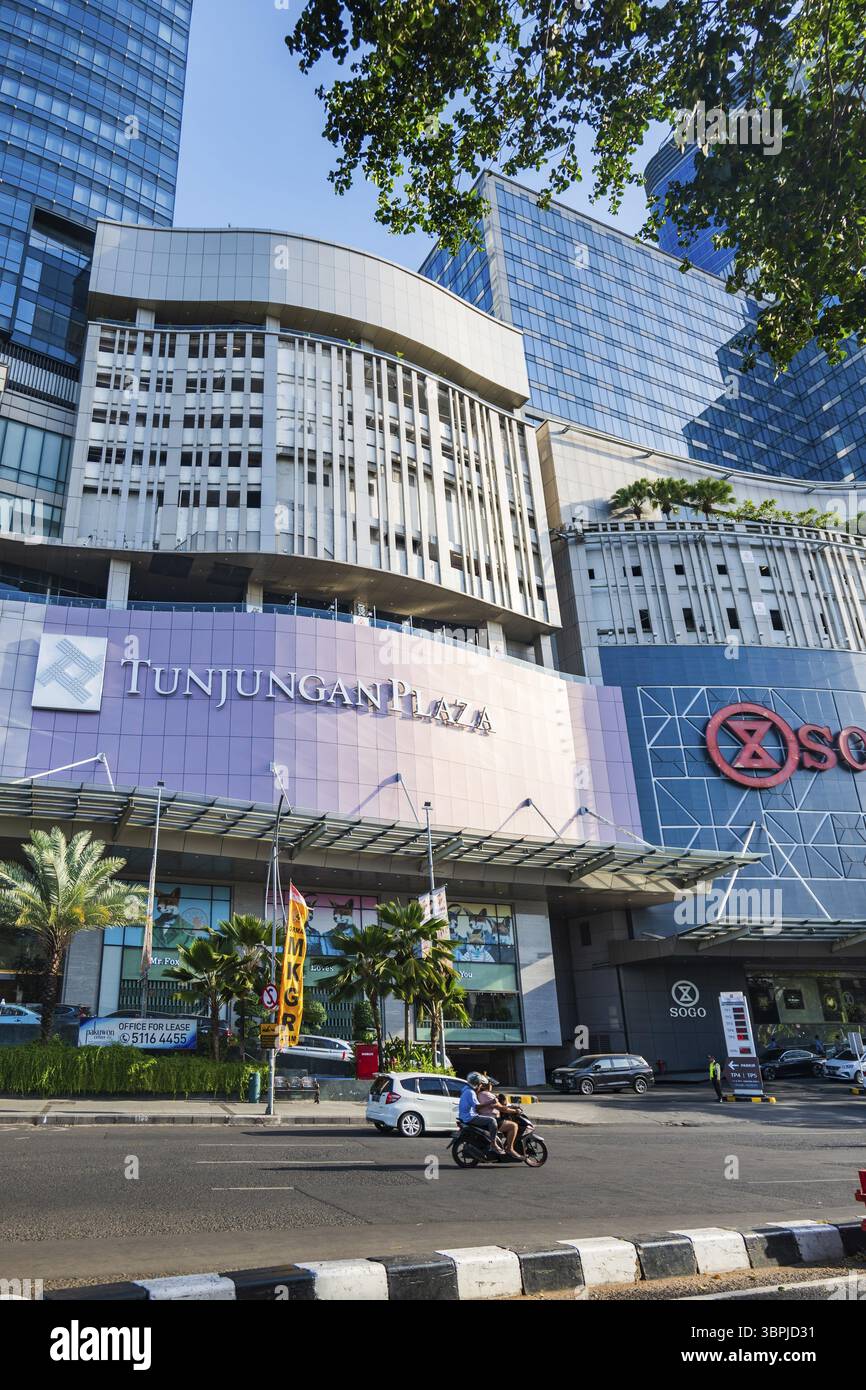
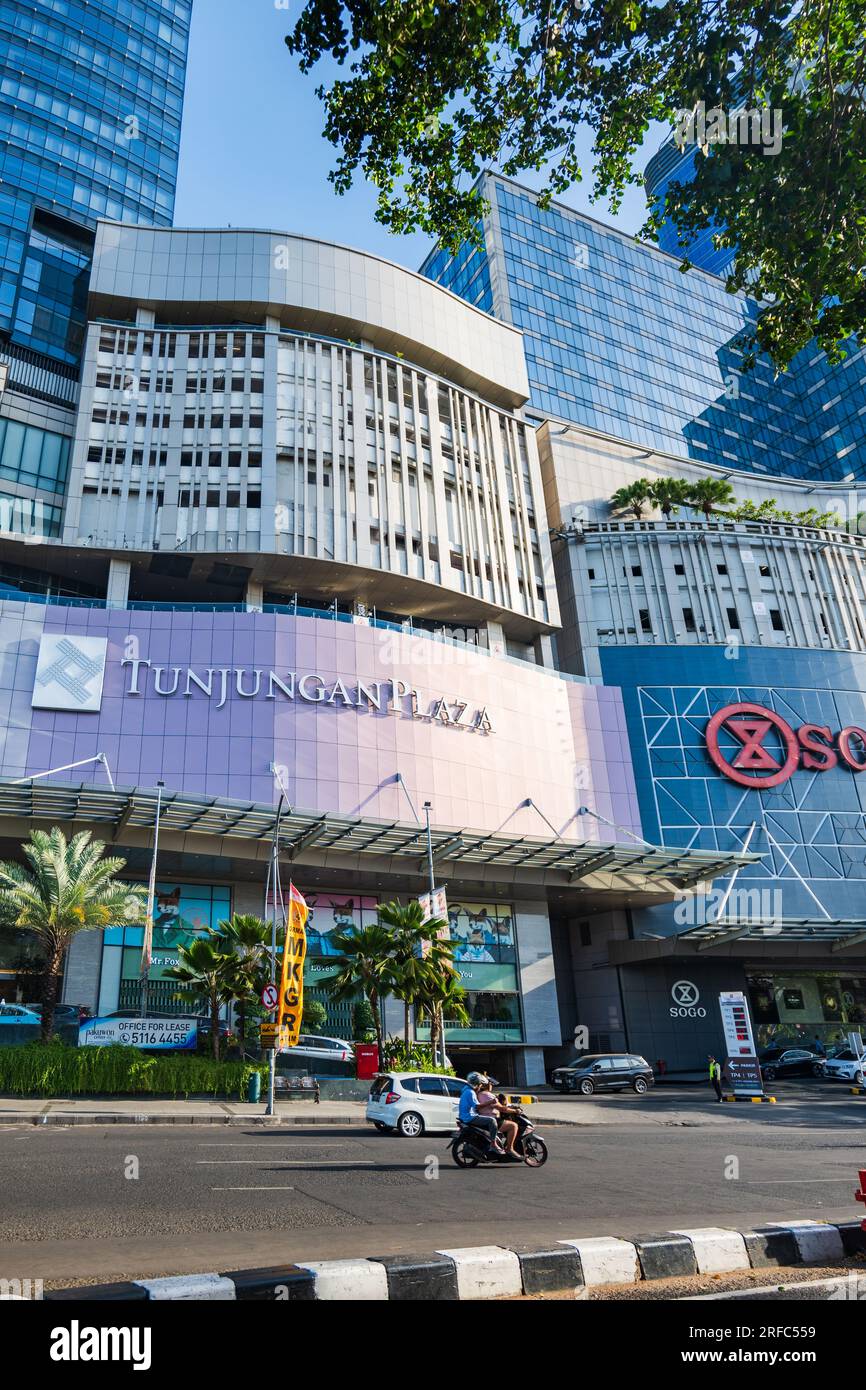
Leasing opportunities offer competitive terms with estimated rents of IDR 300,000 to 450,000 per sqm per year for mid-tier spaces, lower than premium centers IDR 500,000+, enabling cost-effective entry for emerging brands. Advantages include vibrant F&B scene driving repeat visits and event programming to enhance footfall, estimated at 5,000-7,000 daily visitors based on similar properties. Drawbacks encompass competition from upscale rivals like Tunjungan Plaza (97% occupancy) and potential saturation in dining categories, alongside risks from economic fluctuations impacting discretionary spending in a market projected to grow occupancy by 3% annually through 2027.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile and Footfall
Wonokromo district features a middle-income residential profile within Surabaya's 2.92 million population (2024 data), with high density of 8,698 people per sq km fostering local catchment. The consumer base, with regional minimum wage at IDR 4,961,753 (2025), supports spending on casual dining and entertainment rather than luxury goods. Footfall averages 5,000-7,000 visitors daily, driven by family outings and proximity to universities, though lower than central malls 10,000+; this provides consistent but moderate traffic for lifestyle retailers, with seasonal boosts from promotions.
Occupancy Rates and Rent Levels
Surabaya retail market occupancy stood at 72.5% in late 2024, expected to rise 3% yearly to 2027 according to Colliers, reflecting recovering demand post-pandemic. For community-oriented properties like Surabaya Town Square, occupancy hovers around 75-80%, above average due to strong local appeal but below premium benchmarks. Rent levels for prime spaces range IDR 300,000-450,000 per sqm annually, with a projected 2% increase in 2025; service charges add IDR 50,000-70,000 per sqm. This structure offers affordability for small-to-medium tenants, though negotiations may be needed amid selective leasing to optimize mix.
Tenant Mix, Competition, and Risks
The tenant composition prioritizes F&B (40% of space, including international chains like A&W and local eateries), lifestyle retail (30%), and leisure (20% with cinema and arcade), creating a relaxed atmosphere that attracts hangouts over purchases.
Strengths lie in diverse dining drawing repeat traffic; weaknesses include limited anchor department stores, potentially capping sales in fashion categories. Competition intensifies from nearby Ciputra World Surabaya and central Tunjungan Plaza, risking footfall diversion amid 15+ malls in the city leading to category saturation in casual dining. Risks involve aging infrastructure since 2008 requiring maintenance investments and vulnerability to economic slowdowns affecting middle-class spending, with operational quality maintained through regular events but challenged by access issues during floods or traffic peaks.
Building Details
Detailed Market Analytics
City Snapshot
Surabaya
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Surabaya
Discover more shopping centers in Surabaya.


Popular in Indonesia
Top retail destinations across Indonesia.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Surabaya
Comprehensive market intelligence for retail expansion in this city