Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
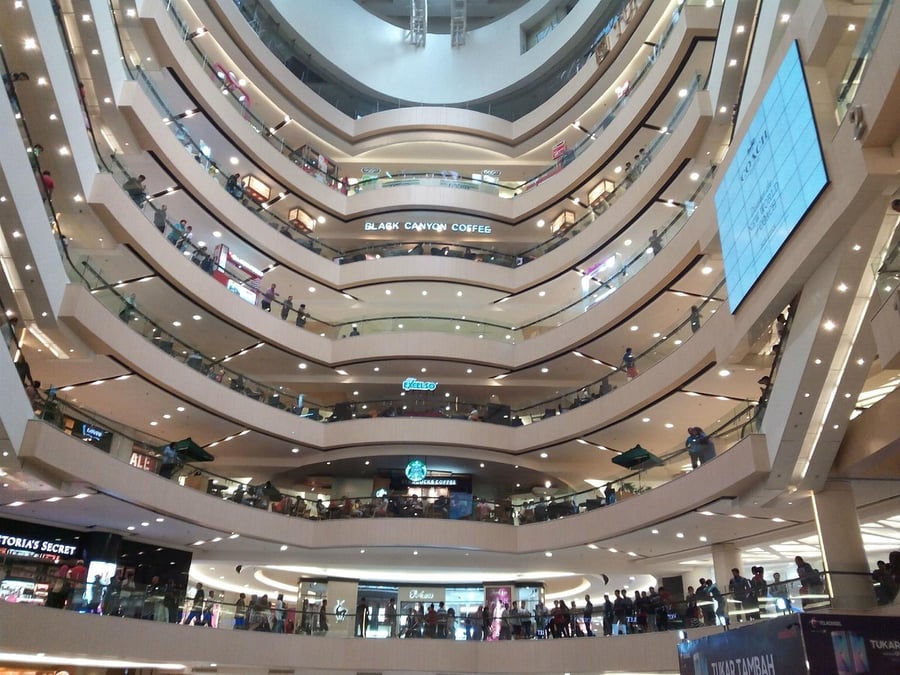
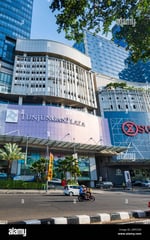
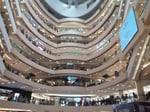
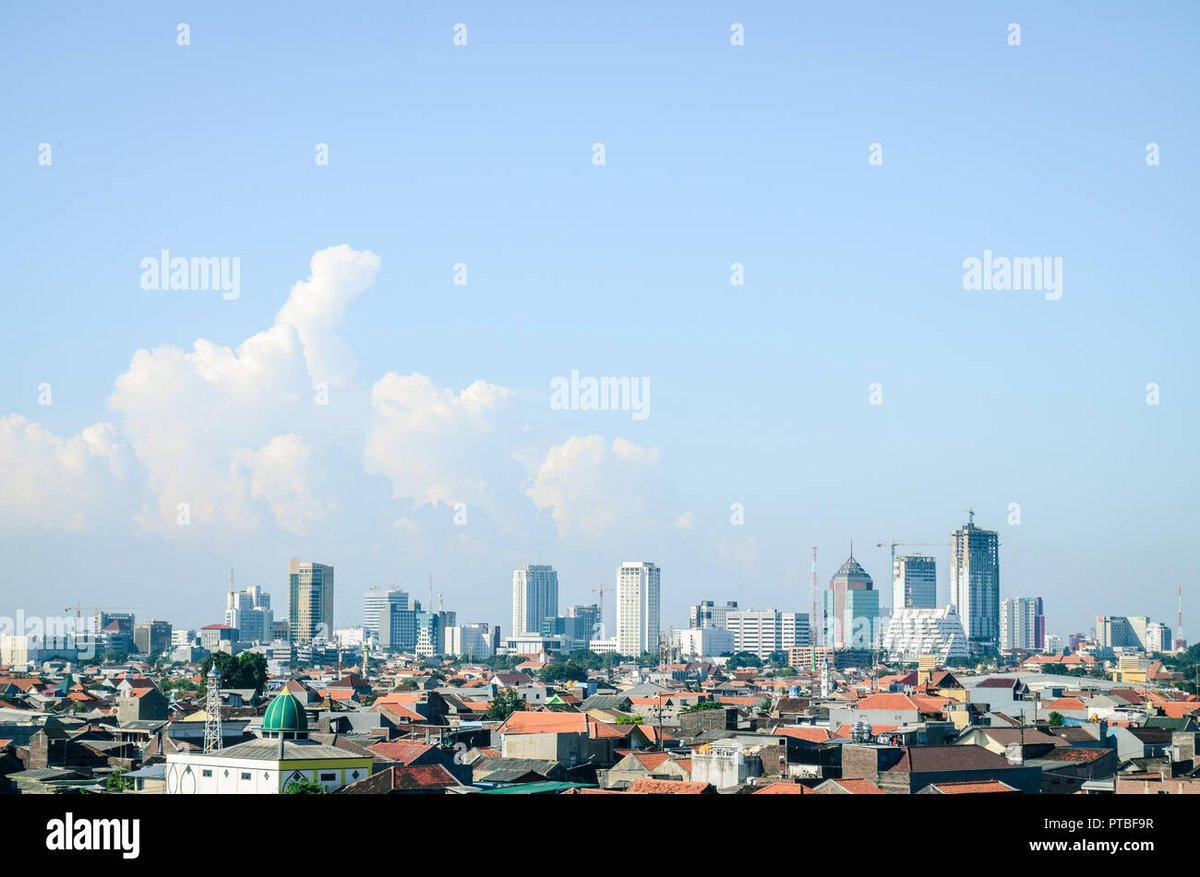
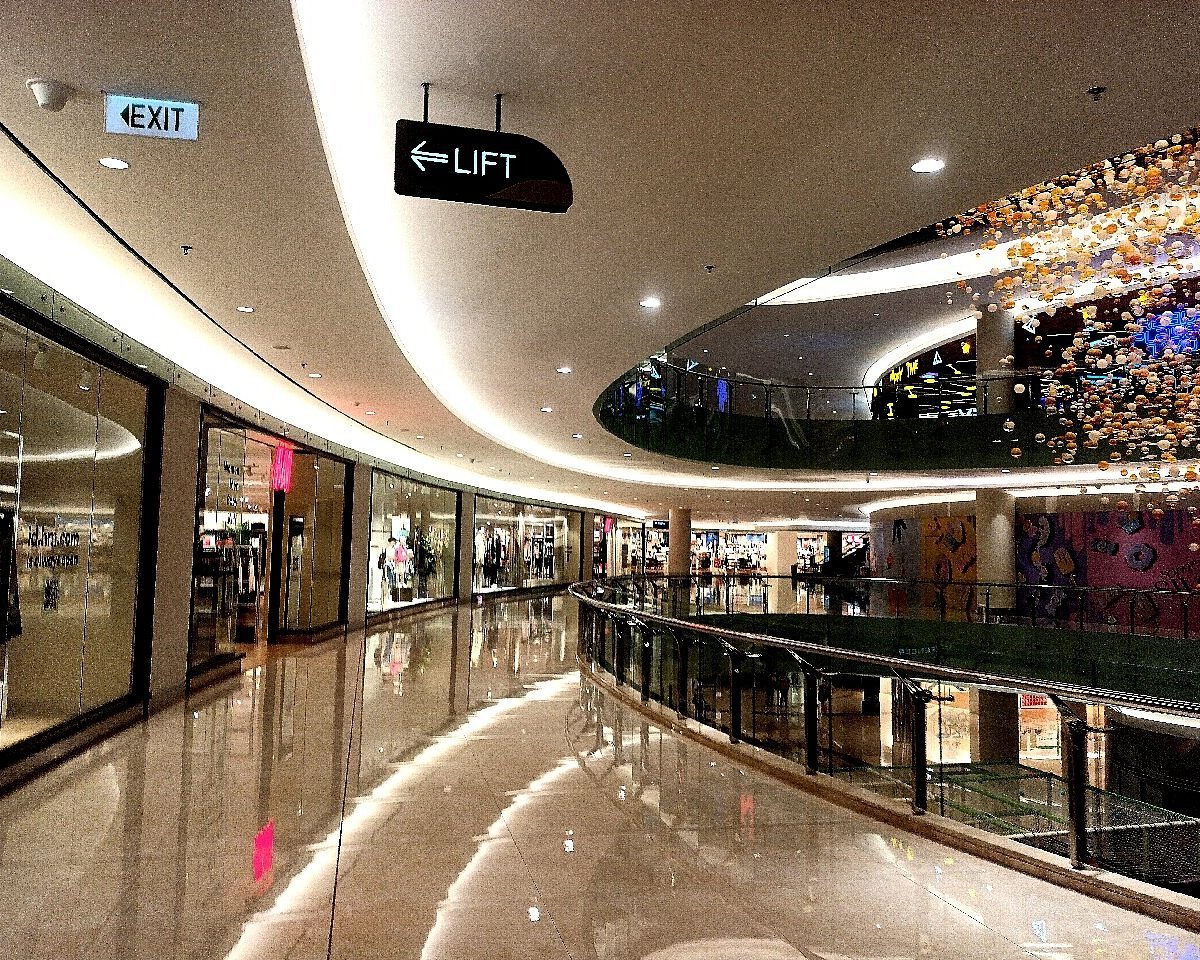
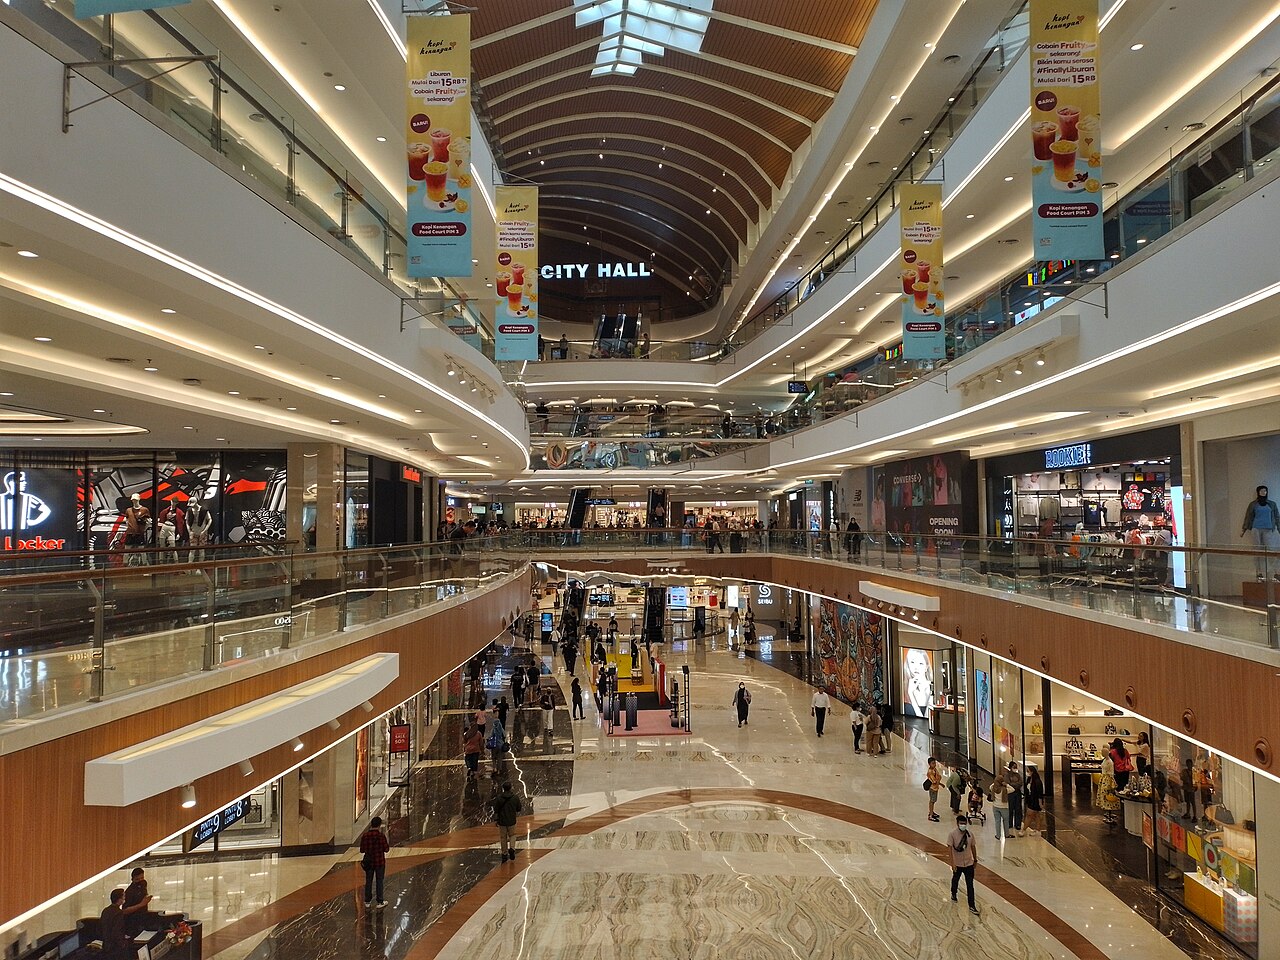
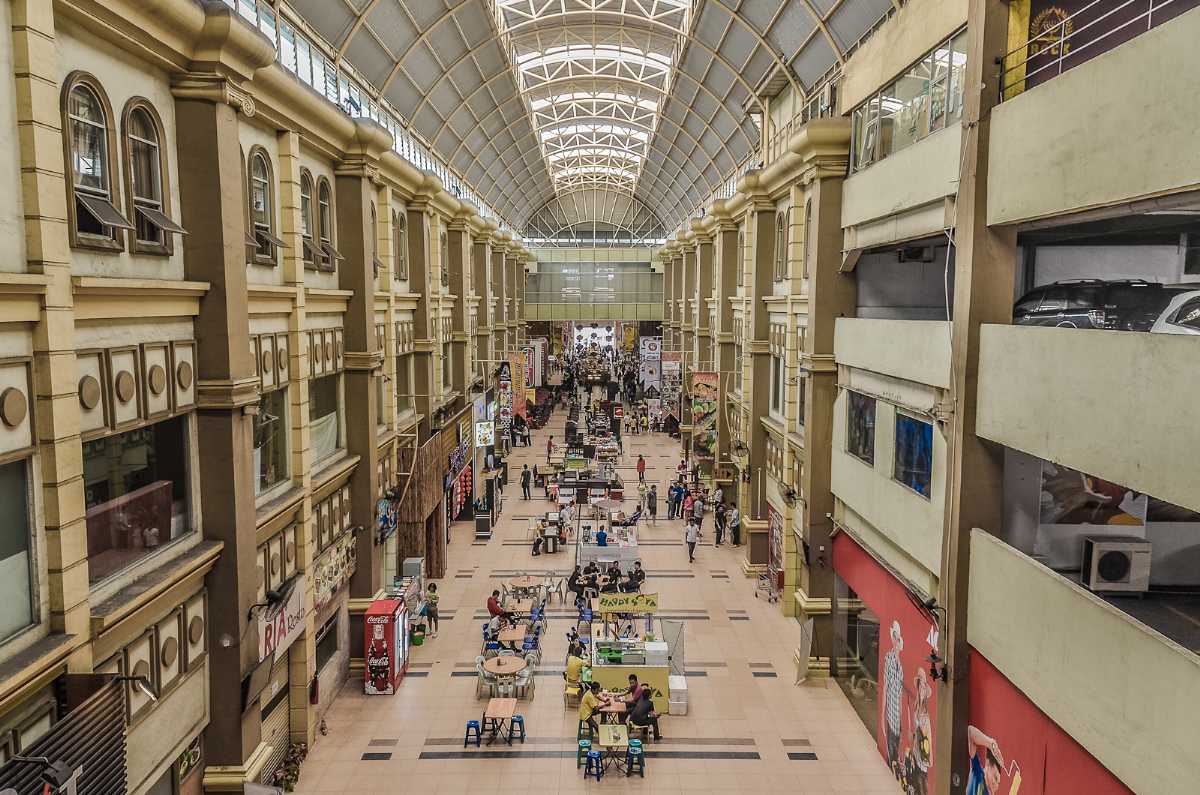
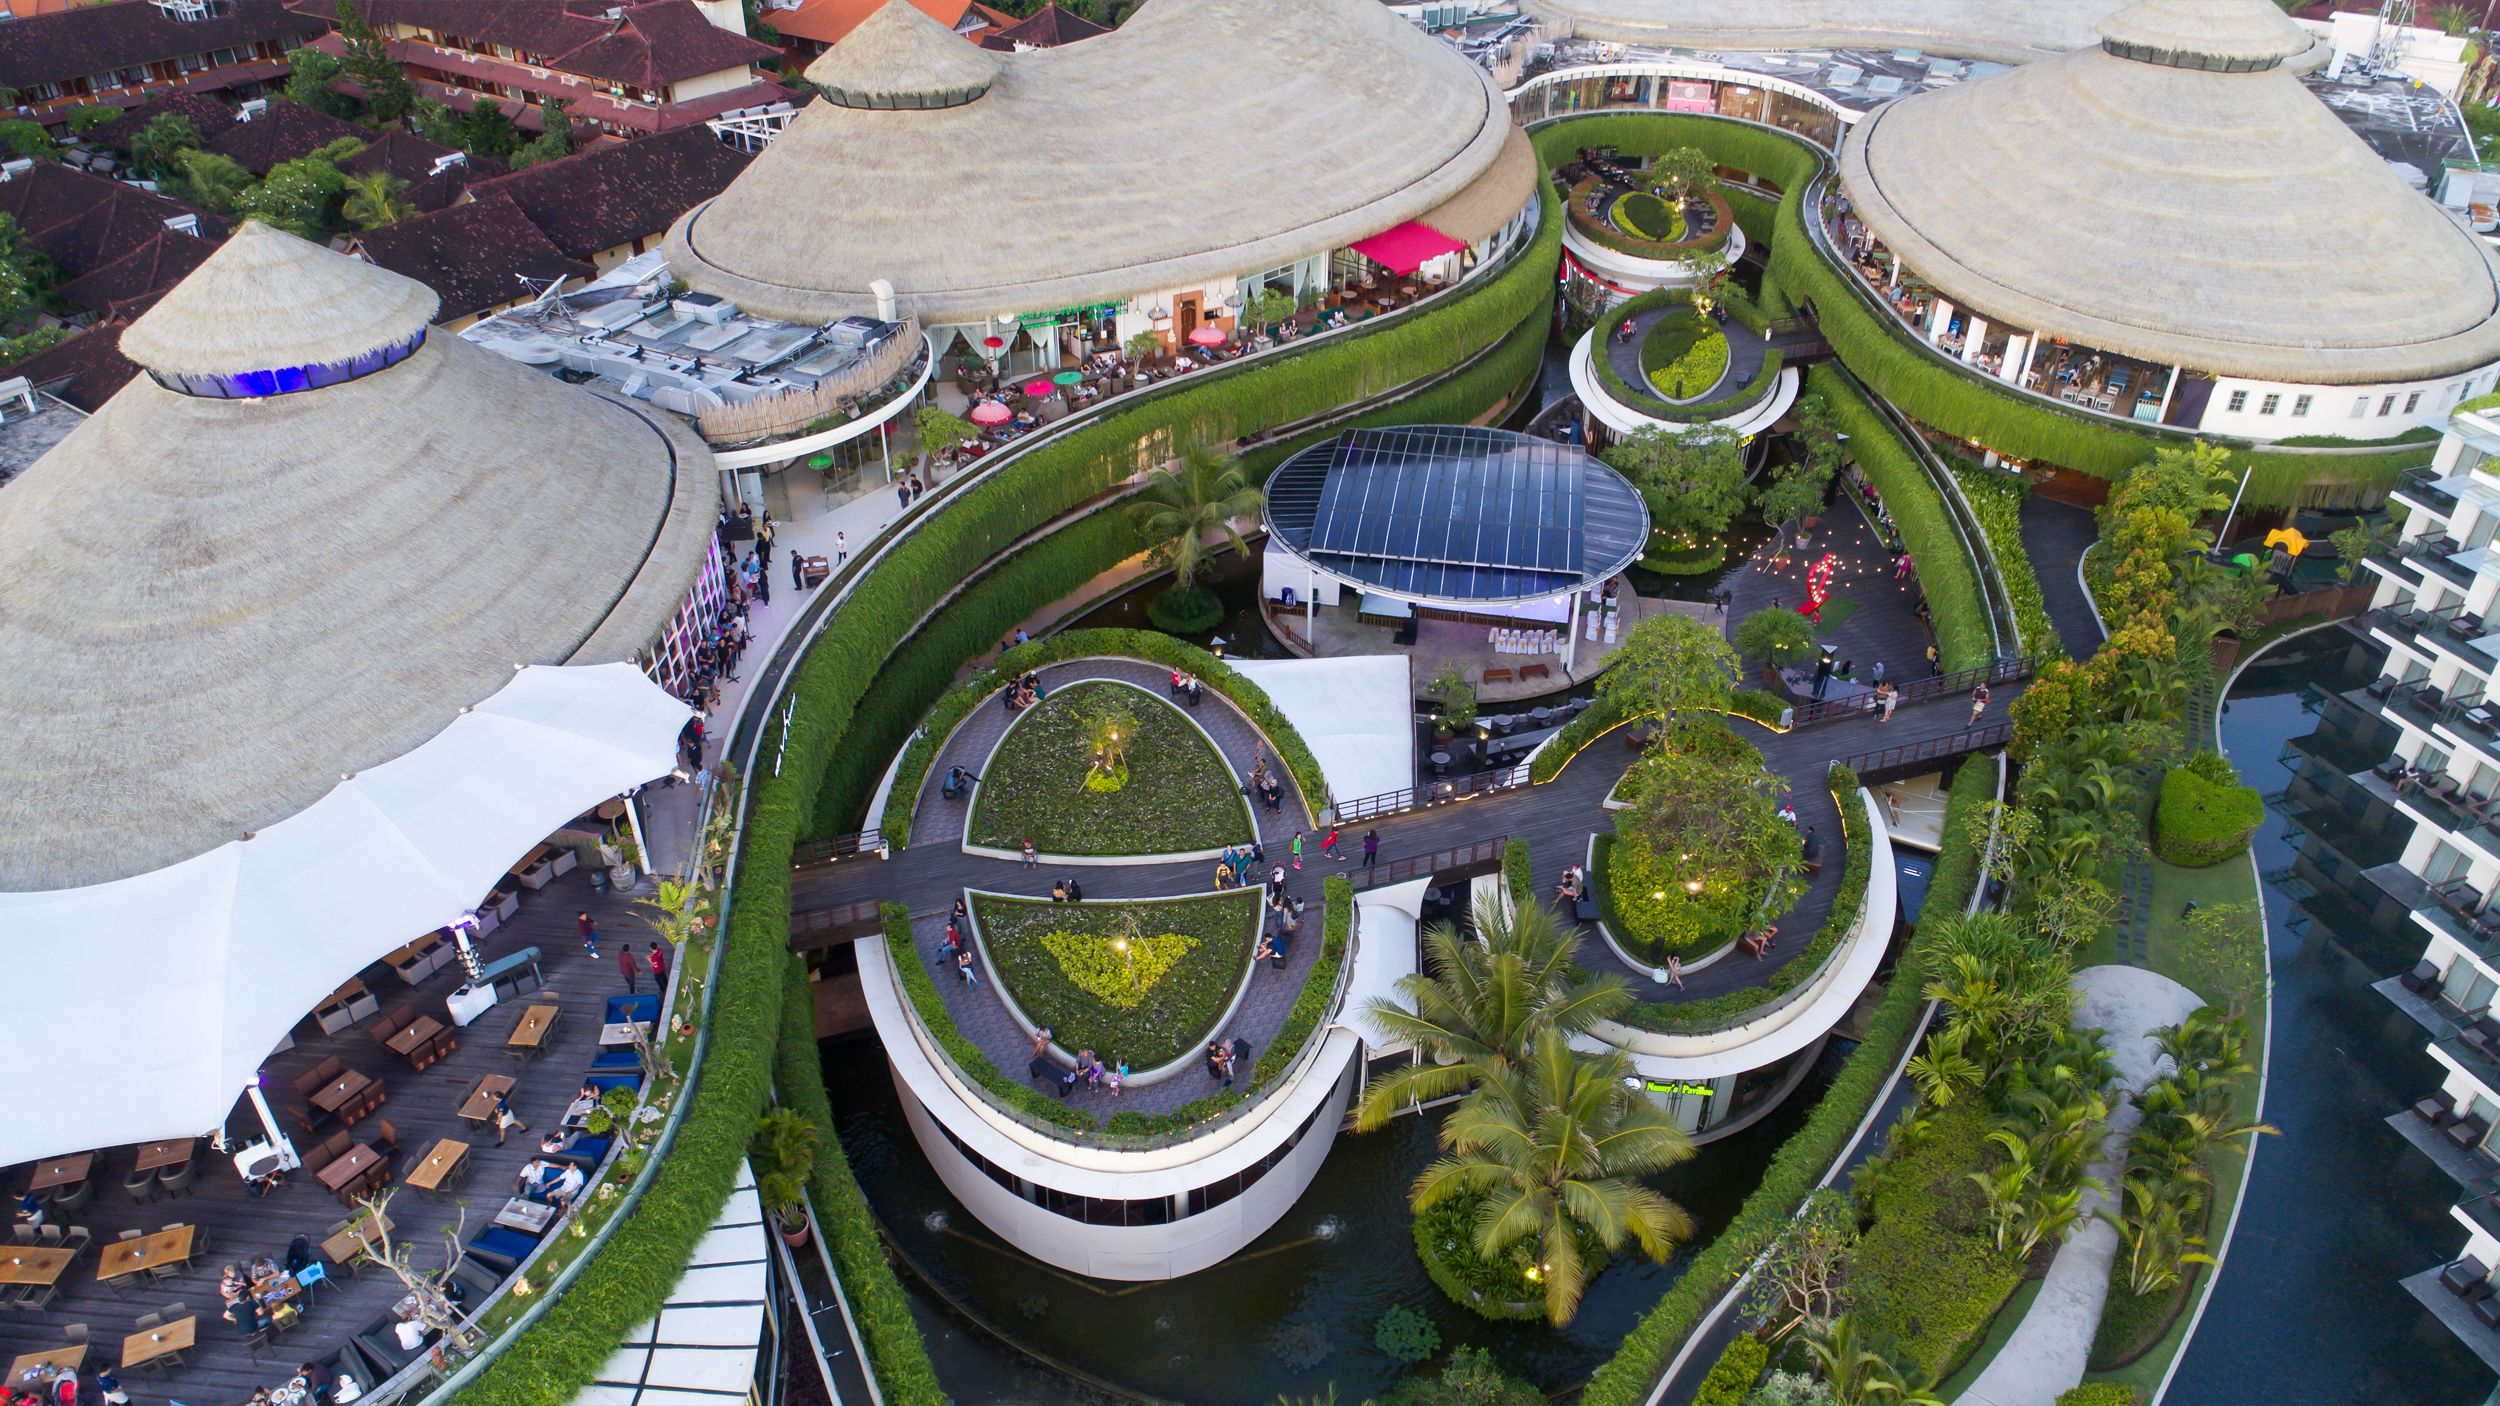
Grand City Surabaya is a prominent shopping center located in the central Gubeng district of Surabaya, Indonesia, spanning approximately 4.5 hectares across 8 floors with a total gross leasable area estimated at around 100,000 square meters. Opened in 2007, it positions itself as a one-stop shopping and MICE (Meetings, Incentives, Conferences, Exhibitions) destination, attracting urban shoppers and event attendees.
The tenant mix is diverse, featuring anchor stores such as Hero Supermarket for groceries, The Grand Palace department store, international brands like Marks & Spencer for fashion, electronics retailer Best Denki, and entertainment options including Cinema XXI, The Premiere luxury cinema, Happup Karaoke, and Fun World arcade. Dining outlets cover local Indonesian cuisine, international fast food, and cafes, while retail includes apparel, accessories, beauty, and lifestyle brands.
In the Surabaya retail market, which saw an occupancy rate of 72.5% in late 2024 rising to about 76% in 2025 per Colliers reports, Grand City benefits from high footfall due to its central location near Gubeng Train Station and major roads, drawing middle-class demographics aged 18-45 from the citys 3 million residents and surrounding areas.
Leasing advantages include flexible space options from 50 to 1,000 square meters, competitive rents averaging IDR 600,000 to 900,000 per square meter per month based on location and category, and promotional support through events that boost visibility. However, challenges include competition from larger complexes like Tunjungan Plaza and Pakuwon Mall, potential infrastructure aging after nearly two decades, and market saturation with over 20 malls in Surabaya leading to selective consumer spending influenced by economic pressures on the middle class.
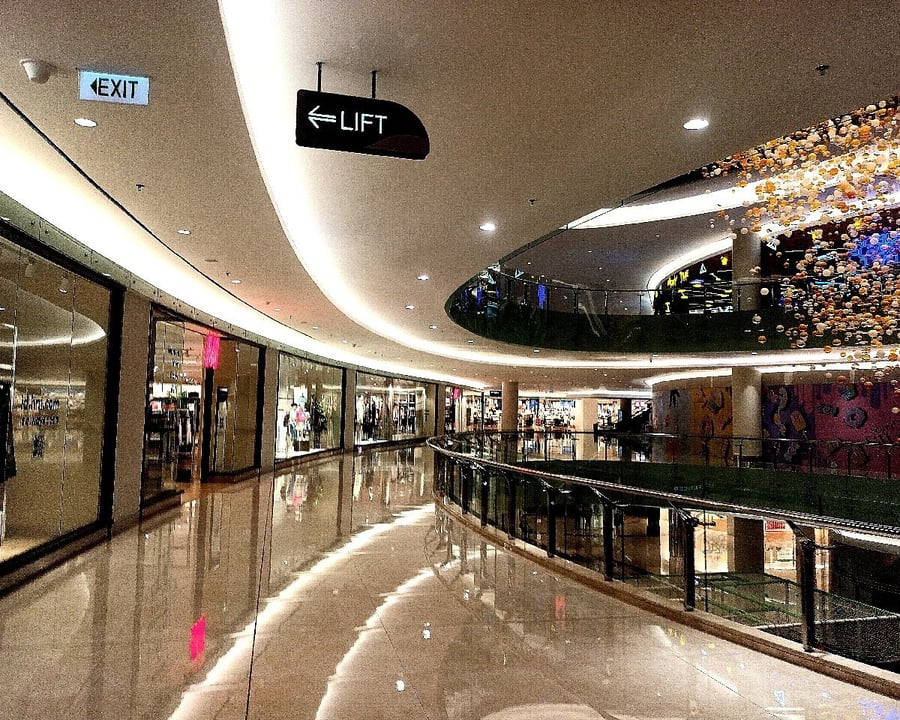
Operational quality is solid with modern facilities, but occasional access issues during peak traffic and a focus on family-oriented categories may limit appeal to luxury segments.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile
Grand City Surabaya serves a primarily urban middle-class demographic in Surabaya, with over 3 million city residents and a metropolitan area exceeding 10 million as of 2024. Target shoppers are aged 18-45, including young professionals, families, and students, drawn from nearby residential areas like Gubeng and Wonokromo. Household incomes range from IDR 5-15 million monthly, supporting spending on mid-range fashion, dining, and entertainment. Footfall estimates reach 10,000-15,000 daily visitors on weekdays, peaking at 25,000 on weekends per local market insights, bolstered by proximity to educational institutions and offices. However, economic slowdowns could reduce discretionary spending in weaker categories like non-essential retail.
Competitive Landscape
In Surabayas saturated retail market with more than 20 malls totaling over 2 million square meters of space, Grand City faces strong competition from established players like Tunjungan Plaza (occupancy 95%+, anchor-heavy with luxury brands) and Pakuwon Mall (91-98% occupancy, integrated lifestyle hub). These rivals draw higher-end demographics and international tourists, potentially diverting footfall from Grand Citys mid-market positioning. Strengths include its MICE facilities hosting events that generate additional traffic, but risks involve tenant churn in fashion and F&B due to overlapping offerings and e-commerce growth eroding physical sales by 10-15% annually. Market reports note selective leasing favoring experiential tenants to counter competition.
Occupancy and Rent Metrics
Surabaya retail occupancy averaged 76% in 2025, with Grand City maintaining around 80-85% based on similar mid-tier malls, supported by stable anchors but challenged by vacant spaces in secondary categories amid post-pandemic recovery. Rent levels are tiered: prime ground-floor spots at IDR 800,000-1,000,000 per square meter monthly, upper floors at IDR 400,000-600,000, including CAM charges of 10-15% of gross rent. Leasing terms offer 3-5 year commitments with escalation clauses of 5-8% annually, plus turnover rent options for high-traffic food tenants. Drawbacks include negotiation pressures from high vacancy risks in saturated segments and infrastructure maintenance costs impacting net yields, though data-driven tenant mix adjustments could enhance performance.
Building Details
Detailed Market Analytics
City Snapshot
Surabaya
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Surabaya
Discover more shopping centers in Surabaya.


Popular in Indonesia
Top retail destinations across Indonesia.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Surabaya
Comprehensive market intelligence for retail expansion in this city