
Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
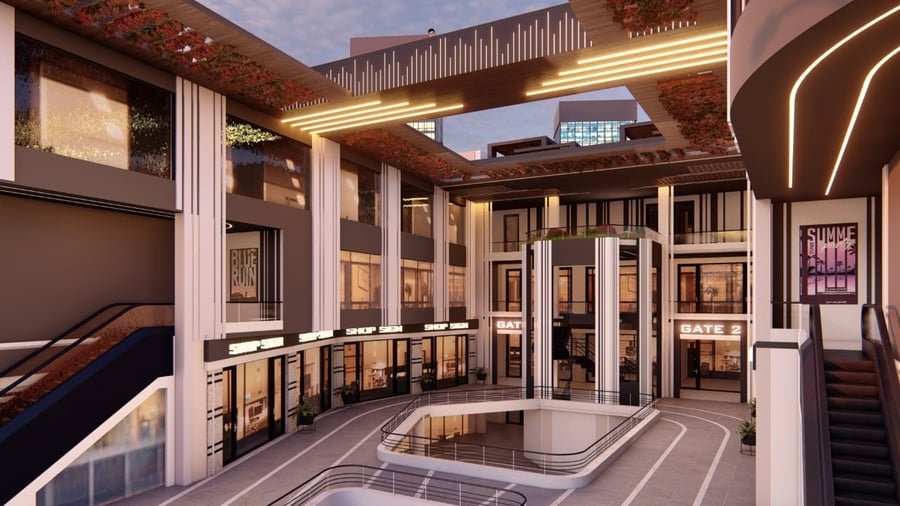
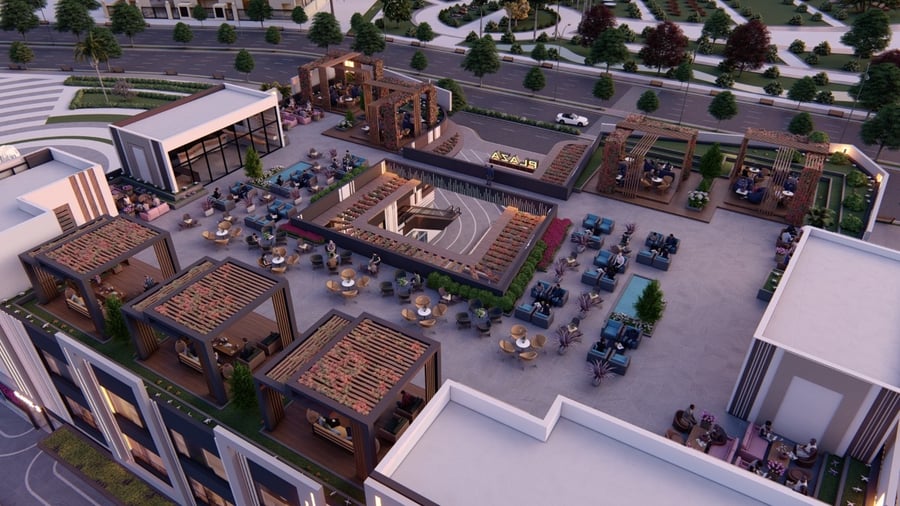
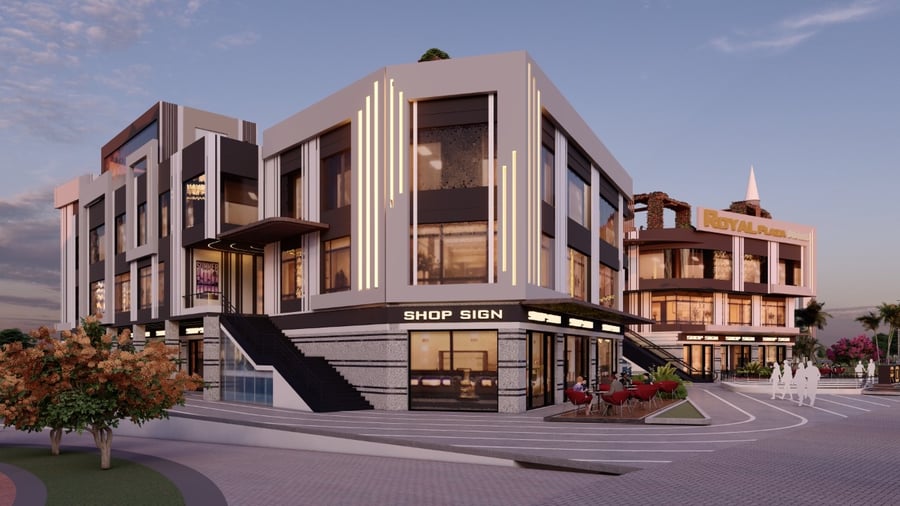
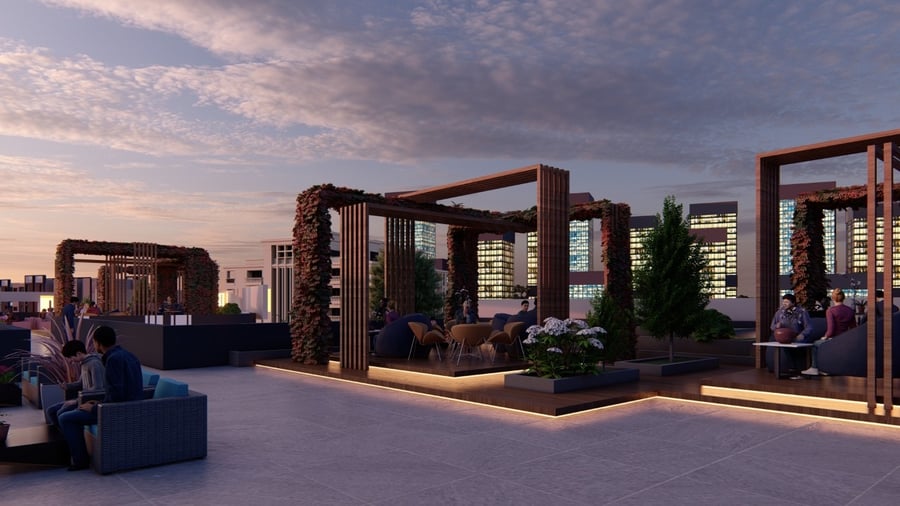
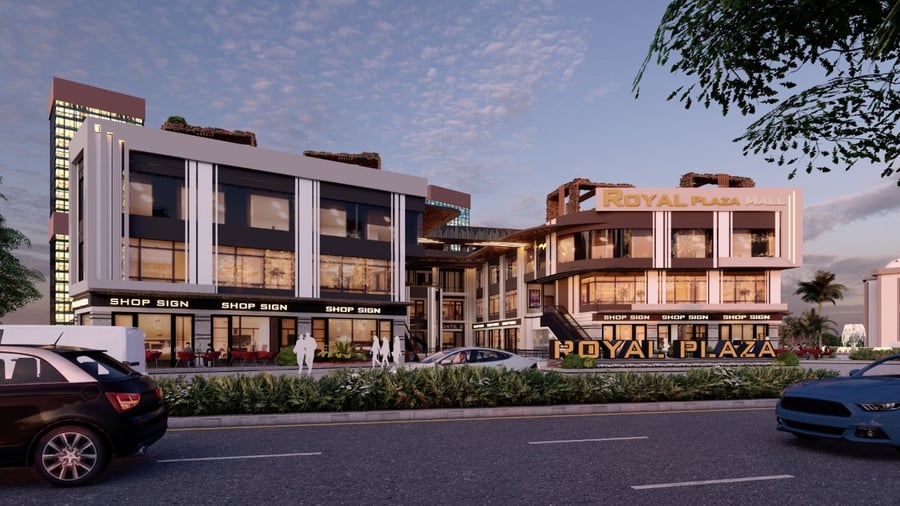
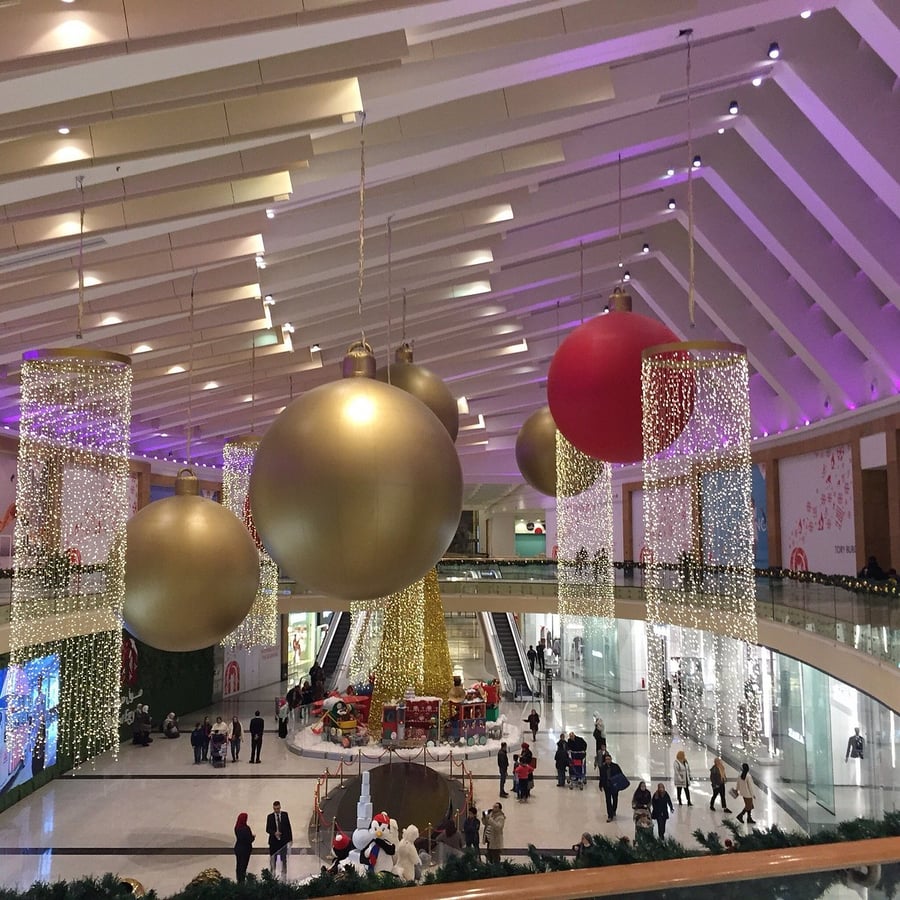
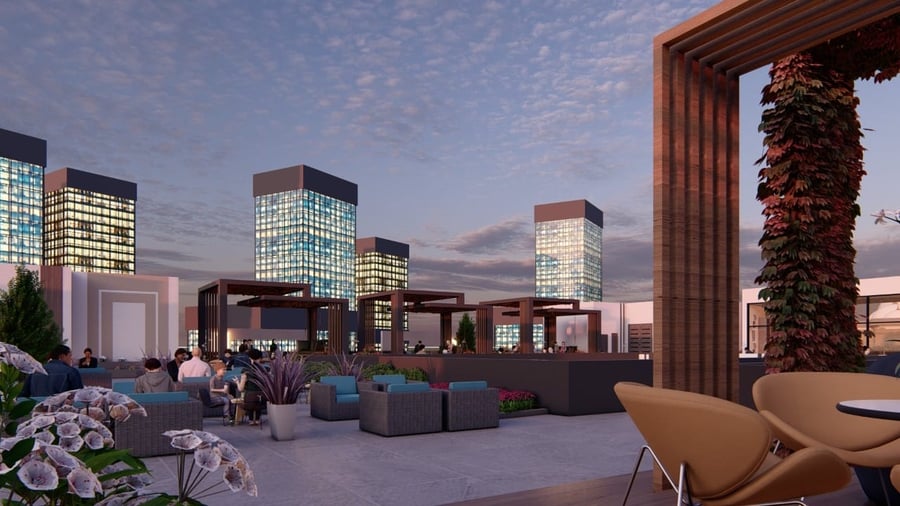
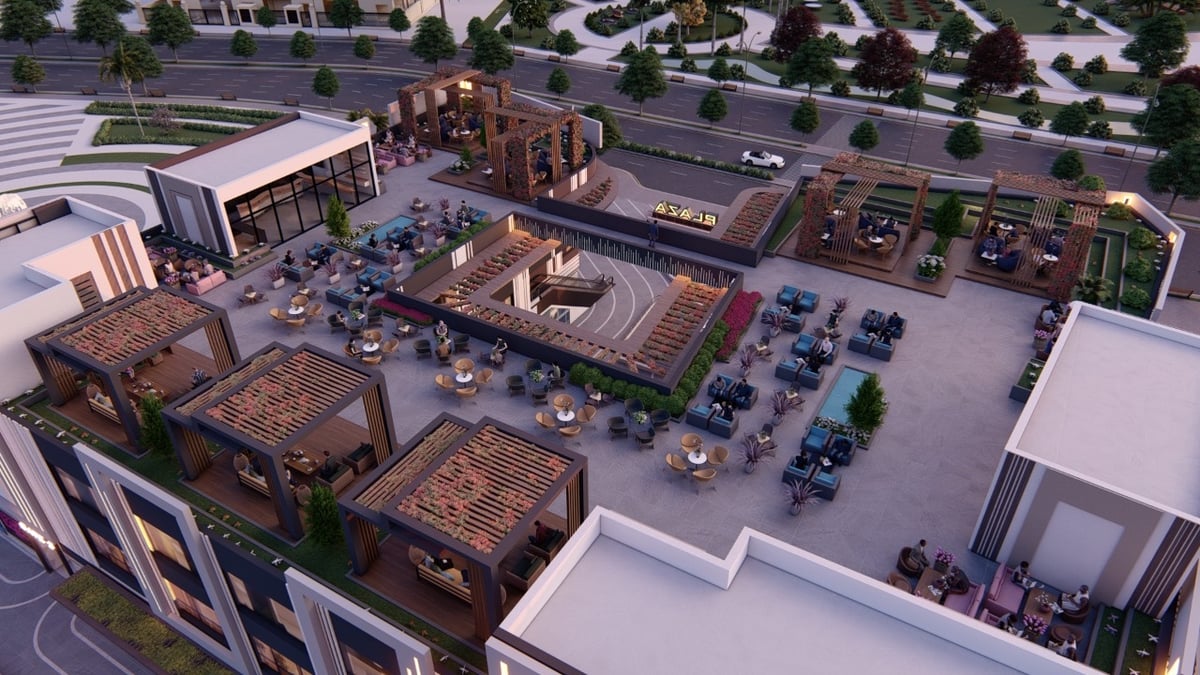
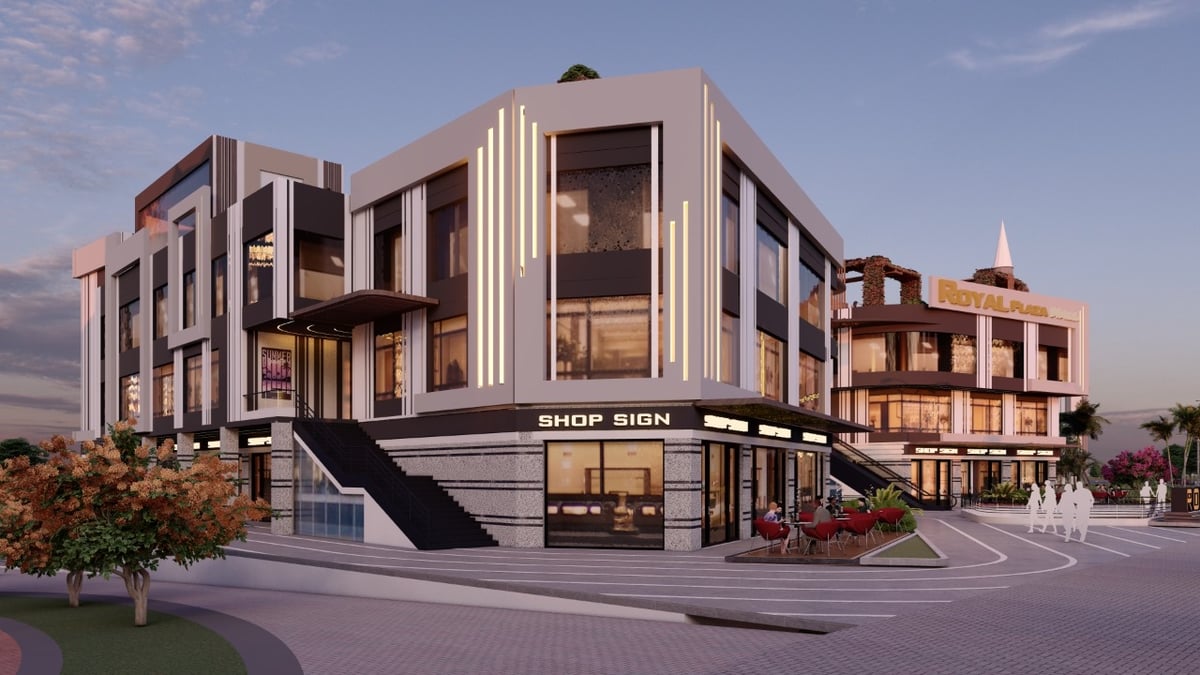
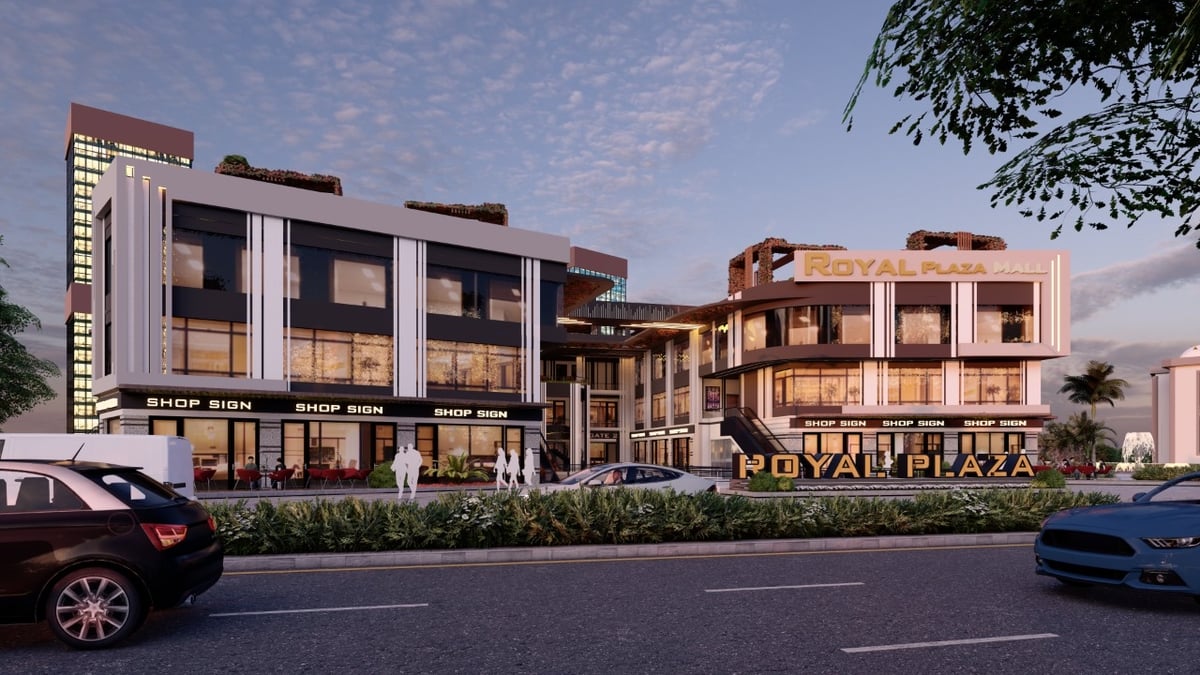
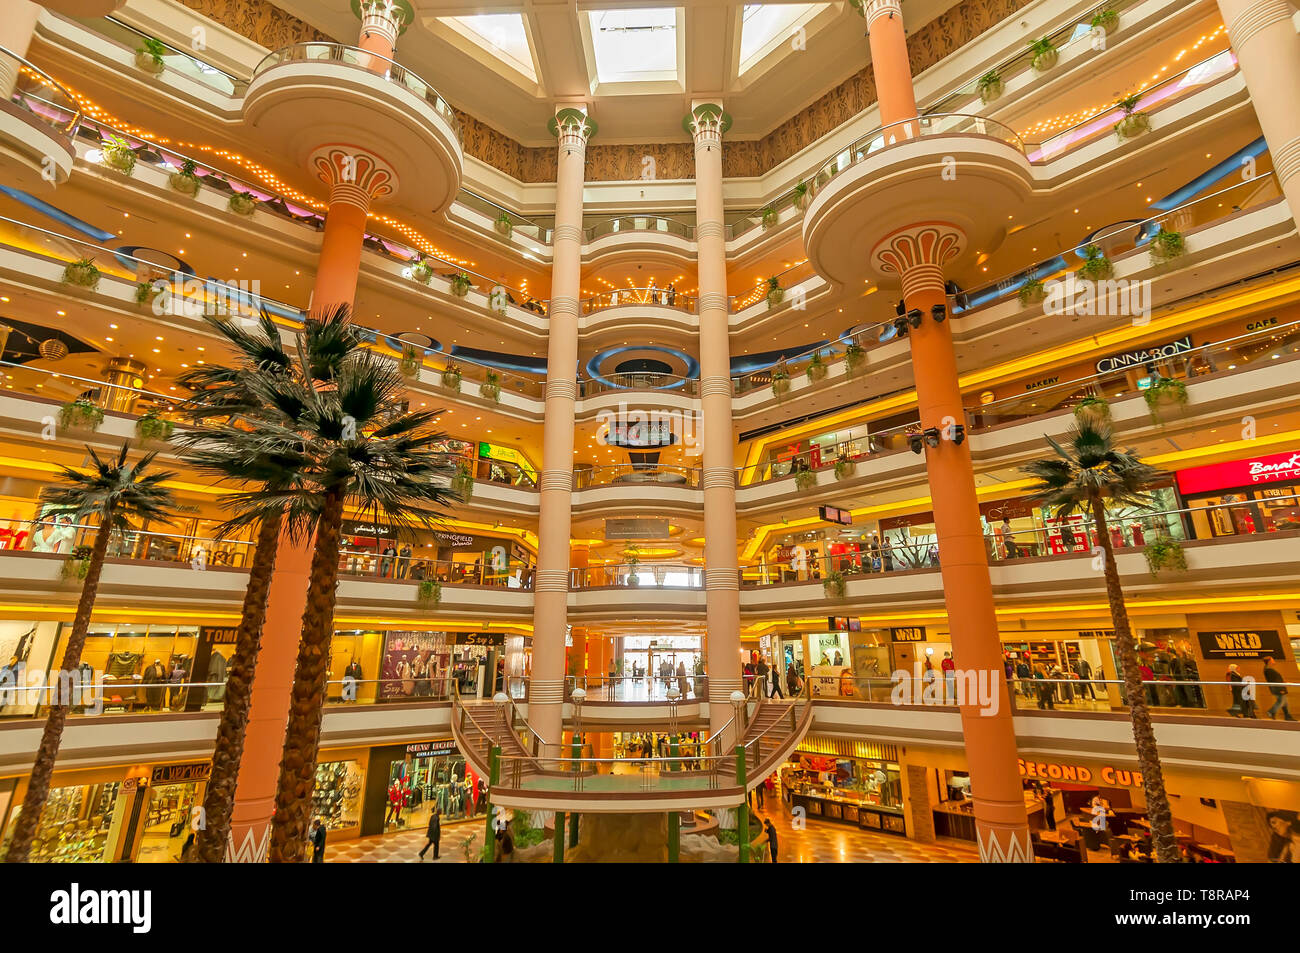
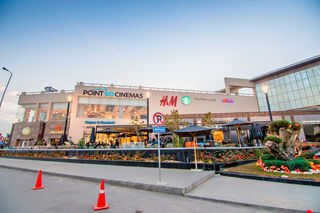
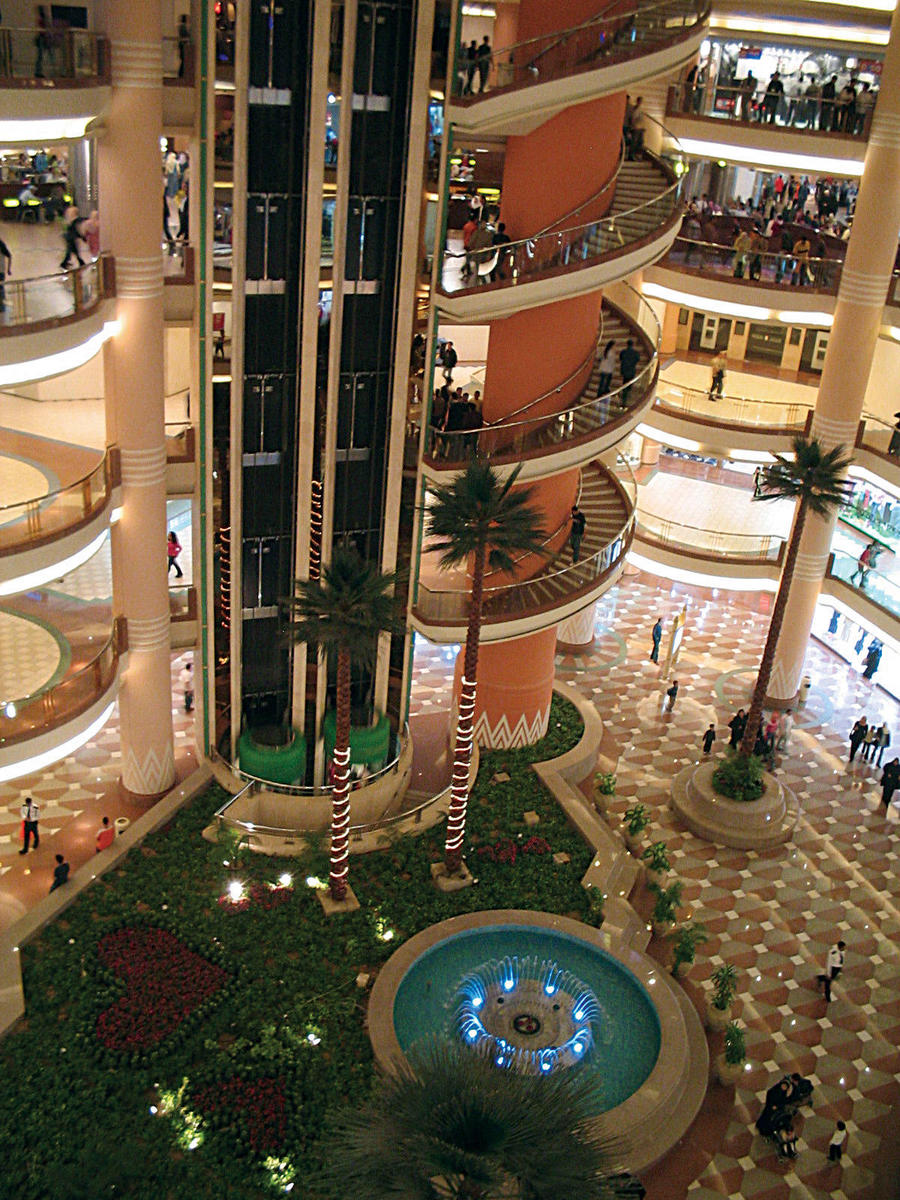
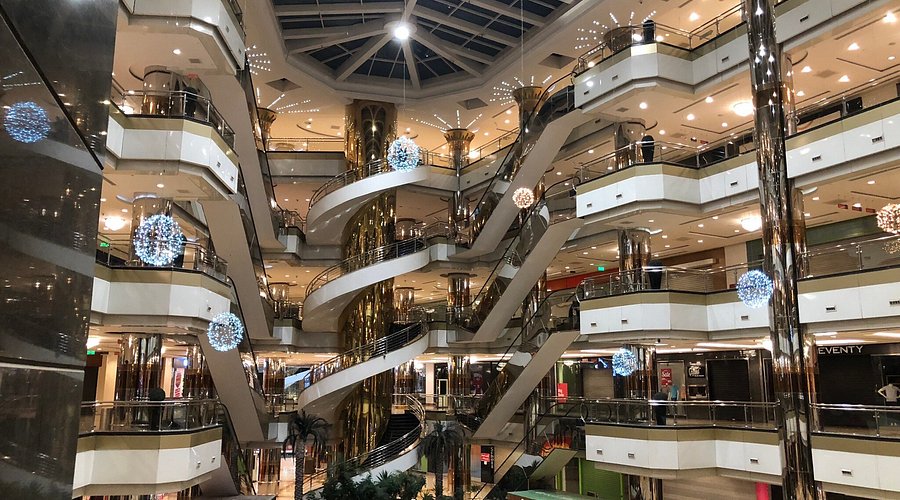
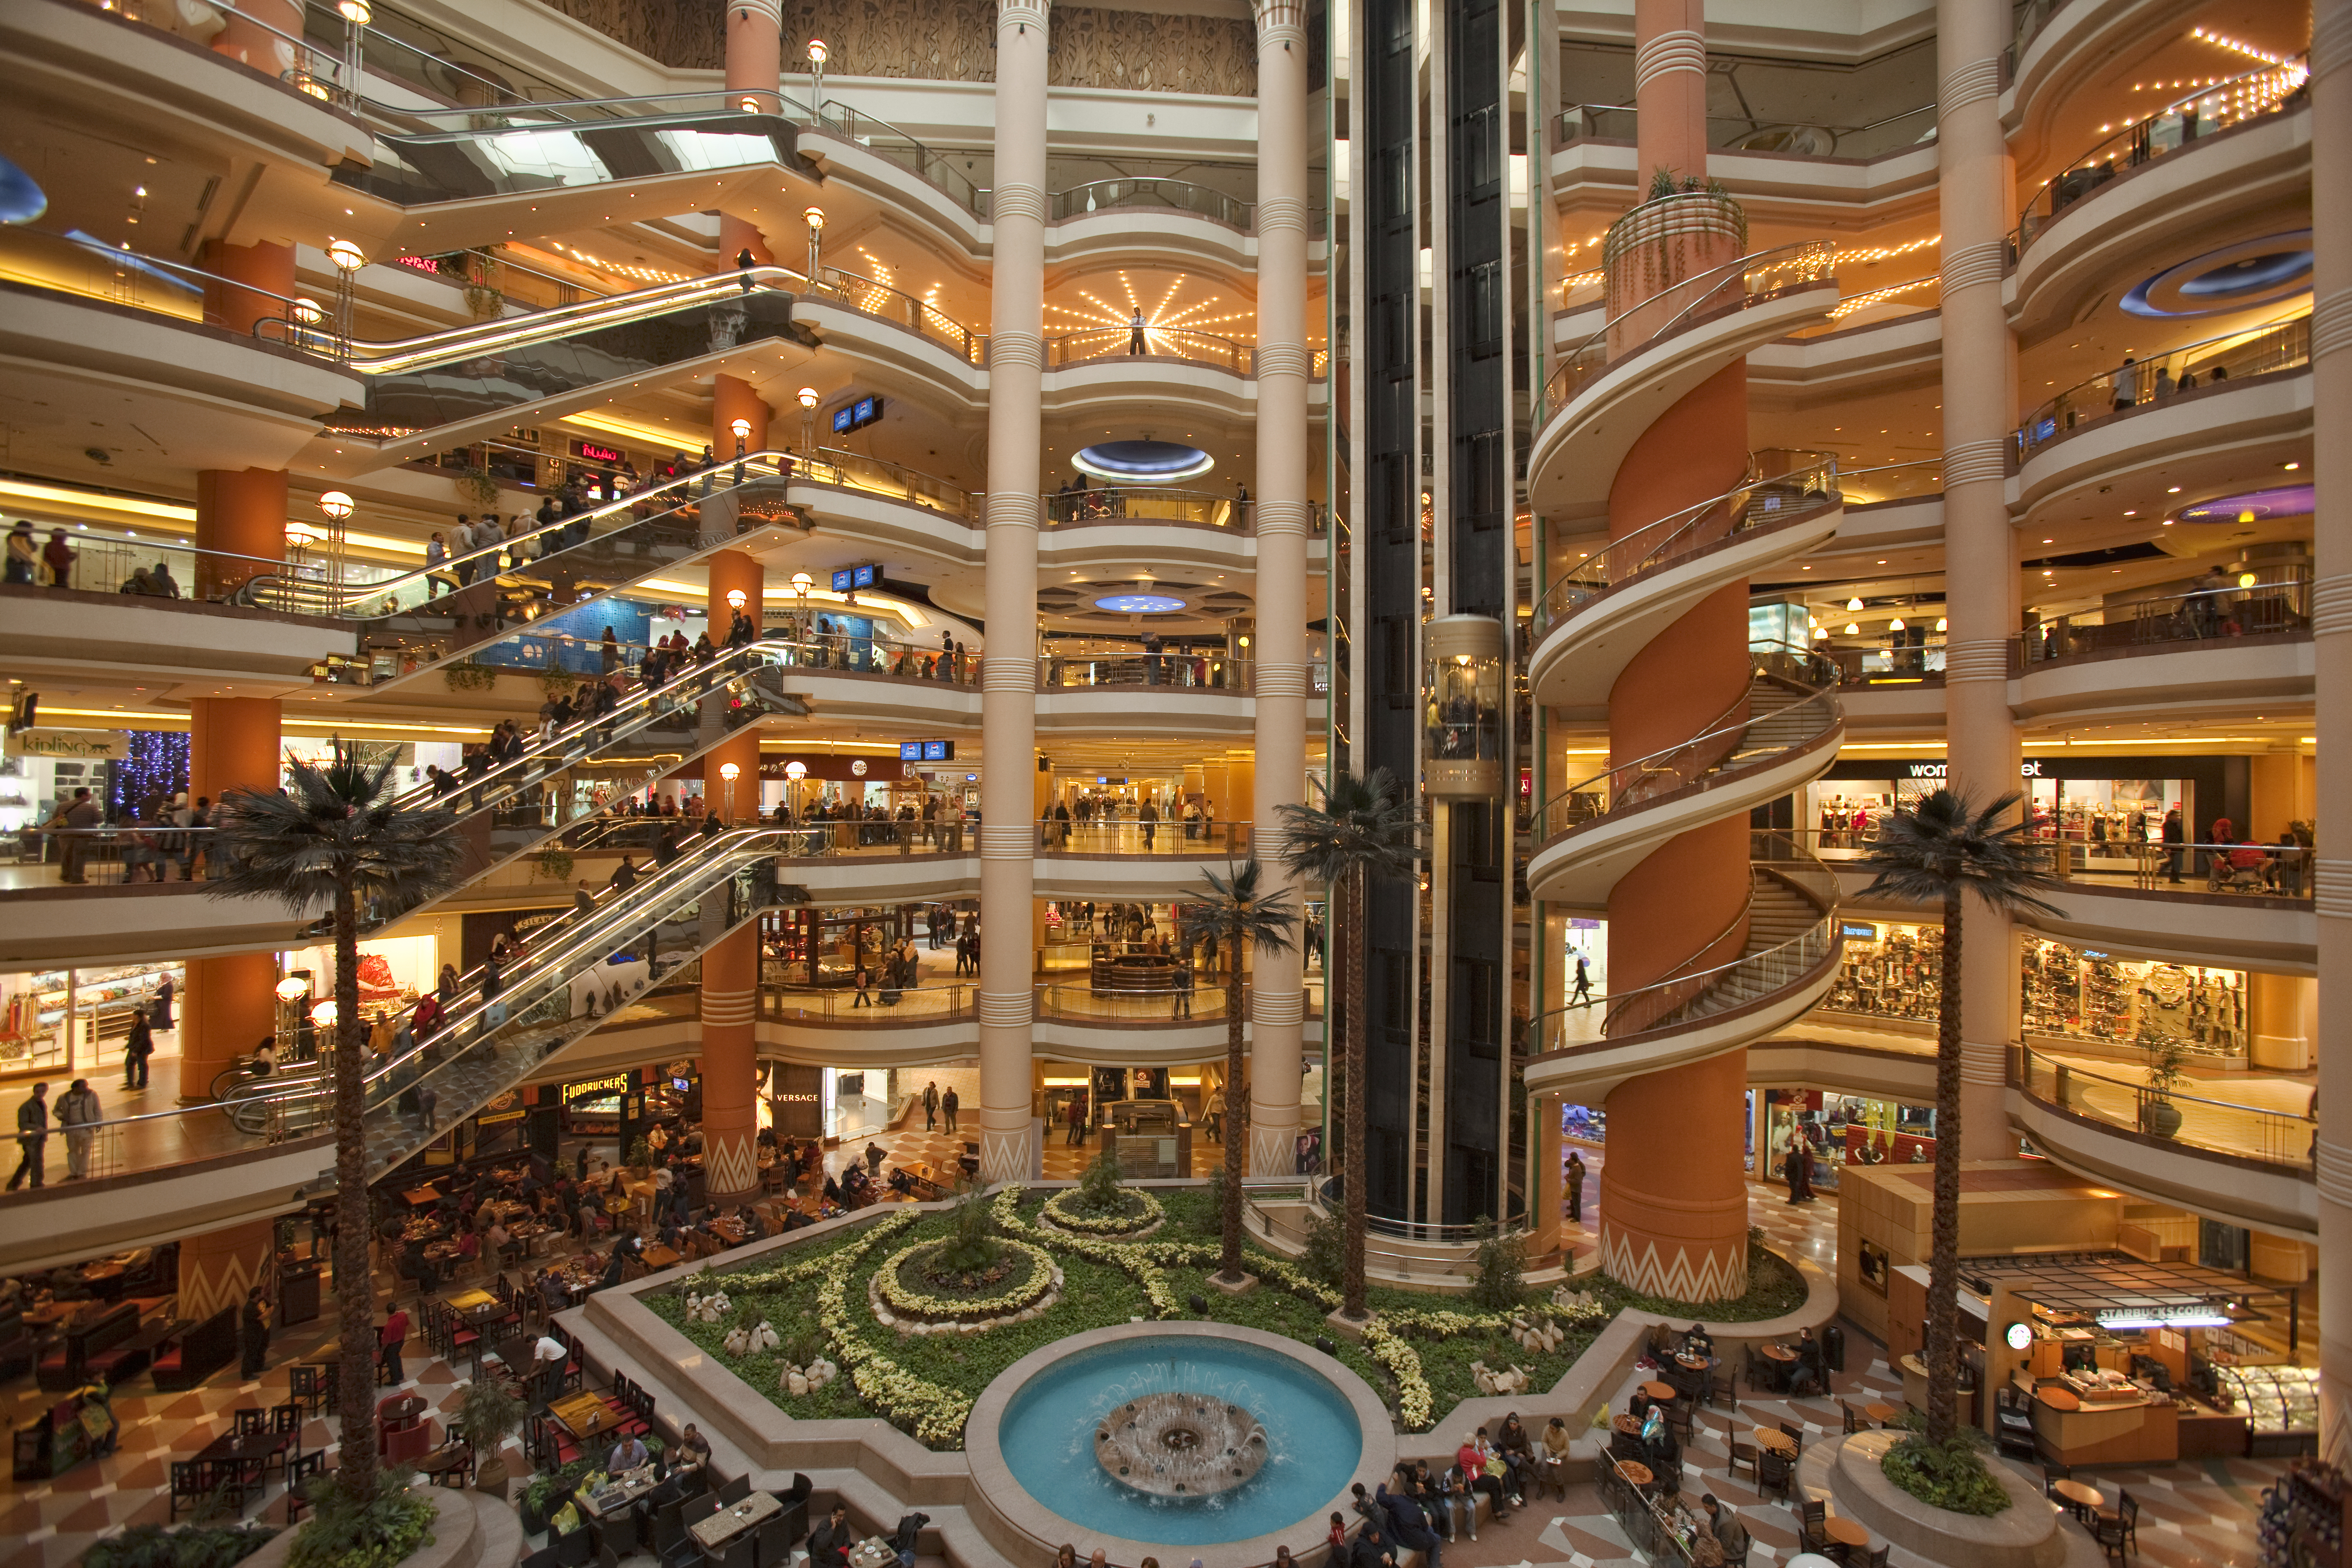
Royal Mall is a mid-sized, three-floor commercial center located in 6th of October City, Egypt, along the service axis near El Hosary Square. Developed as a community-focused retail destination, it spans approximately 20,000 square meters of gross leasable area, targeting middle-income residents in this rapidly expanding suburb of Greater Cairo. The property opened in the early 2010s and has undergone minor renovations to maintain operational quality.
Its market position is as a neighborhood mall, serving daily shopping needs rather than regional draw, with footfall estimated at 6,000 to 10,000 visitors per day based on local traffic patterns reported in Cairo retail analyses. Occupancy stands at around 85%, aligning with the Q2 2025 Cairo retail vacancy rate of 7.2% per JLL market dynamics, indicating stable demand amid economic recovery.
Tenant mix comprises 35% fashion and accessories (local and mid-tier brands like Flormar), 25% food and beverage (quick-service outlets and cafes), 20% health and pharmacy services, and 20% miscellaneous including electronics and services; this balanced composition supports cross-shopping but shows weakness in luxury categories.
Rent levels average EGP 700-1,100 per square meter annually, competitive for small-format retailers compared to prime malls like Mall of Arabia at EGP 1,500+.
Accessibility is facilitated by proximity to Dahshur Link Road and the Ring Road, with public transport options, though private vehicle dependency is high and parking capacity (about 300 spaces) can be strained during peaks.
Demographic profile includes young families and professionals aged 25-45, with household incomes of EGP 15,000-30,000 monthly, drawn from nearby residential compounds.
Leasing advantages include flexible lease terms (3-5 years) and turnover rents tied to sales, aiding new entrants in a market with 7% CAGR growth to 2025 per regional reports. However, challenges encompass intense competition from larger venues like Mall of Egypt (50,000+ daily footfall), potential aging infrastructure requiring capex, and category saturation in F&B amid rising operational costs from inflation.
Overall, it offers practical opportunities for local brands but requires careful risk assessment regarding economic fluctuations and access improvements.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 11:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
6th of October City hosts over 600,000 residents, predominantly middle-class families and young professionals with median household incomes of EGP 20,000 monthly, per 2025 demographic studies. Royal Mall draws from a 5-km catchment area, generating moderate footfall of 7,500 visitors daily on weekdays and up to 12,000 on weekends, supported by local residential density but limited by lack of major anchors. This contrasts with regional averages of 20,000+ for prime malls, highlighting its community role while exposing it to risks from shifting consumer preferences toward online retail, which captured 15% of sales in Egypt by 2025.
Tenant Mix and Occupancy
The tenant mix emphasizes everyday essentials with 40% retail (fashion, beauty via stores like Flormar), 30% F&B (local eateries and chains), and 30% services (pharmacies, clinics), fostering steady traffic but vulnerable to weak performance in non-essential categories during downturns. Occupancy rate of 88% exceeds the Cairo suburban average of 82%, reflecting strong local demand and proactive management, though recent reports note 5% vacancy in similar properties due to anchor tenant relocations. This stability aids leasing but underscores the need for diversified mix to mitigate sector-specific slumps.
Rent Levels and Competition
Average rents range from EGP 800 per square meter yearly for ground-floor units to EGP 600 for upper levels, below prime Cairo rates of EGP 1,200+ but pressured by 20% annual increases tied to inflation in 2025. Competitive advantages include lower entry barriers for SMEs, yet intense rivalry from nearby Mall of Arabia and Mall of Egypt, with their superior footfall and international brands, poses risks of tenant poaching and reduced sales potential (estimated 20-30% lower than competitors). Market saturation in fashion and F&B categories further challenges new leases, necessitating niche positioning.
Building Details
Detailed Market Analytics
City Snapshot
6th Of October City
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in 6th Of October City
Discover more shopping centers in 6th Of October City.

Popular in Egypt
Top retail destinations across Egypt.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
6th Of October City
Comprehensive market intelligence for retail expansion in this city