Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
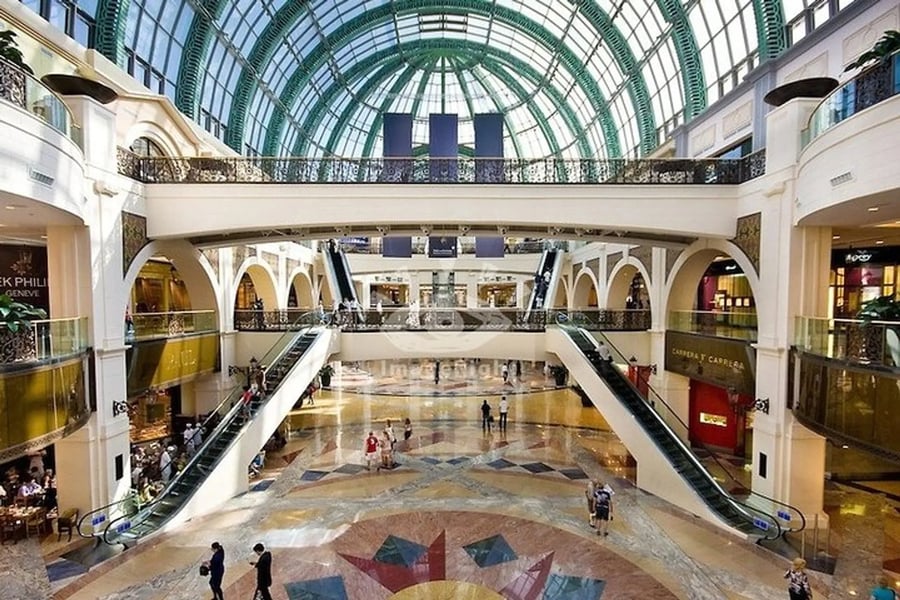
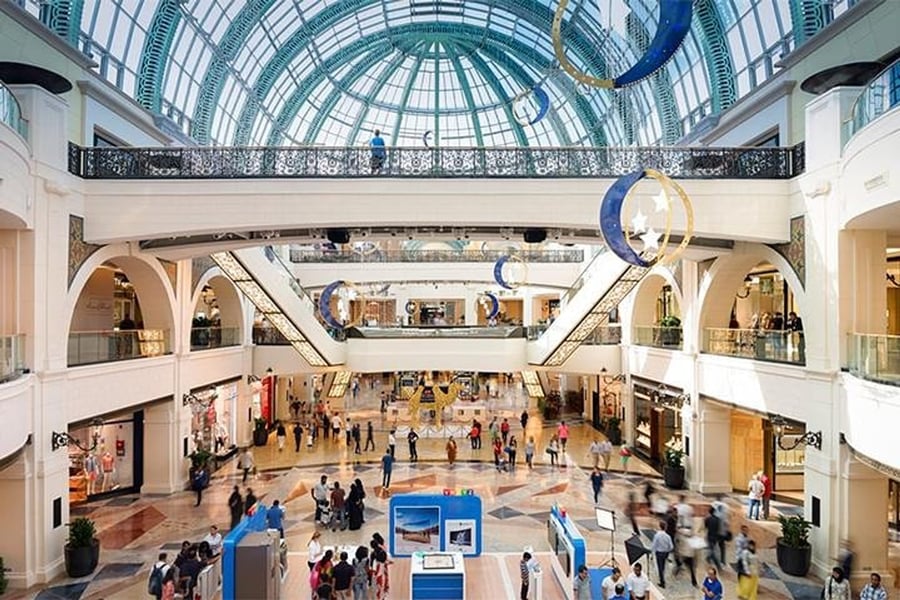
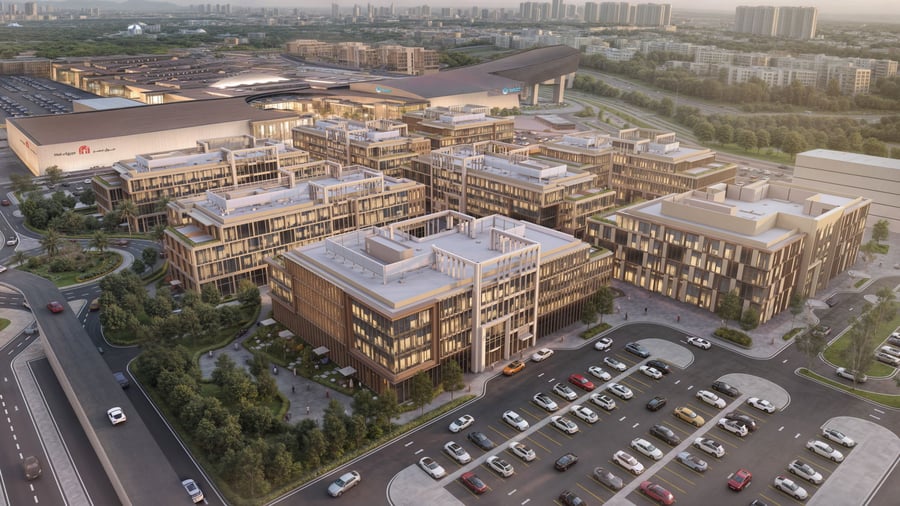
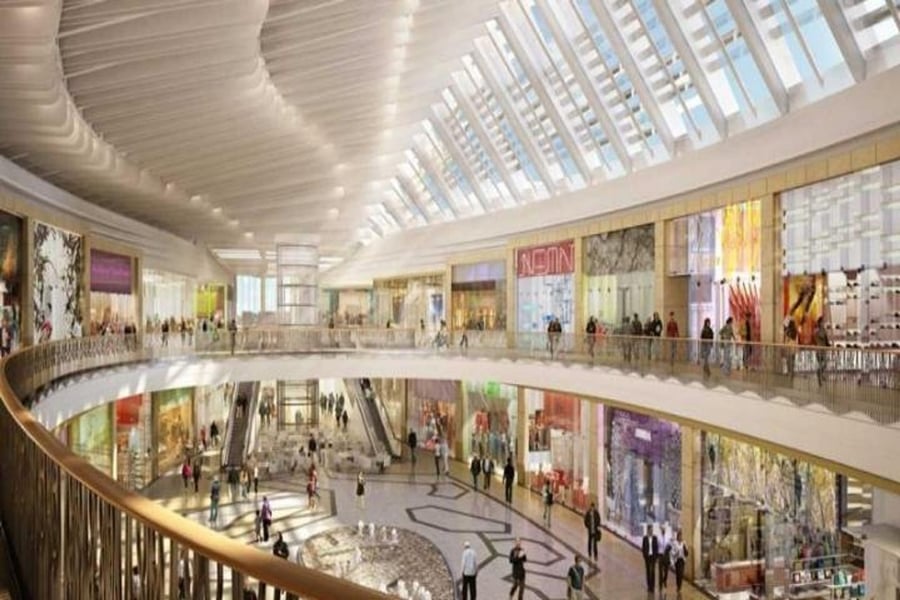
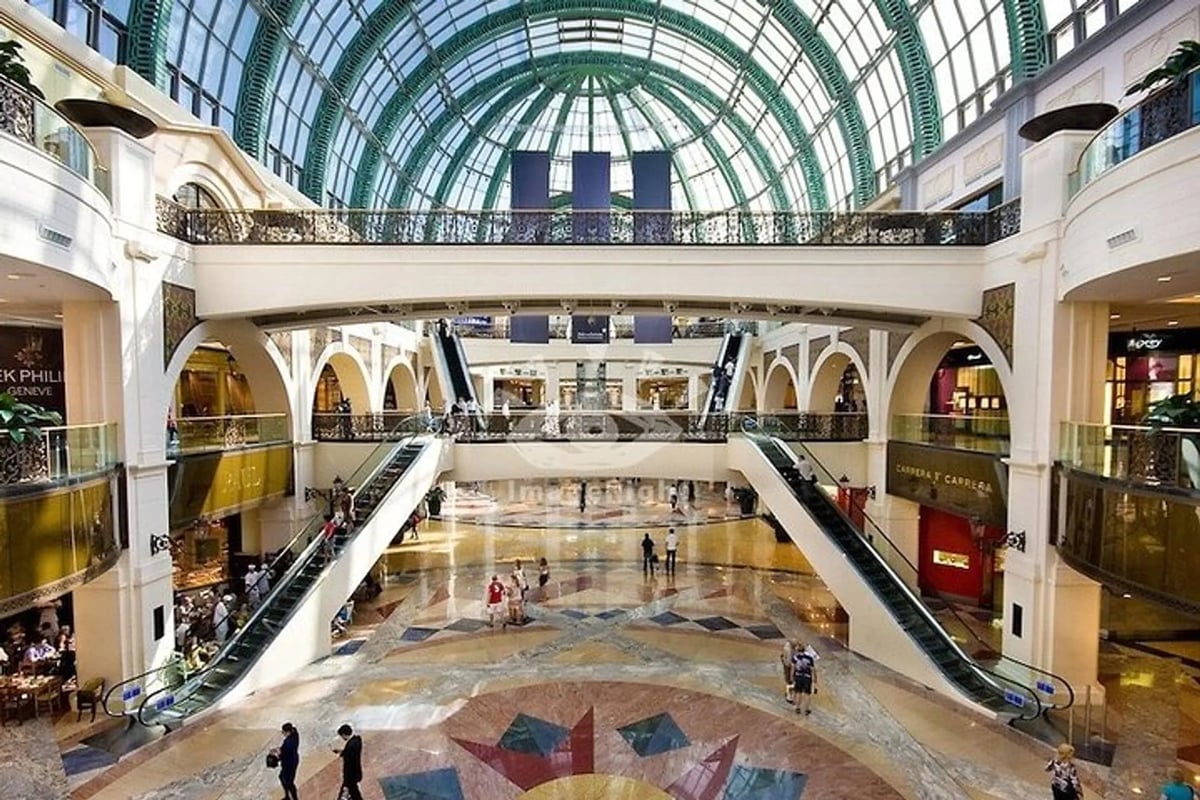
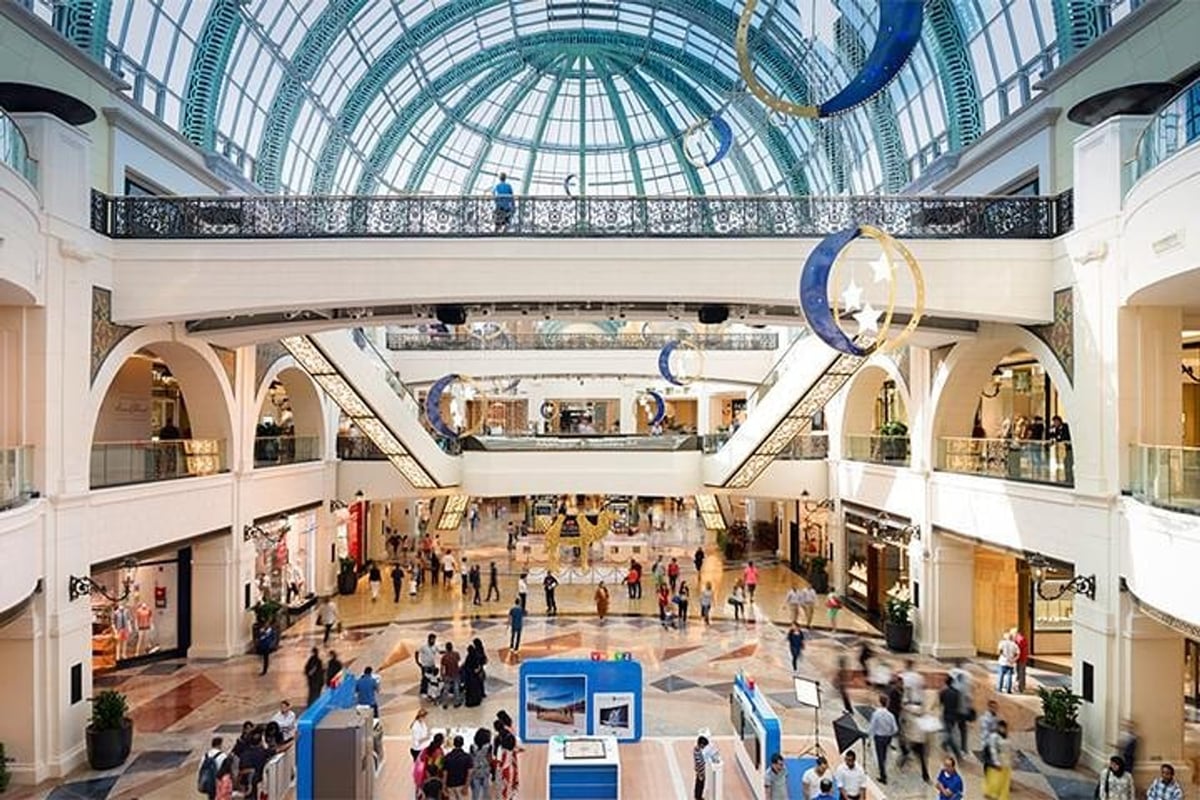
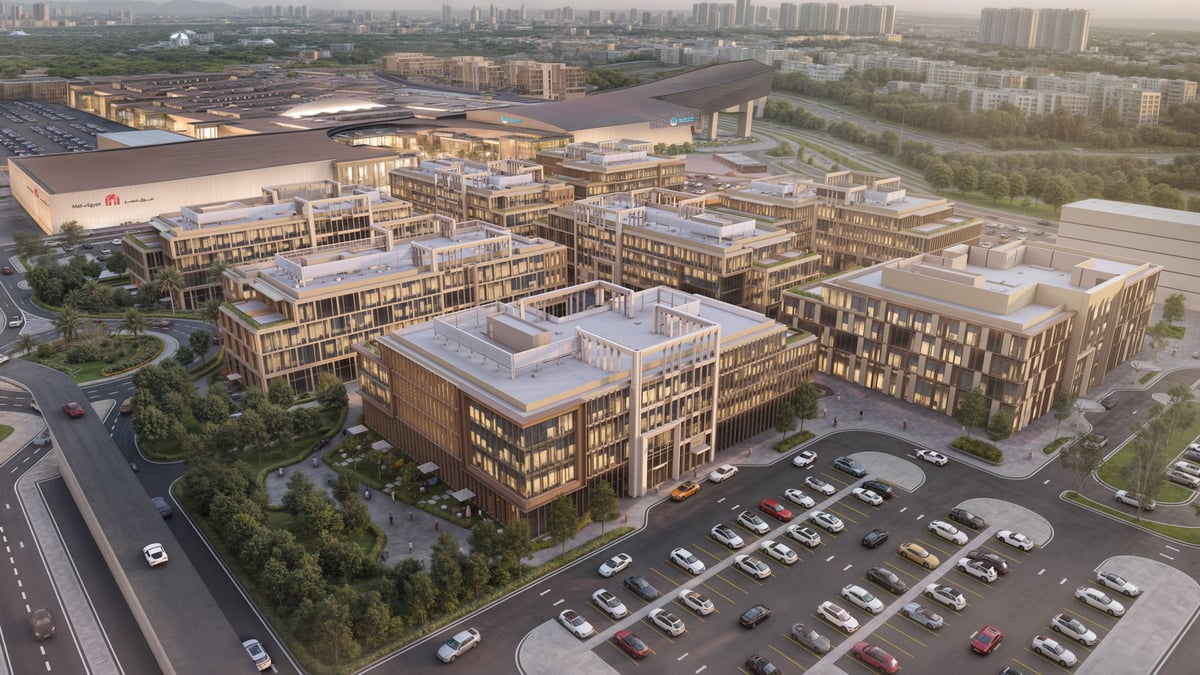
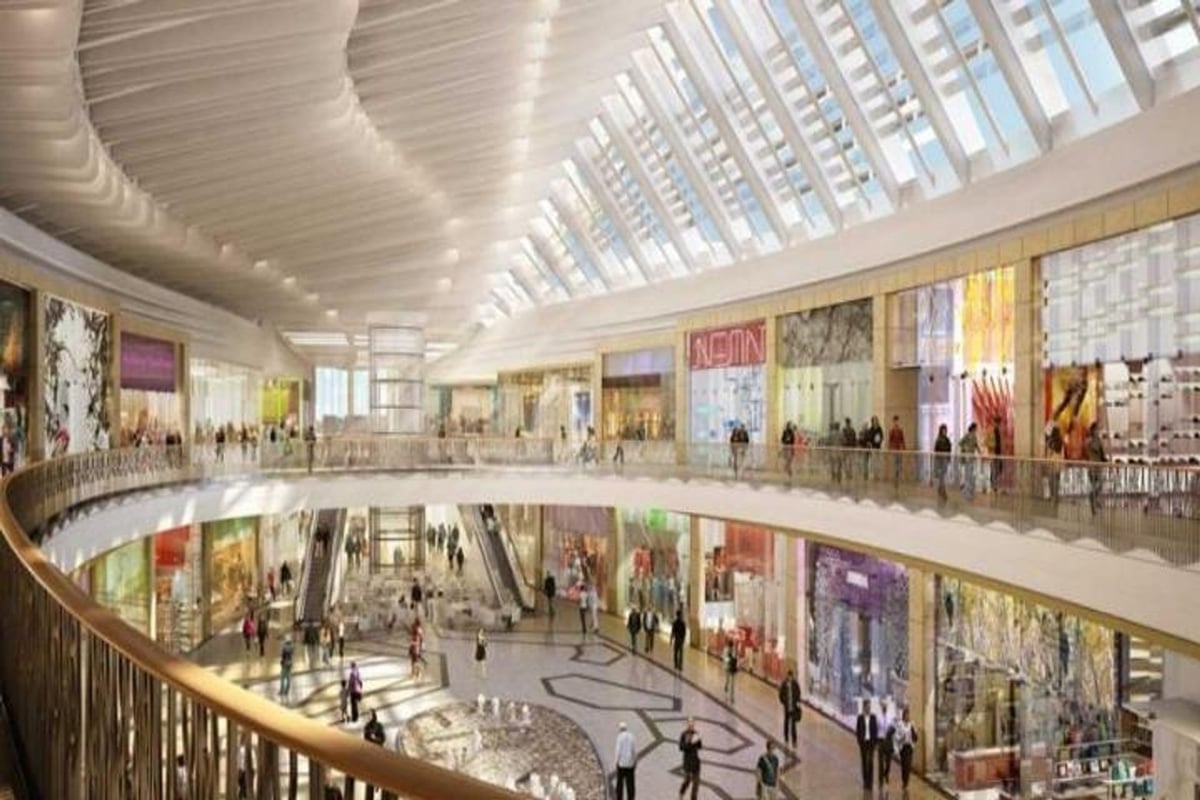
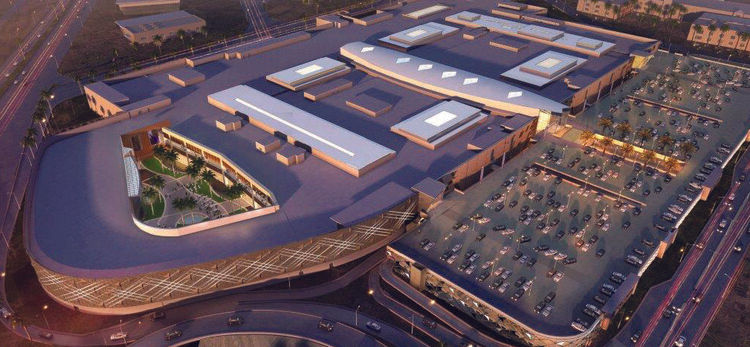
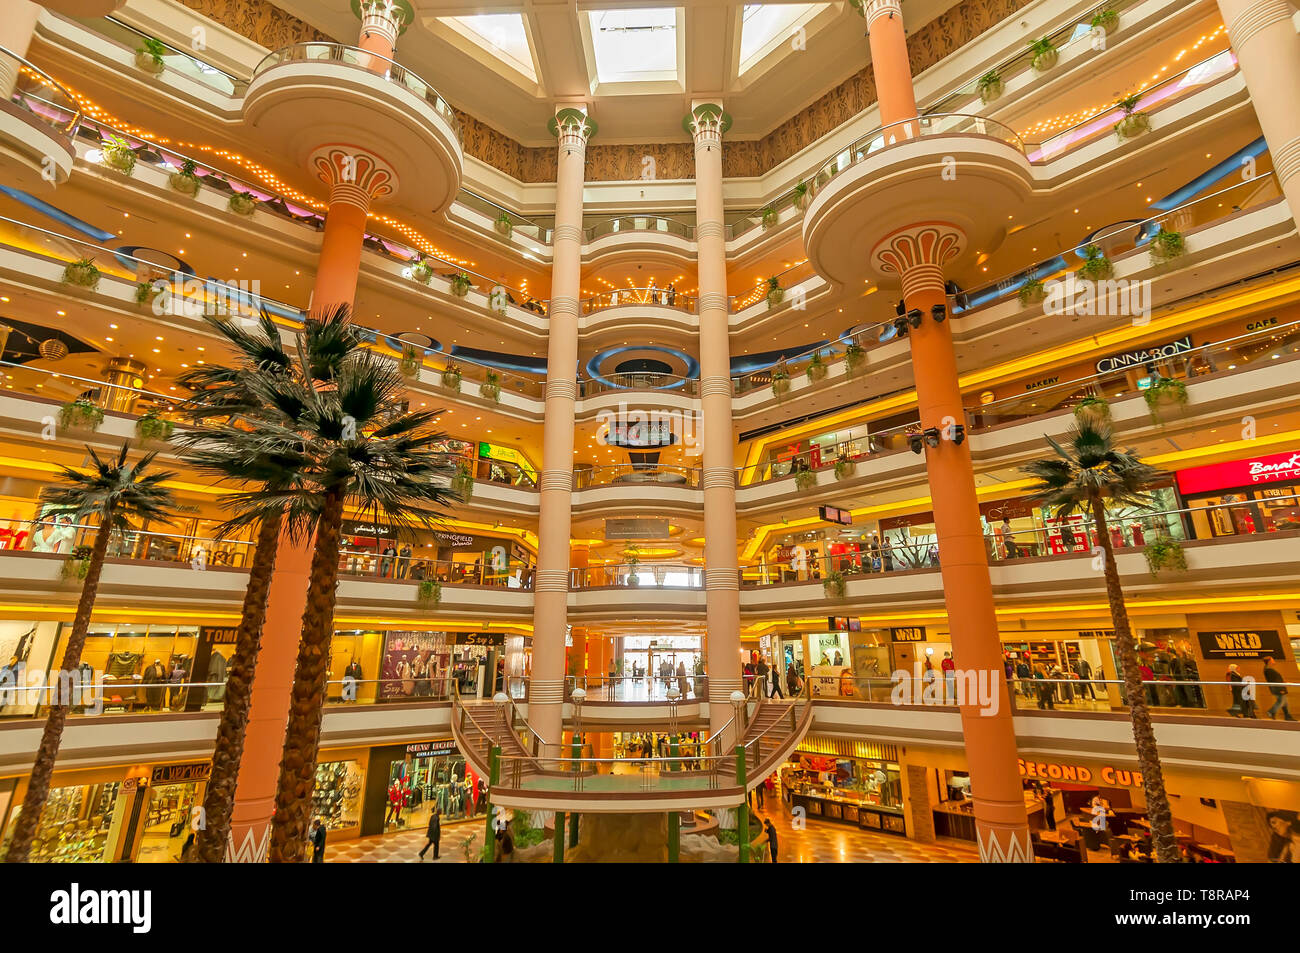
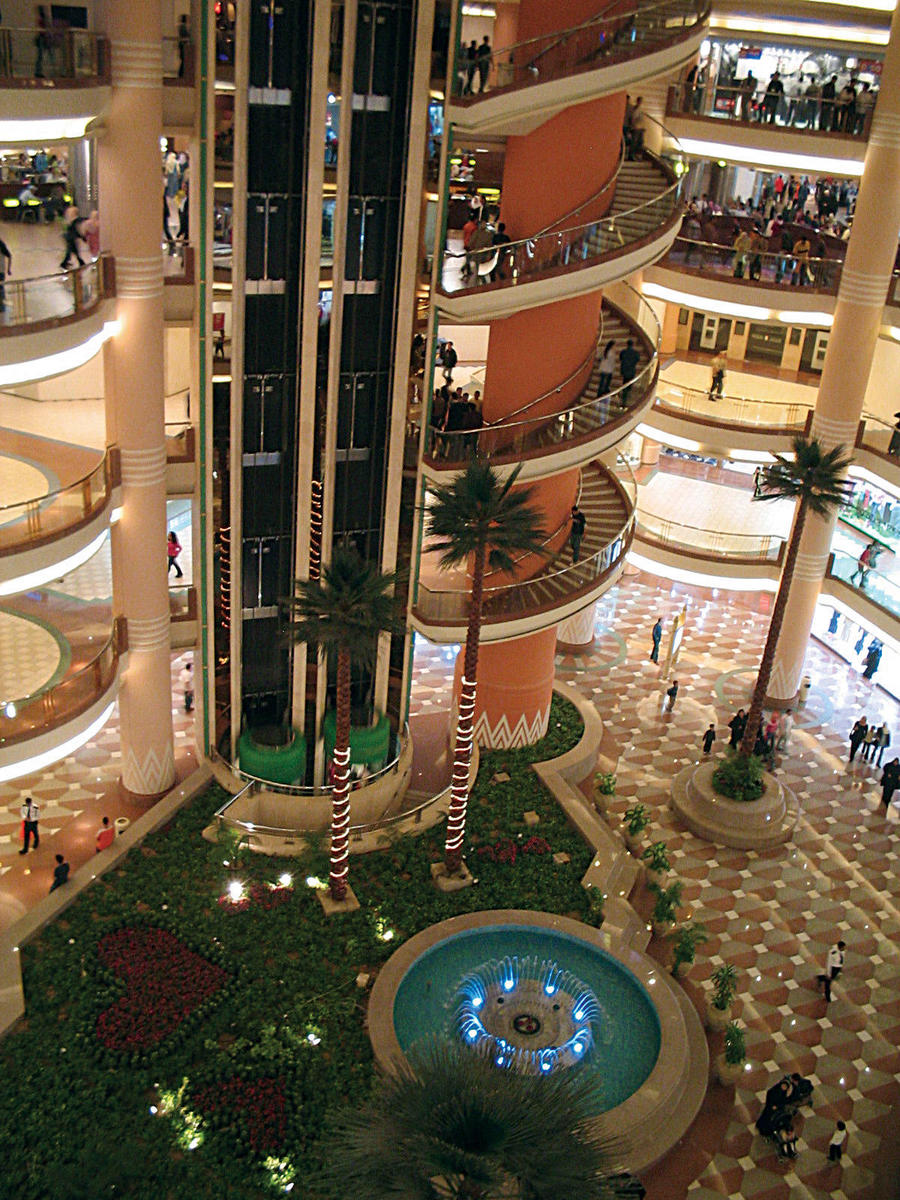
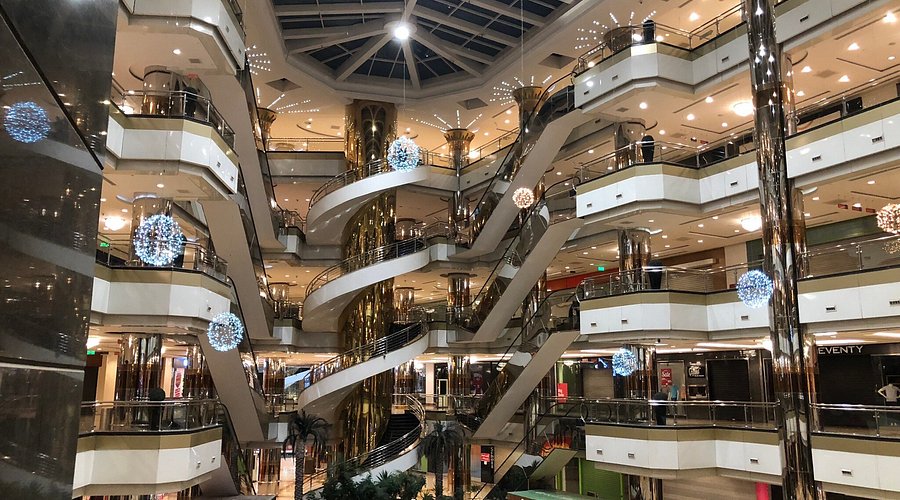
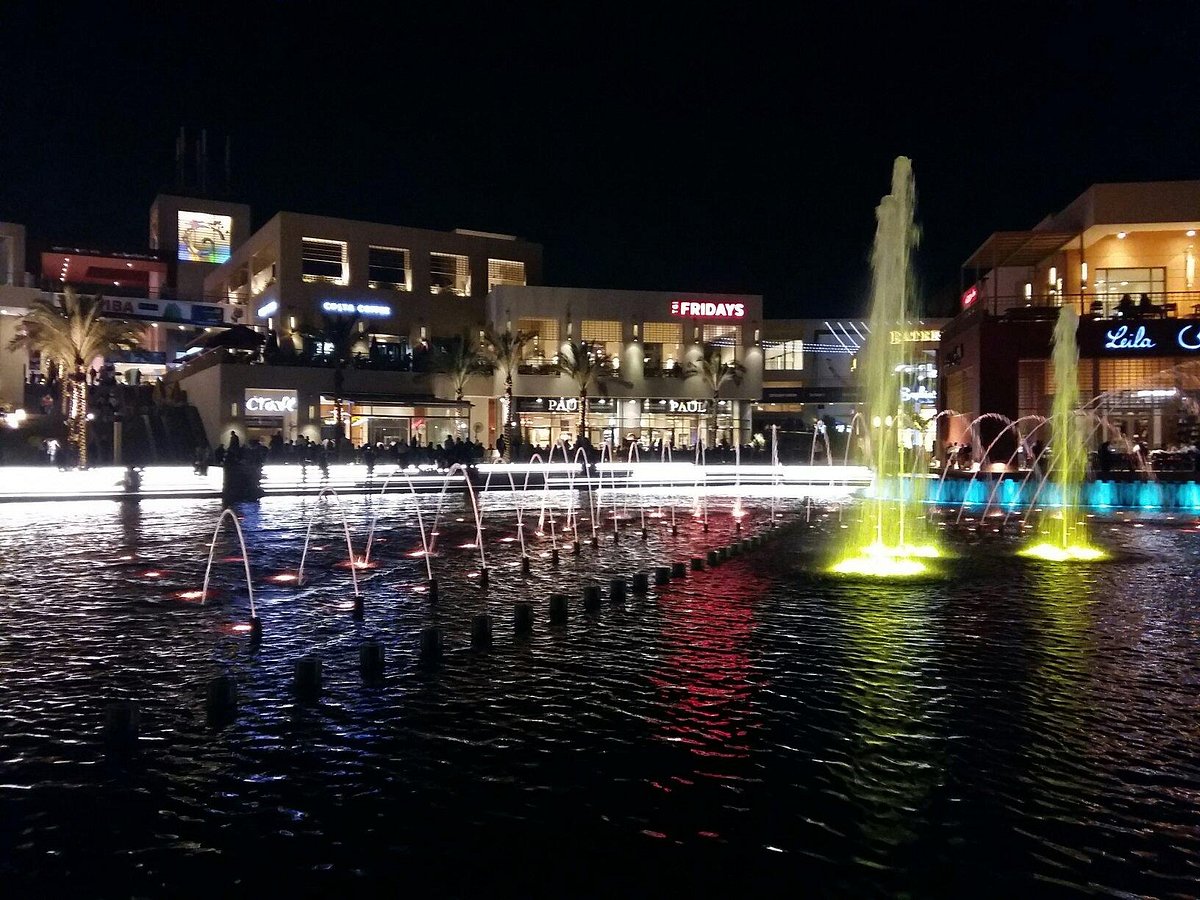
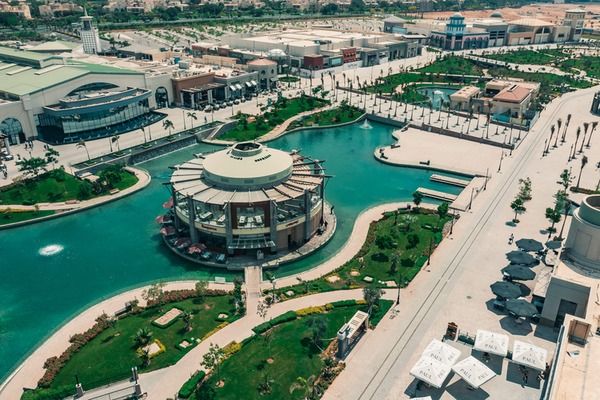
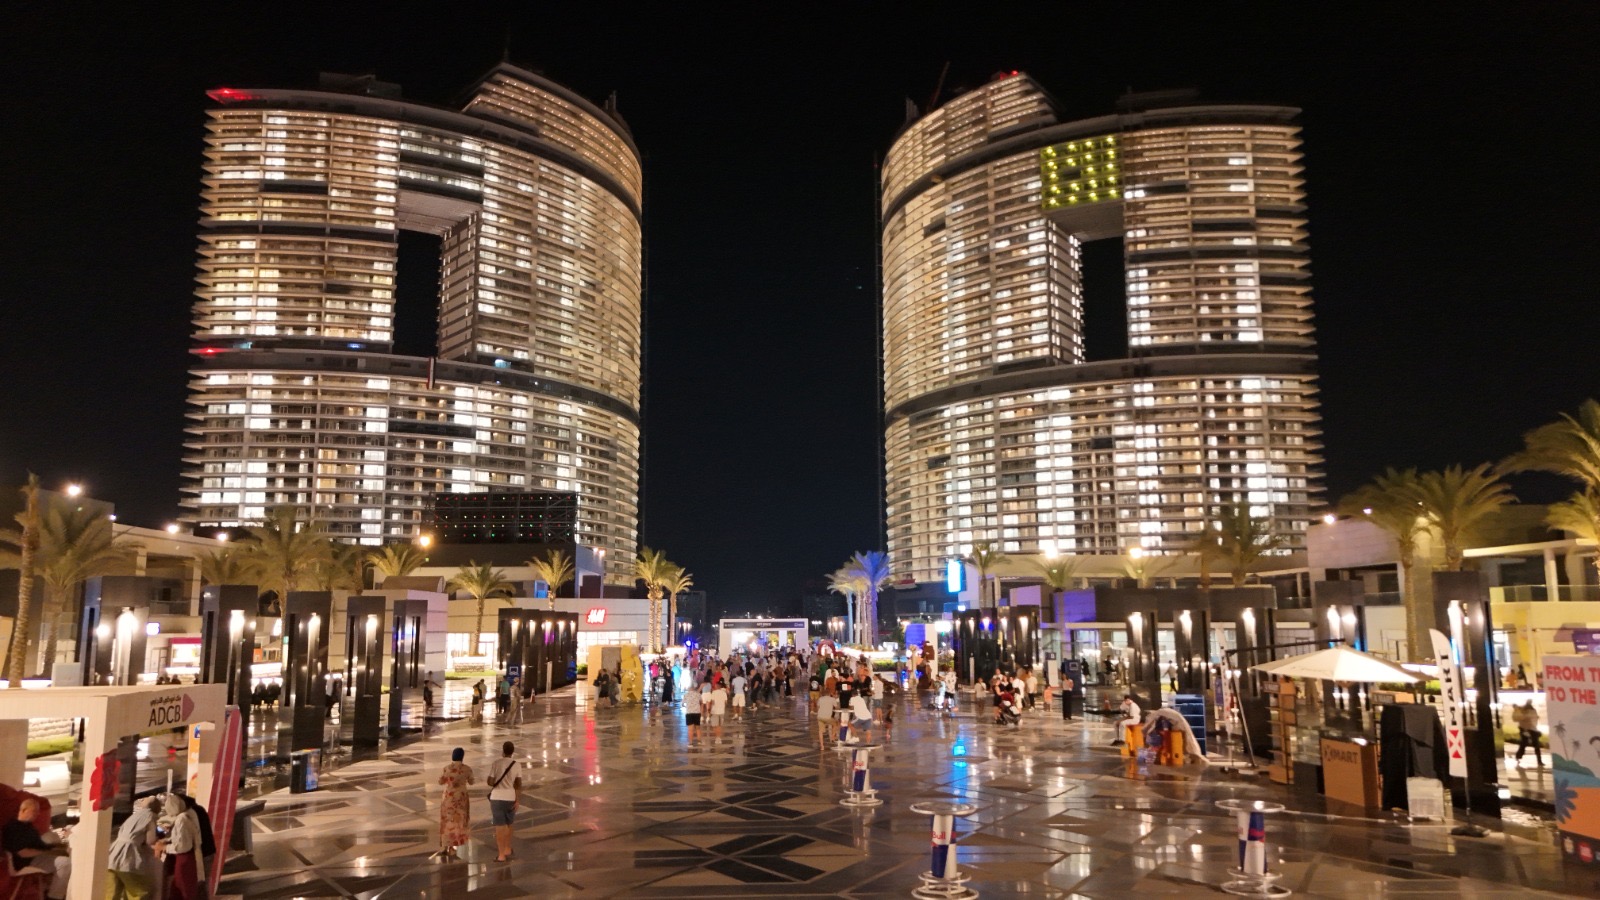
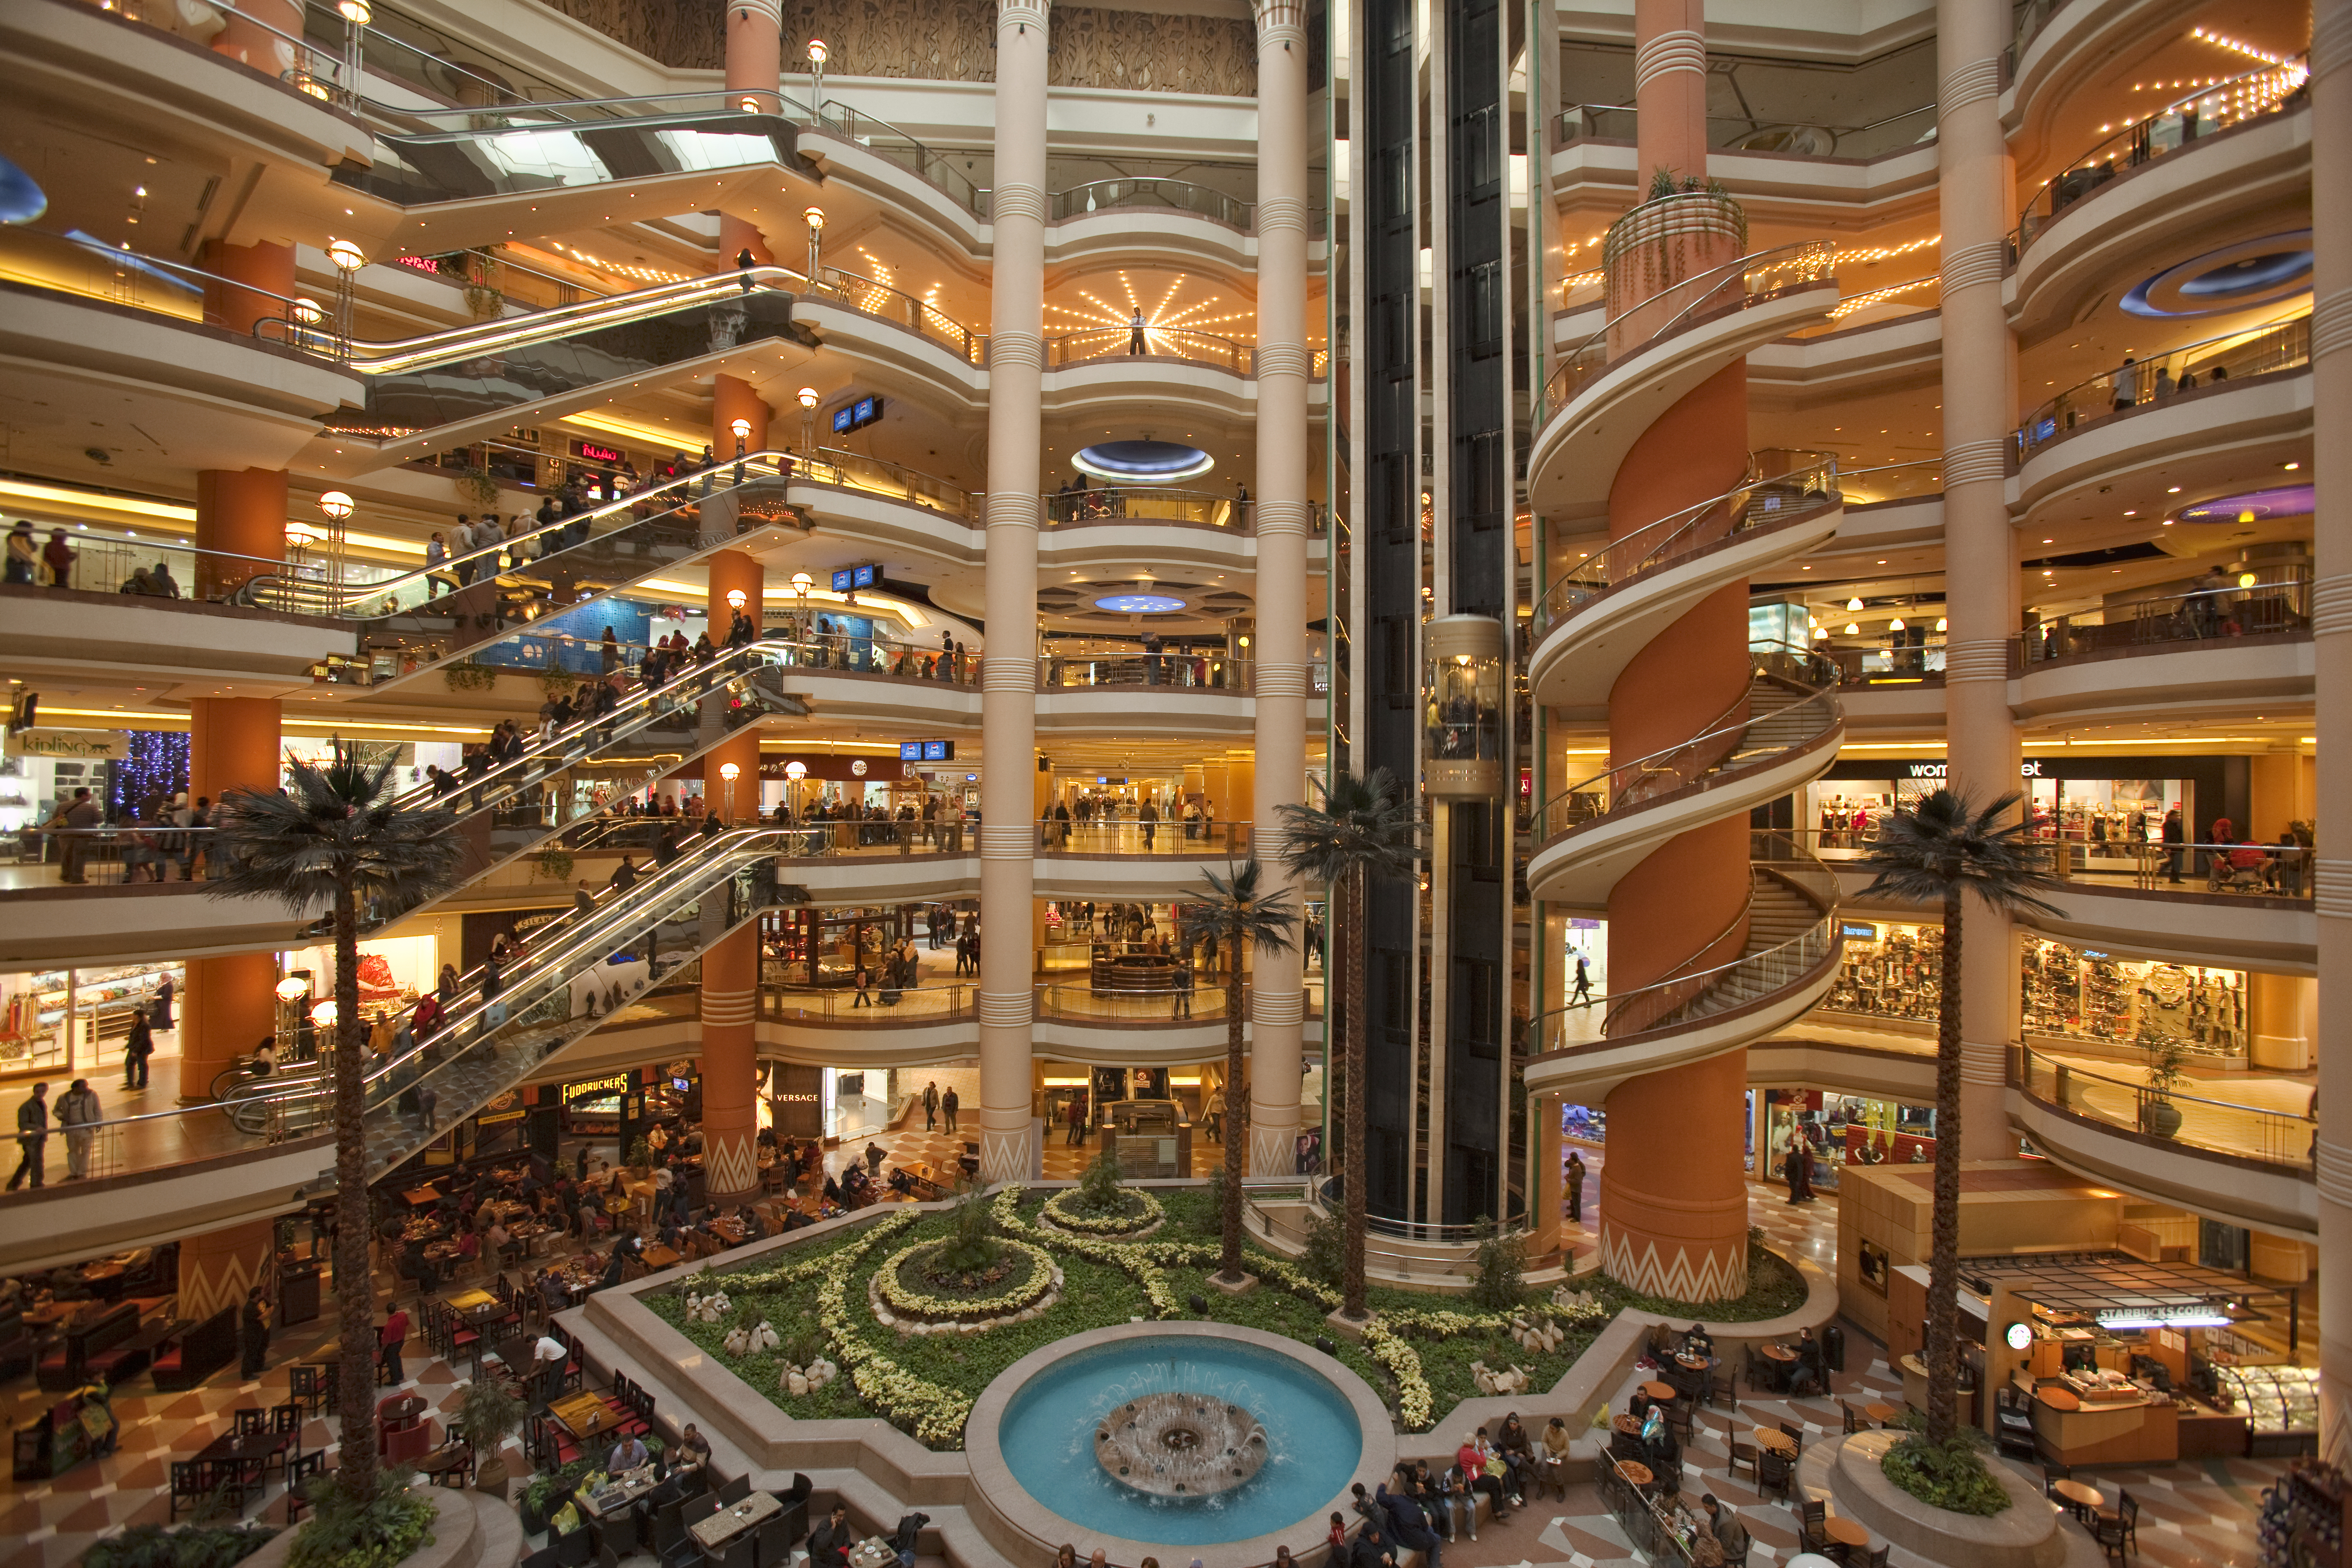
Mall of Egypt, commonly known as Egypt Mall, is situated in 6th of October City, Cairo, along El Wahat Road, providing access via major highways like the Ring Road. Developed by Majid Al Futtaim and operational since 2014, it offers 160,000 square meters of gross leasable area over four levels within a 440,000 square meter mixed-use development that includes shopping, entertainment, offices, and residential components.
The tenant mix comprises approximately 350-400 stores, with 40% dedicated to fashion outlets featuring brands such as Zara, H&M, and luxury options like Gucci; 25% to food and beverage venues with diverse cuisines; 20% to entertainment including the unique Ski Egypt indoor ski slope, VOX Cinemas, and an adventure park; and key anchors like the Carrefour hypermarket. Occupancy stands at 92%, surpassing the Cairo suburban average of 82% per JLL reports, with 5,000 square meters of available space and a robust pipeline for new tenants.
Monthly footfall exceeds 1.5 million visitors, supported by 5,000 parking spaces, average dwell time of 120 minutes, and a 30% conversion rate. The primary catchment area covers 2.5 million residents within a 10 km radius, characterized by middle to upper-middle income households with median annual income of 4,500 USD, 55% families with children, and growing expatriate presence.
Rent levels range from 25-40 USD per square meter annually, with leasing advantages including flexible 3-7 year terms, turnover rent clauses at 8-12% of sales, 5-7% annual escalations, and incentives like fit-out contributions up to 20% for anchors.
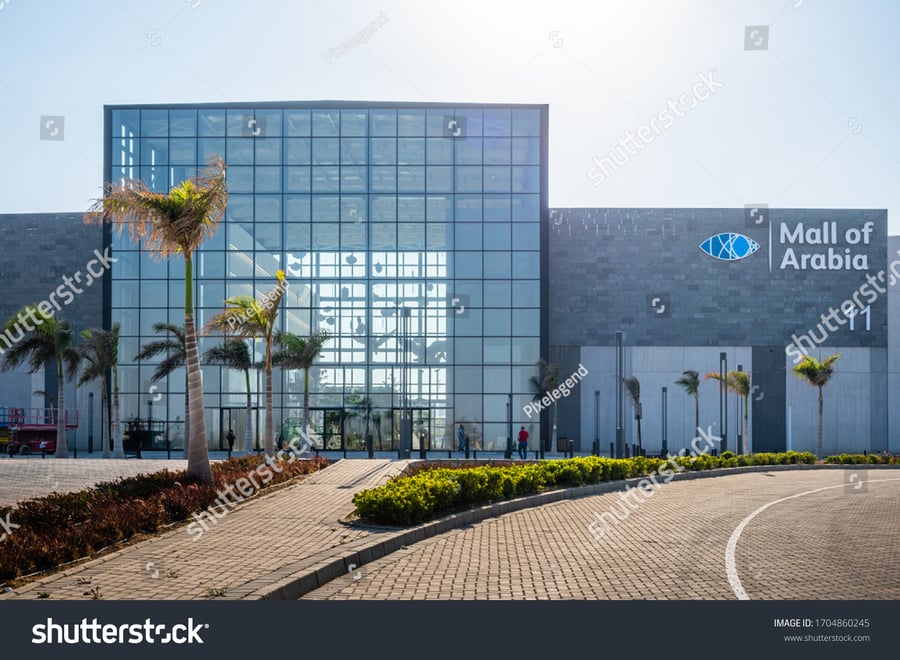
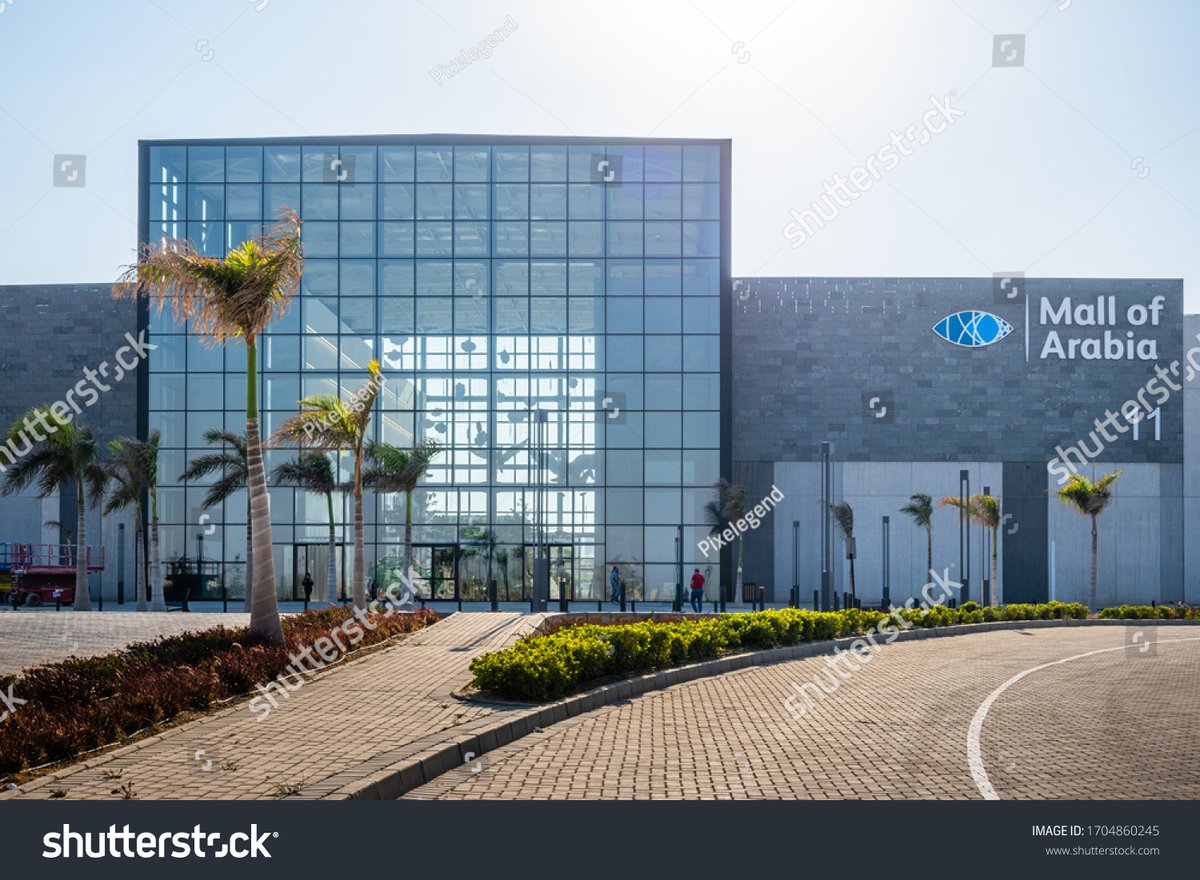
Market position is strong as a premium destination with sales per square meter at 2,500 USD, 10-15% above peers, driven by unique entertainment anchors that enhance dwell times and promotional events with 40% loyalty program penetration. However, challenges include peak-hour traffic congestion reducing effective footfall by up to 10%, regional economic volatility from inflation and currency devaluation potentially increasing costs by 15-20%, and intensifying competition from nearby malls like Mall of Arabia.
Operational quality is high with 95% facility uptime and digital traffic analytics, though aging infrastructure may require capex for upgrades estimated at 10% of rent value.
Overall, it presents balanced leasing opportunities for retailers targeting family-oriented and lifestyle segments amid Egypt's projected 4% GDP growth in 2025.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 11:00 PM |
| Saturday | 10:00 AM — 11:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
"Demographic Profile"
The catchment area for Egypt Mall encompasses 2.5 million residents in a 10 km radius around 6th of October City and Sheikh Zayed, with a secondary 30 km radius extending to greater Cairo. Demographics feature middle to upper-middle income families, with median household income at 4,500 USD annually and household sizes averaging 4.2 persons. Median age is 25 years, tertiary education rate is 25%, and unemployment is 8.5%. Visitor breakdown includes 55% families with children under 18, 25% young professionals aged 18-35, and 20% older adults, supporting strong performance in family entertainment and apparel categories. Retail spending per capita reaches 1,200 USD, with 250 USD on apparel and 600 USD on groceries. High literacy over 90% and 5-10% expatriate community favor international brands, though economic disparities may limit non-essential spending. Internet penetration at 60% heightens e-commerce competition, potentially drawing 15% of sales away from physical stores. Population growth of 2.5% annually bolsters long-term potential, but seasonal fluctuations tied to school holidays can boost footfall by 20-30%.
"Competition and Market Risks"
Competition in 6th of October City is medium to high, with rivals like Mall of Arabia (100,000 sqm GLA, 300 stores, value-oriented) and Royal Mall (88% occupancy) fragmenting market shares, particularly in apparel where rivalry intensity is 15-20%. This saturation necessitates differentiated tenant positioning to sustain sales velocity. Broader risks include Egypt's economic challenges, such as 2025 inflation and EGP devaluation raising operational expenses by 15-20%, alongside fuel price hikes increasing logistics costs. E-commerce growth at 15% annually erodes physical retail sales, especially in non-grocery categories. Infrastructure strains and no specified expansion plans could limit future scalability. Positively, the mall's unique anchors like Ski Egypt provide a competitive edge, achieving superior dwell times and 5% projected footfall growth, though accessibility issues during rush hours may reduce effective traffic by 10%. Overall, retailers face balanced risks with opportunities in underserved leisure segments.
"Lease Terms and Operational Quality"
Leasing at Egypt Mall involves 3-7 year terms with base rents of 25-40 USD per square meter annually, competitive against central Cairo premiums, including 8-12% turnover rent over breakpoints and 5-7% escalations. Incentives for anchors include up to 20% fit-out contributions and co-op marketing budgets, offering negotiation leverage amid 7.2% vacancy. Operational quality under Majid Al Futtaim management is strong, with 95% facility uptime, CCTV security, low crime rates, and digital signage for promotions. Loyalty programs reach 40% penetration, enhancing customer retention. Drawbacks include potential capex needs for aging HVAC and upgrades post-10 years, estimated at 10% of rent value, and high e-commerce adoption impacting click-and-collect efficiency. Accessibility via public transport is good, but congestion poses challenges. These factors support practical leasing for retailers seeking stable, high-traffic environments with flexible terms.
Building Details
Detailed Market Analytics
City Snapshot
6th Of October City
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in 6th Of October City
Discover more shopping centers in 6th Of October City.

Popular in Egypt
Top retail destinations across Egypt.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
6th Of October City
Comprehensive market intelligence for retail expansion in this city