




Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
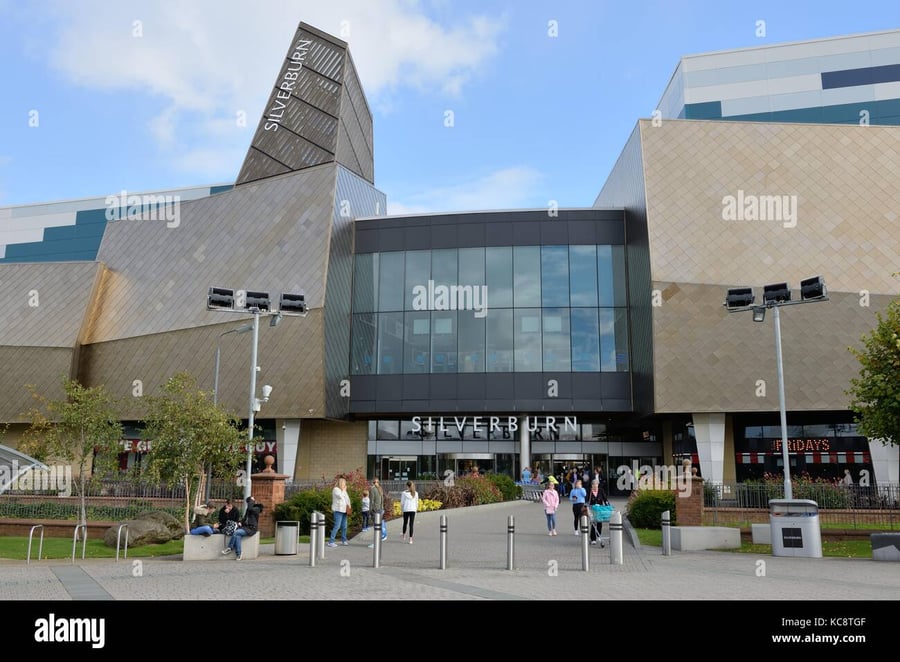
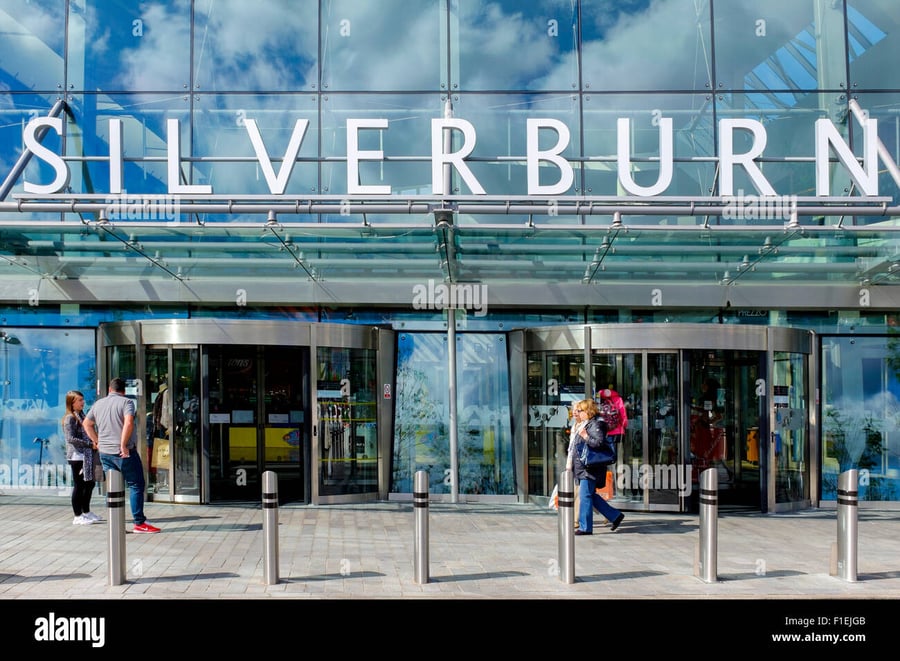
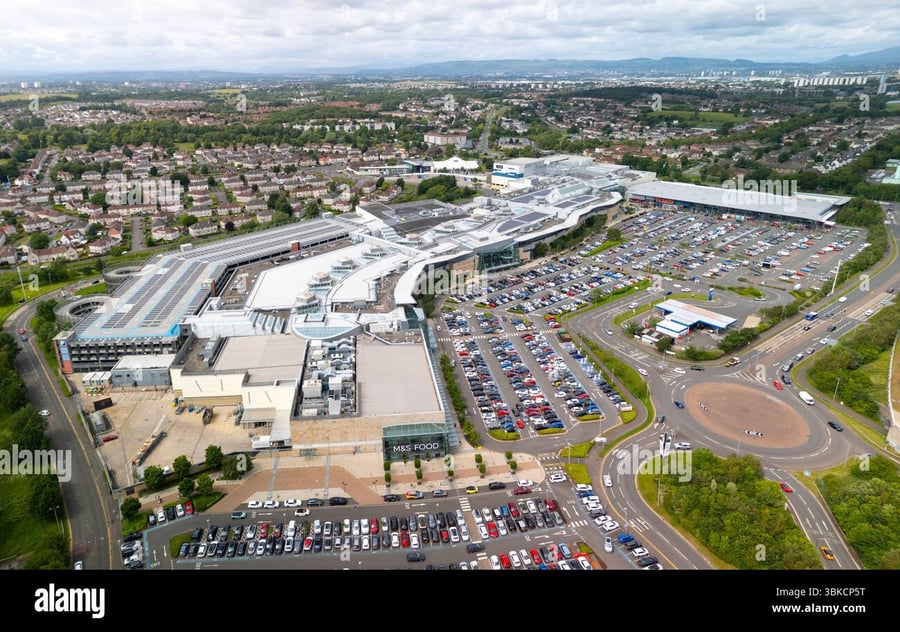
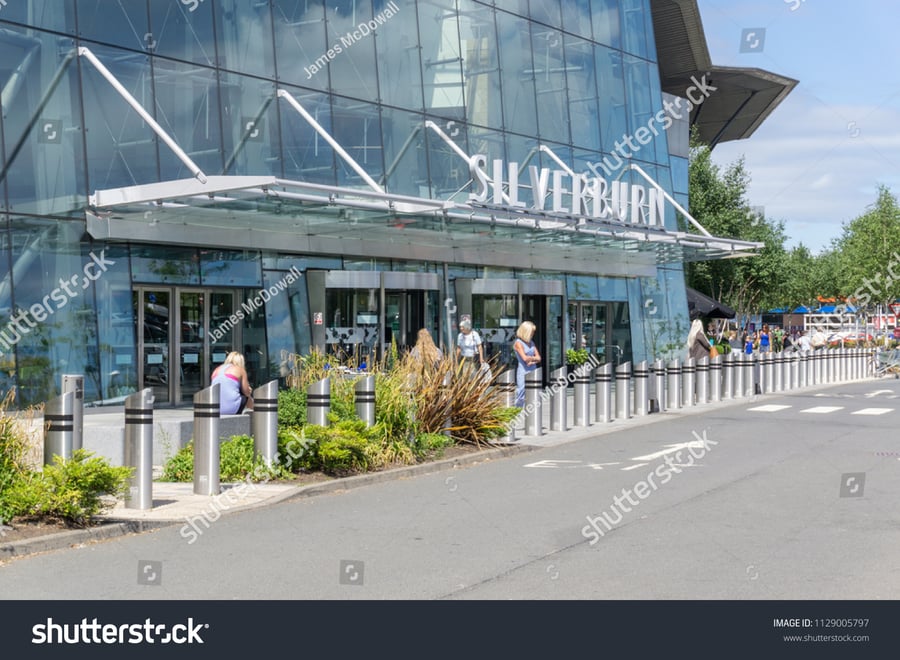
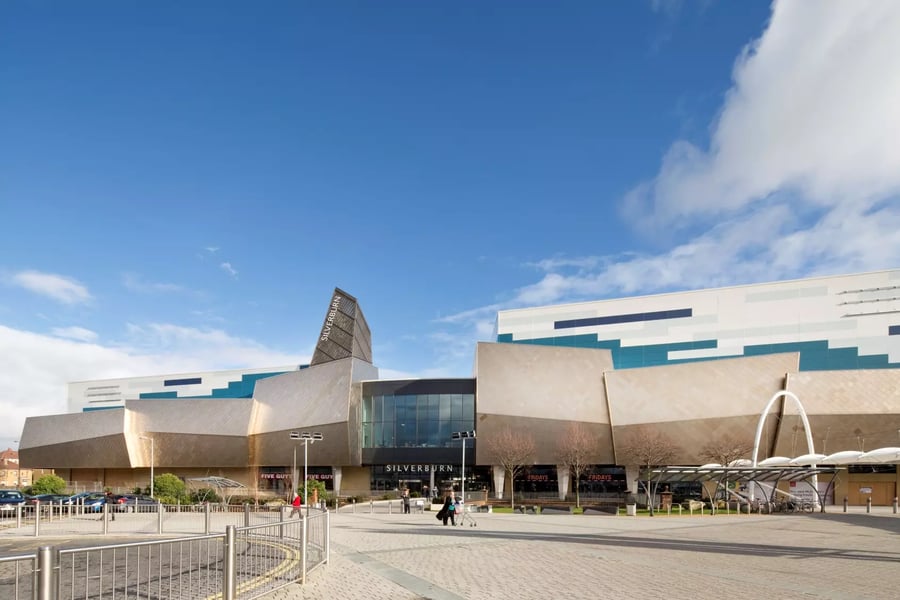
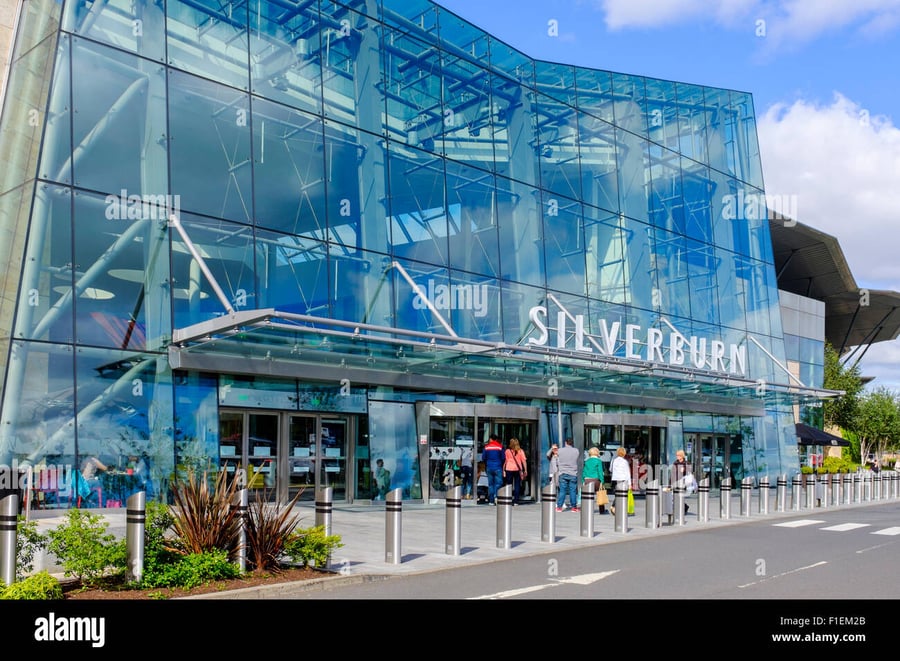
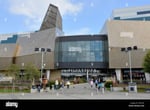
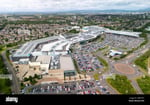
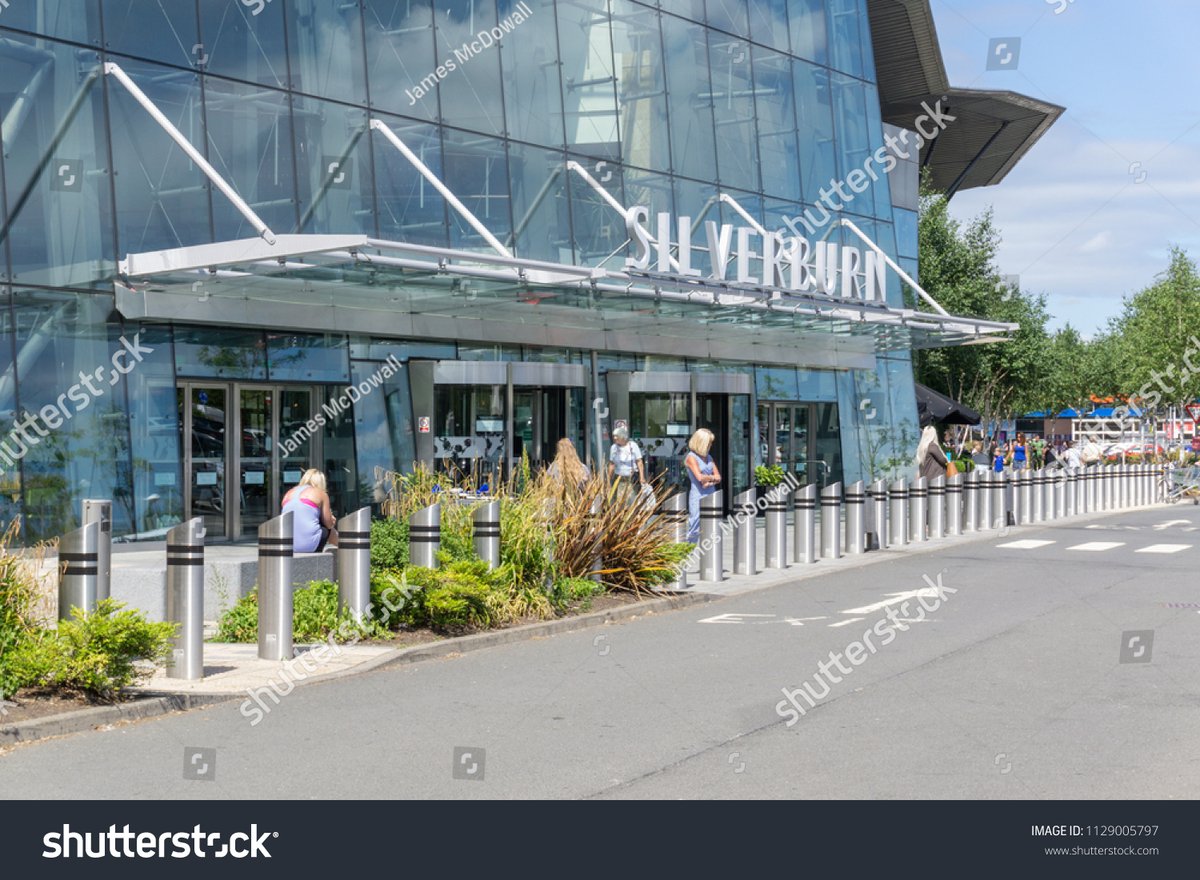
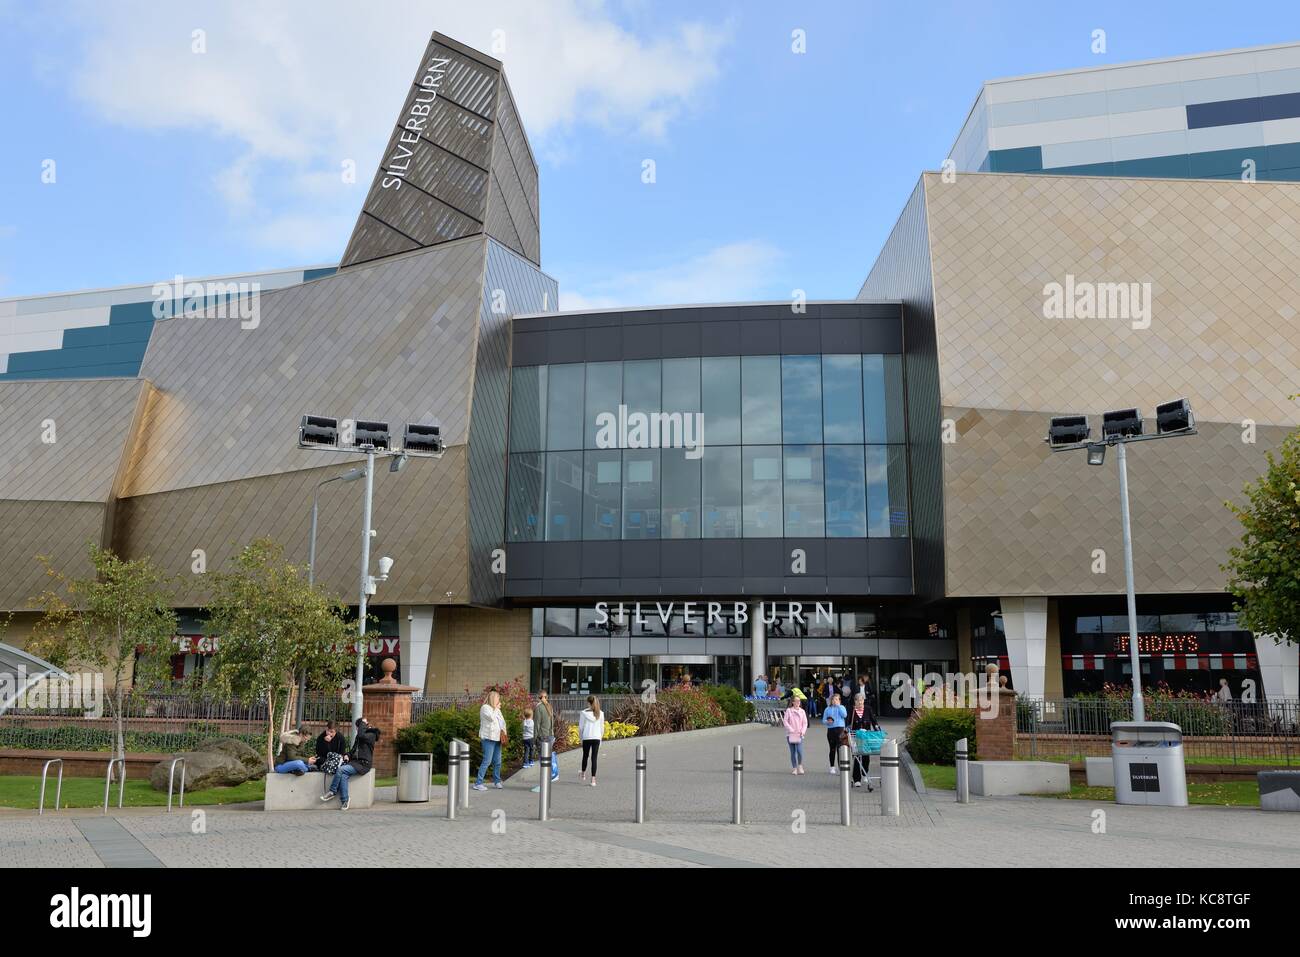
Silverburn Shopping Centre, located in Pollok, Glasgow, Scotland, is an out-of-town retail and leisure destination opened in 2007, with expansions completed in 2015 adding a Cineworld cinema and nine restaurants. The property covers 1.5 million square feet of gross leasable area, accommodating 109 units: 95 retail stores, 14 dining outlets, and leisure facilities. Anchor tenants comprise Tesco Extra (Scotlands largest), Next, and Marks & Spencer, alongside a diverse tenant mix featuring high-street names like TK Maxx and premium brands such as Jo Malone London.
Recent developments include 24 new stores and 10 kiosks added in the past 18 months, with further openings planned for 2025, including H Beauty and The Real Greek. Occupancy reached 97% in 2025, exceeding the UK average of 83.1%, driven by proactive leasing and tenant upgrades. Footfall hit a record 15.2 million visitors in 2024, up 2.4% year-over-year, with an average dwell time of 108 minutes and conversion rates of 25-30%; sales density averages £5,000-6,000 per square meter.
Rents range from £18-20 per square foot. The centre serves a catchment of 1.9 million affluent residents within 30 minutes, characterized by middle-income households (£38,000 median) and 1.2% annual population growth.
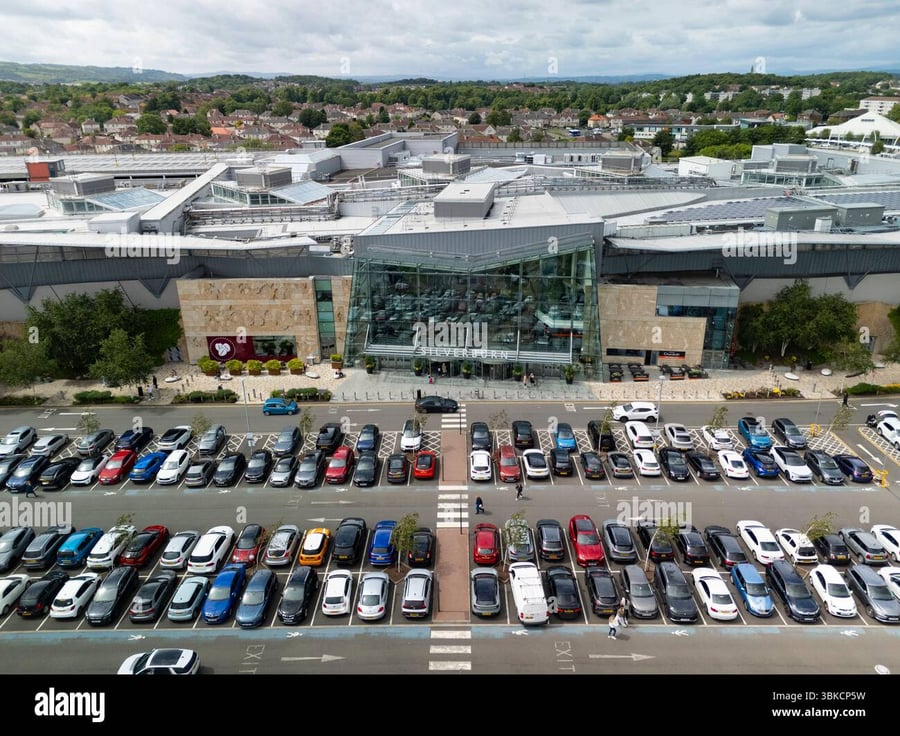
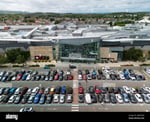
Accessibility benefits from proximity to the M77 motorway, frequent bus links, and 4,000 parking spaces, positioning it 15 minutes from Glasgow city centre. As a top 20 UK shopping centre, it was named Retail Destination of the Year 2025 and Glasgows best performing large business. Leasing opportunities offer high visibility, marketing support, and integrated leisure to boost performance, though economic sensitivity and e-commerce pose risks.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 09:00 PM |
| Saturday | 09:00 AM — 07:00 PM |
| Sunday | 10:00 AM — 07:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment
The catchment area encompasses 1.9 million people within a 30-minute drive, primarily from affluent south Glasgow suburbs like Pollok and surrounding areas in East Renfrewshire and Paisley. Median household income stands at £38,000, supporting higher discretionary spending on retail and leisure, with a demographic profile skewed toward families and middle-income professionals aged 25-54. Annual population growth of 1.2% enhances long-term potential, though 5.5% unemployment rate introduces vulnerability to economic downturns. Per capita retail spend averages £3,500 annually, bolstering sales potential for lifestyle and fashion retailers. This profile favors tenants targeting value and premium segments but requires strategies to address affordability concerns amid inflation.
Occupancy and Tenant Mix
Occupancy at 97% in 2025 reflects strong demand, with only 5% vacancy amid a pipeline of over 20 new leases. The tenant mix emphasizes balance: 60% fashion and accessories (e.g., Next, Stradivarius), 20% food and beverage (14 outlets including The Real Greek), 15% health and beauty (e.g., Jo Malone, H Beauty), and 5% services, integrated with leisure like Cineworld to extend visits. Recent rotations have upgraded units, reducing weak categories. Average lease terms are 5-10 years with turnover rents, and rents at £18-20 psf provide competitive entry for mid-tier brands. Strengths include diverse appeal driving 30% conversion, but fashion saturation risks over-reliance on cyclical categories.
Competition and Accessibility Risks
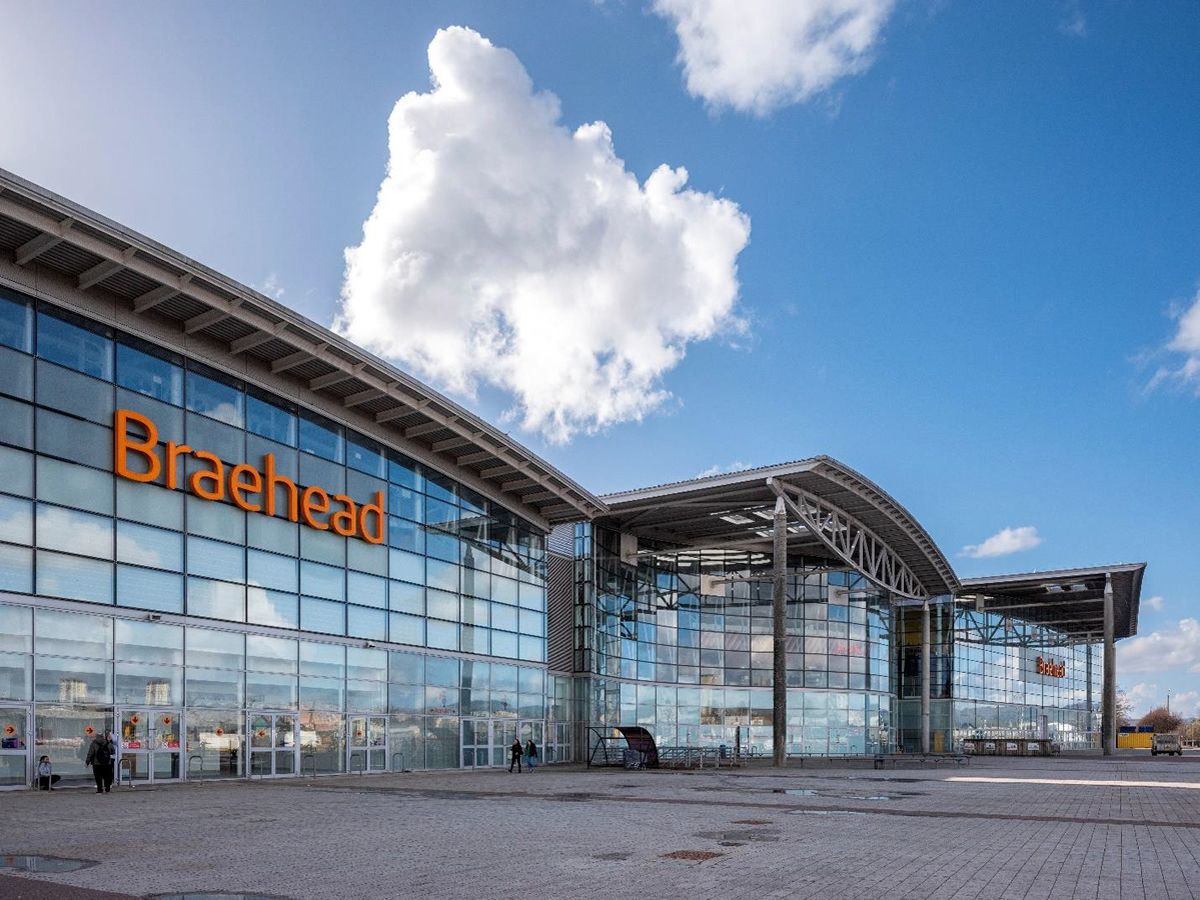
Primary competition stems from nearby Braehead Centre (higher leisure focus) and Glasgow city centre, potentially diverting 20-30% of regional footfall during peak seasons. Out-of-town location enhances car access via M77 but limits public transport reliance, with bus services adequate yet secondary to 4,000-space parking; this car dependency poses sustainability risks and excludes non-drivers, comprising 15% of catchment. E-commerce penetration at 95% erodes physical sales by 10-15% annually, while medium competitor density in south Glasgow contributes to market saturation in apparel. Infrastructure from 2007 remains modern with natural ventilation, but maintenance costs could rise. Overall, risks include economic fluctuations impacting middle-income spending and seasonal traffic variations, necessitating robust digital integration for tenants.
Building Details
Detailed Market Analytics
City Snapshot
Glasgow, SCT
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Glasgow
Discover more shopping centers in Glasgow.

Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Glasgow, SCT
Comprehensive market intelligence for retail expansion in this city