

Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
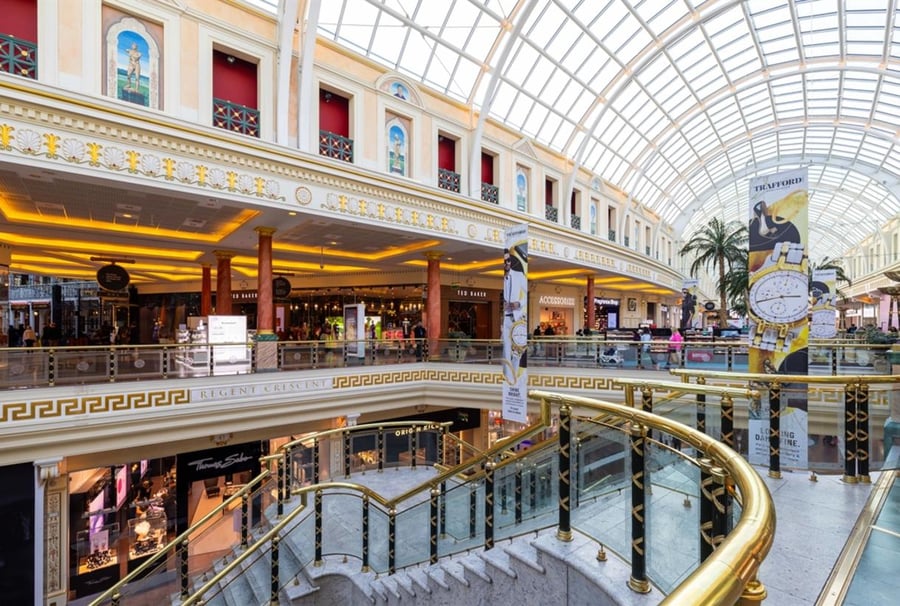
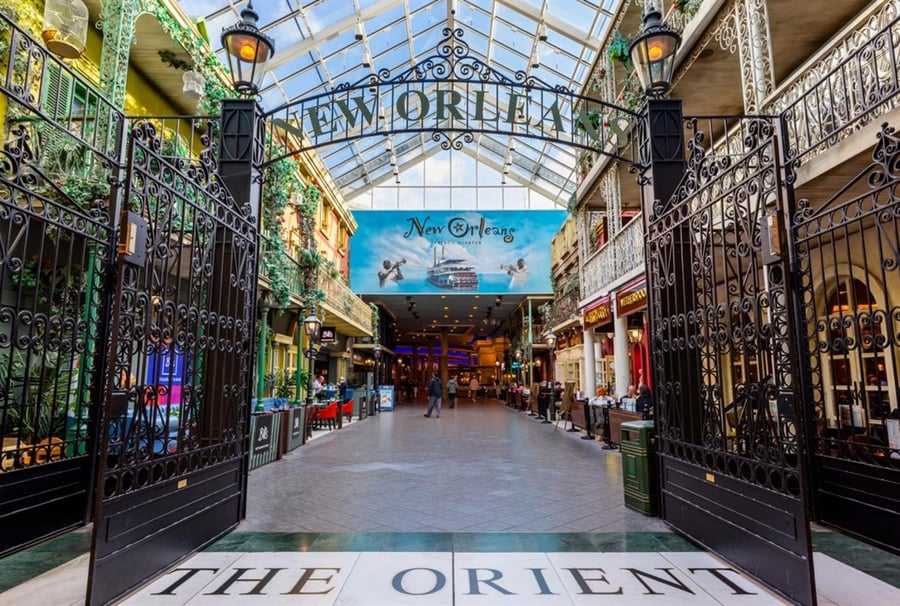
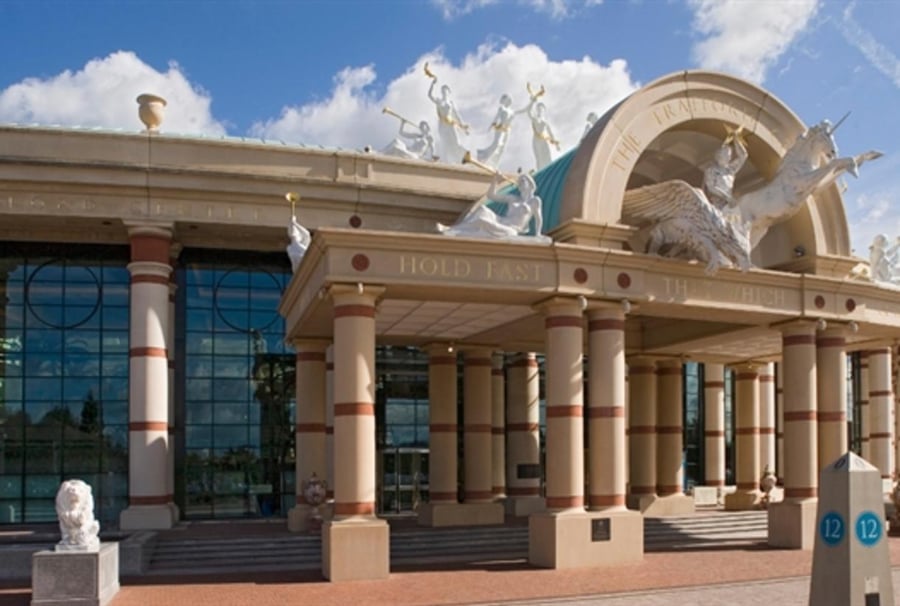
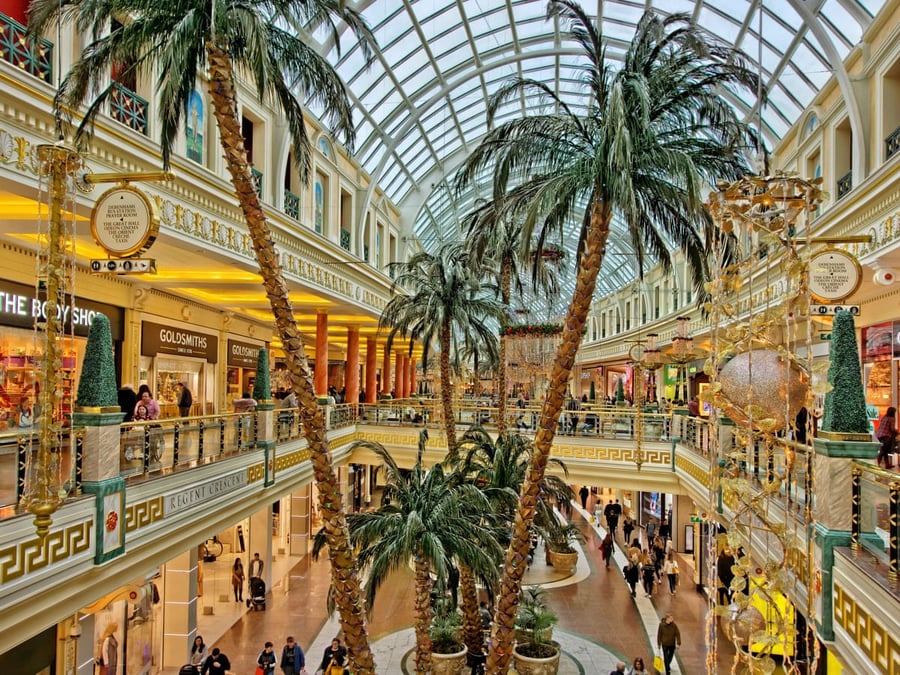
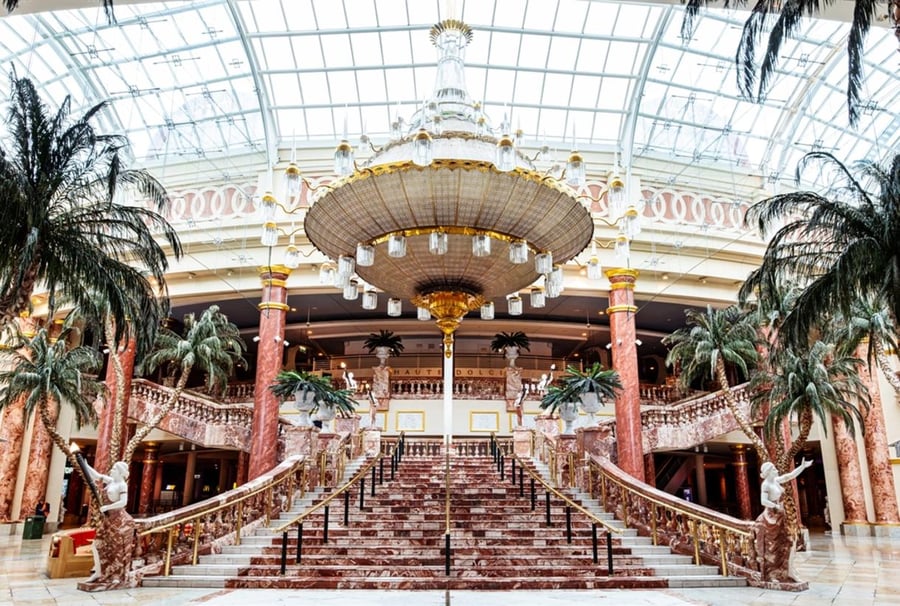
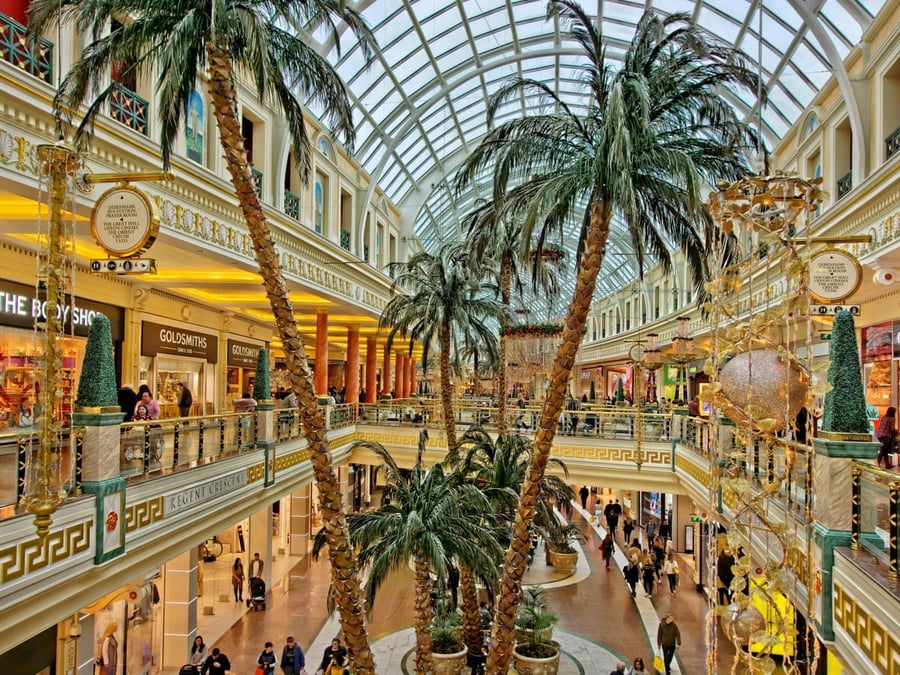
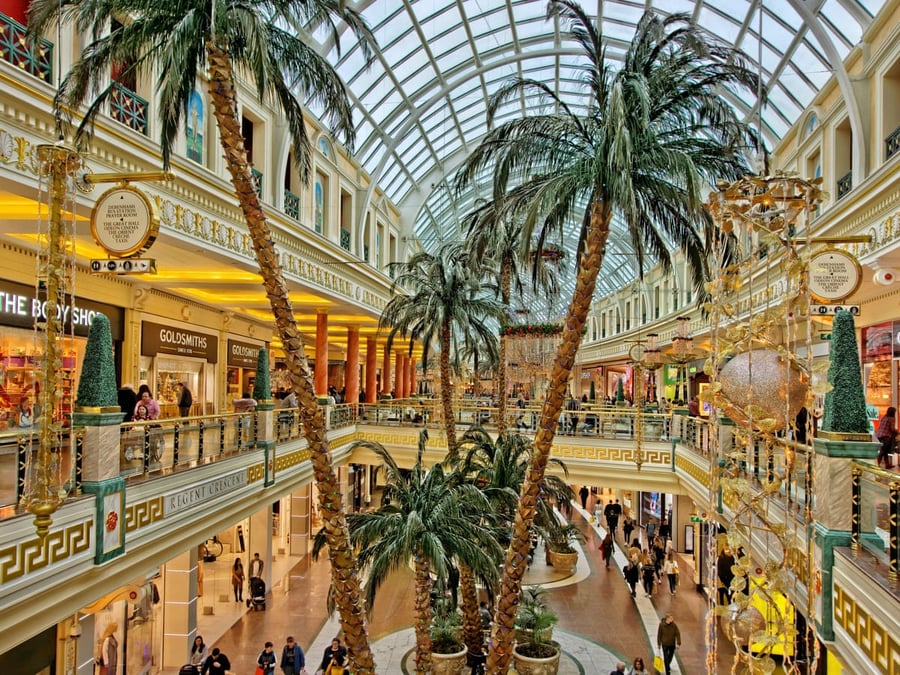
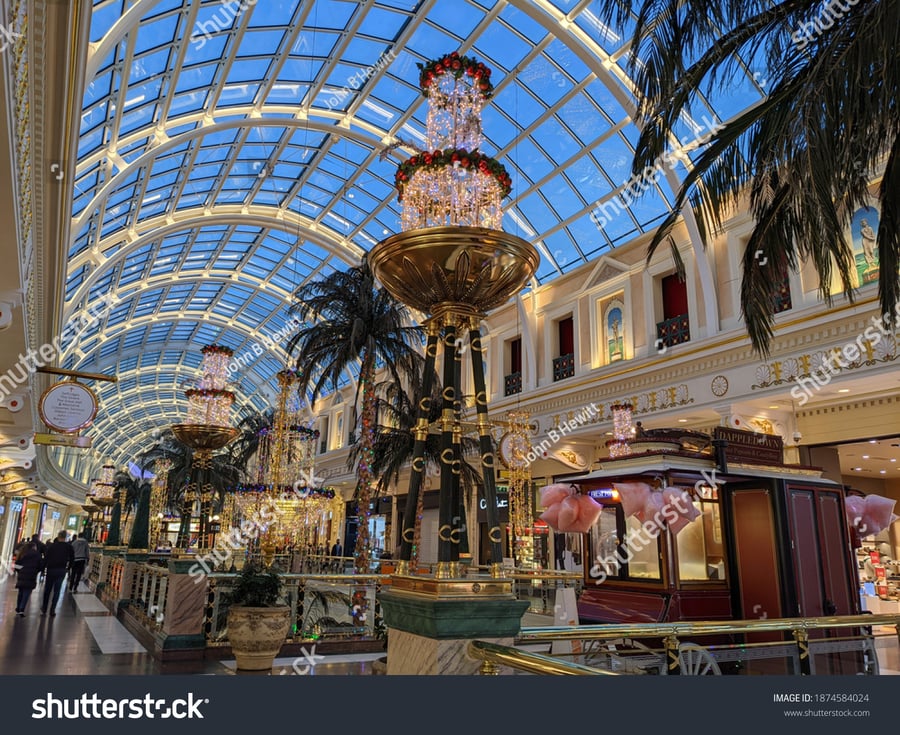
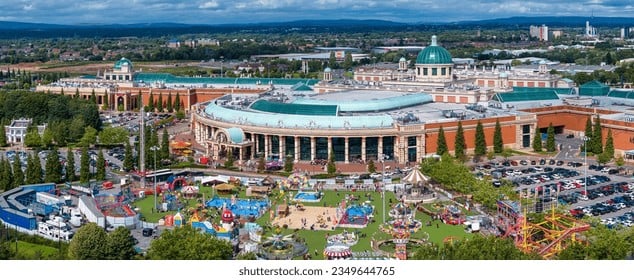
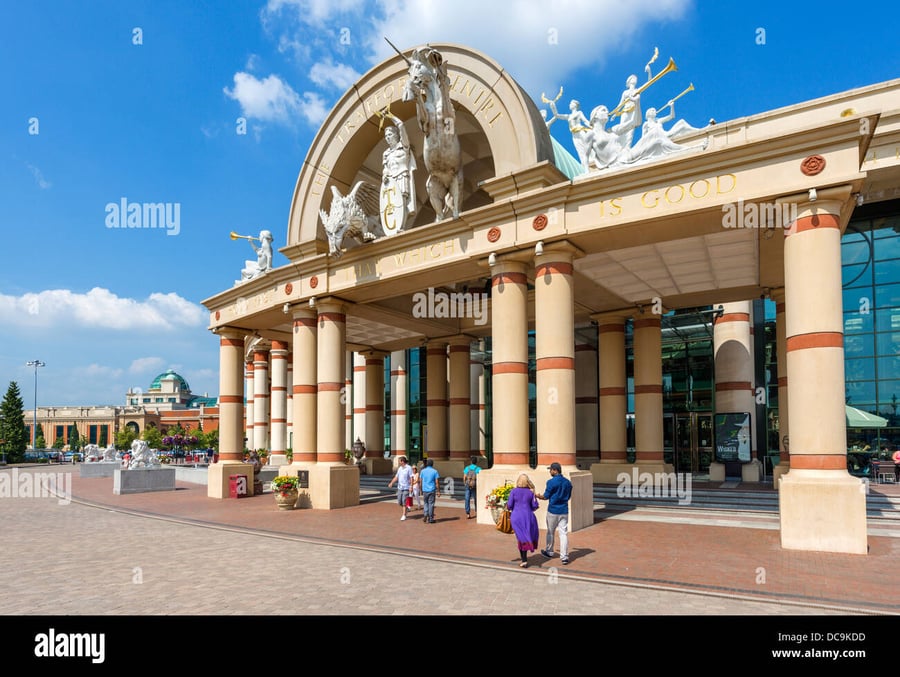
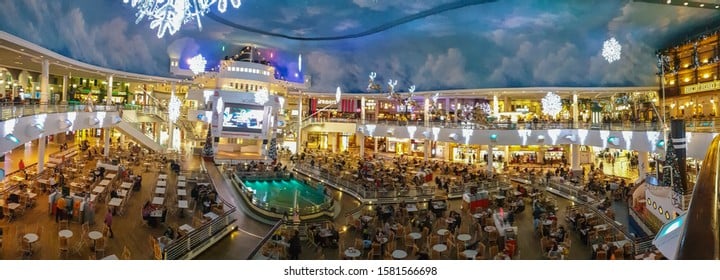
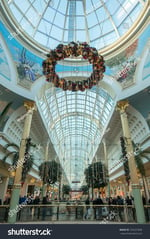
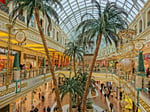
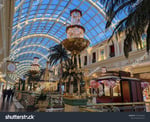
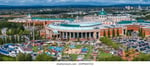
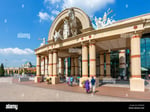
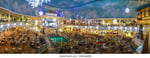
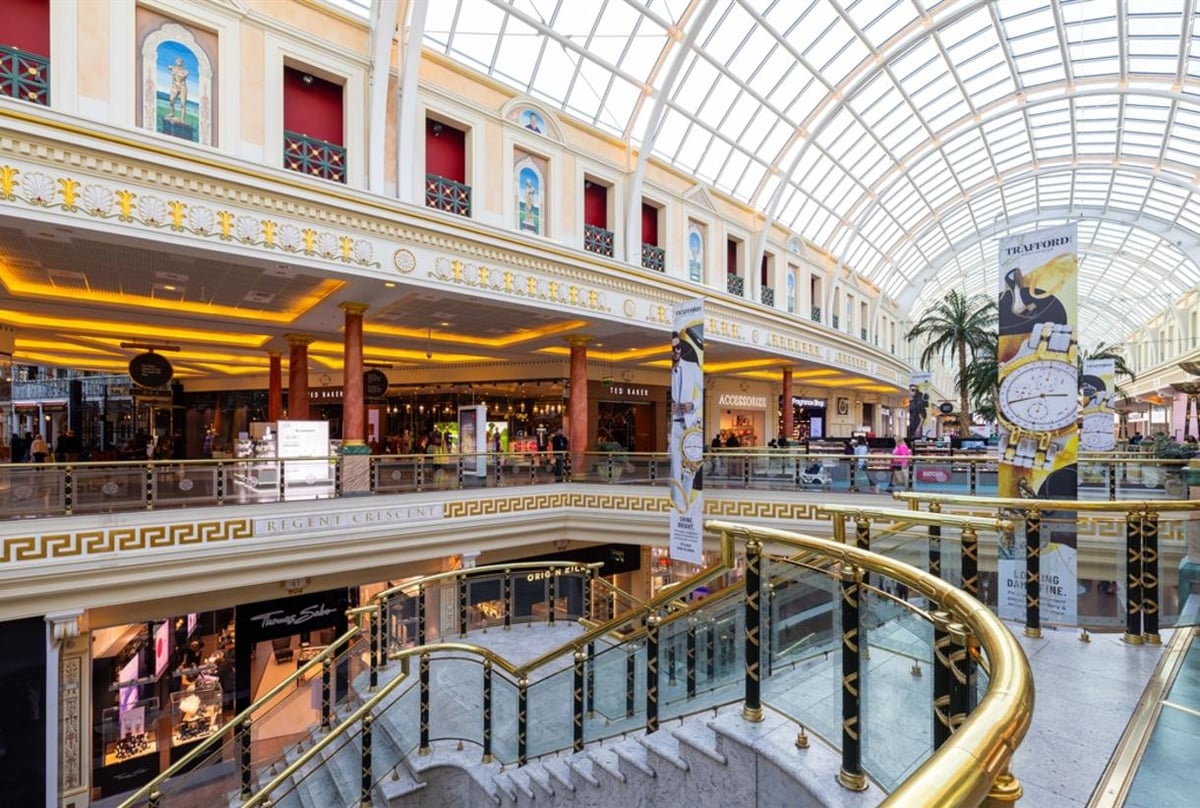
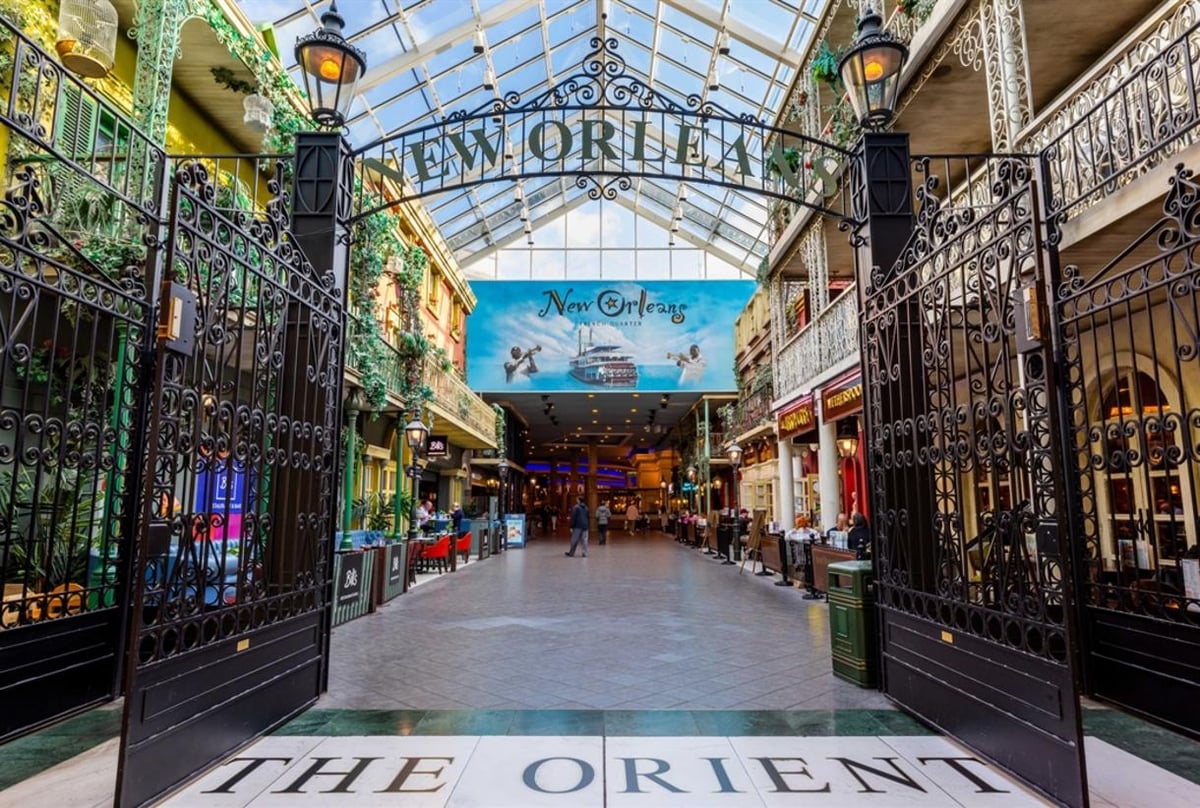
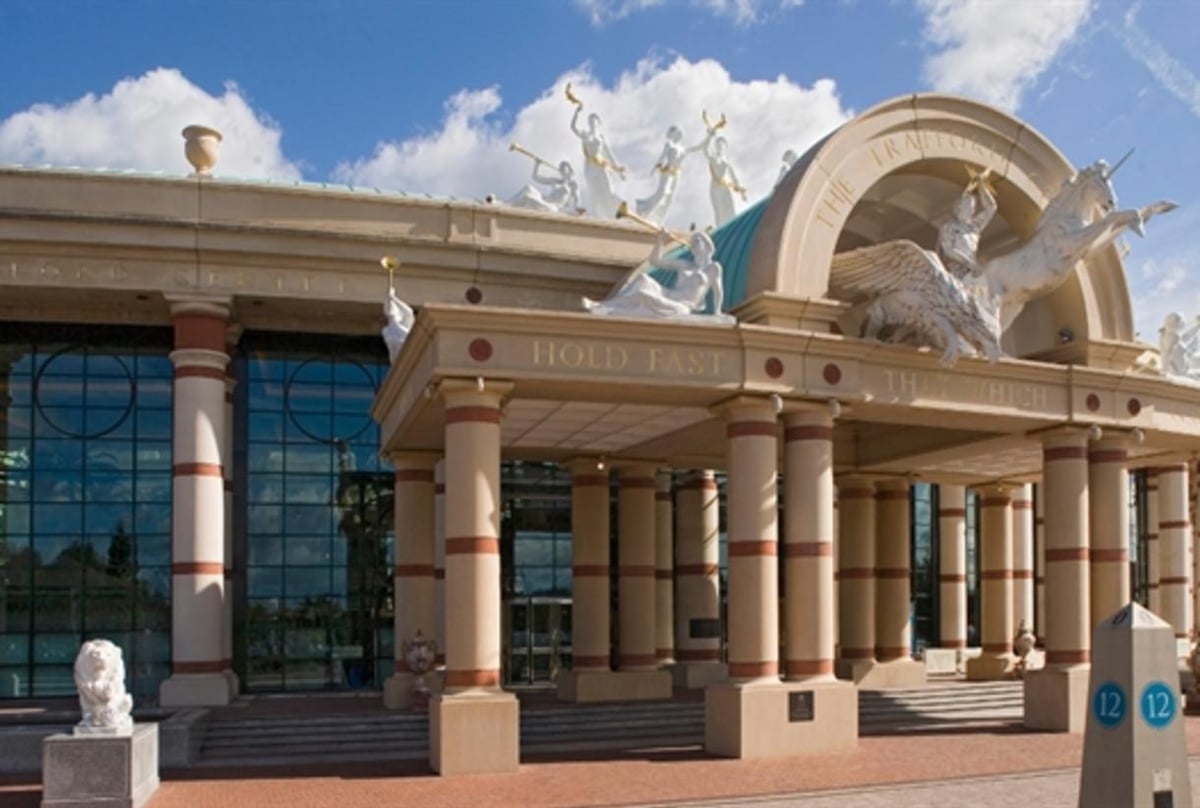
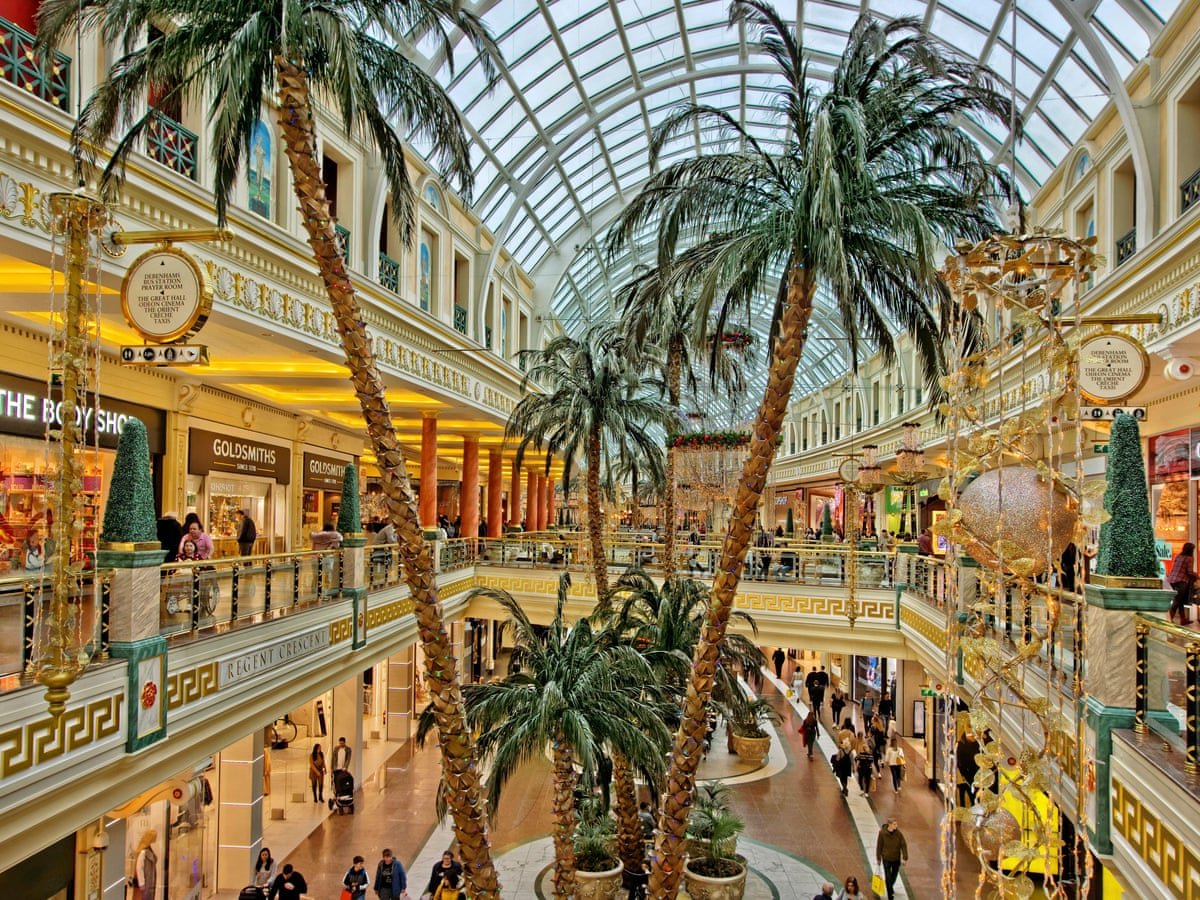
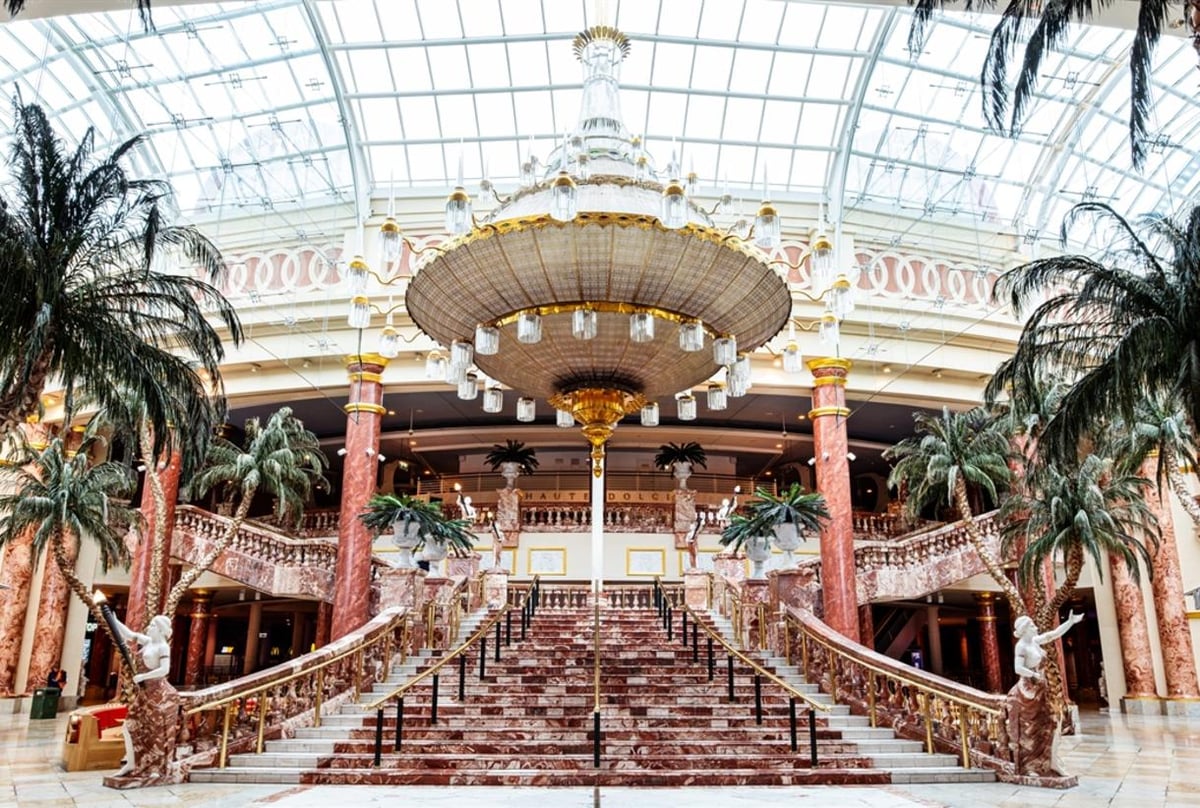
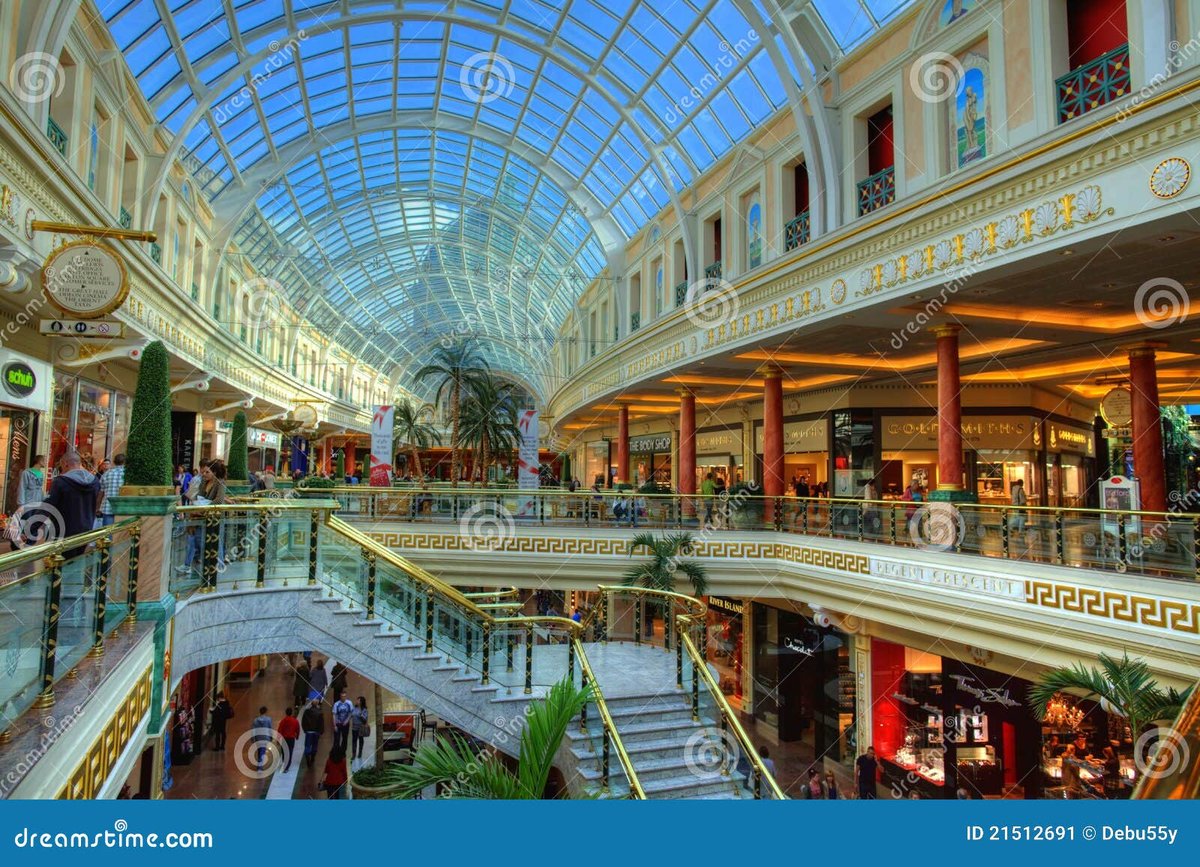
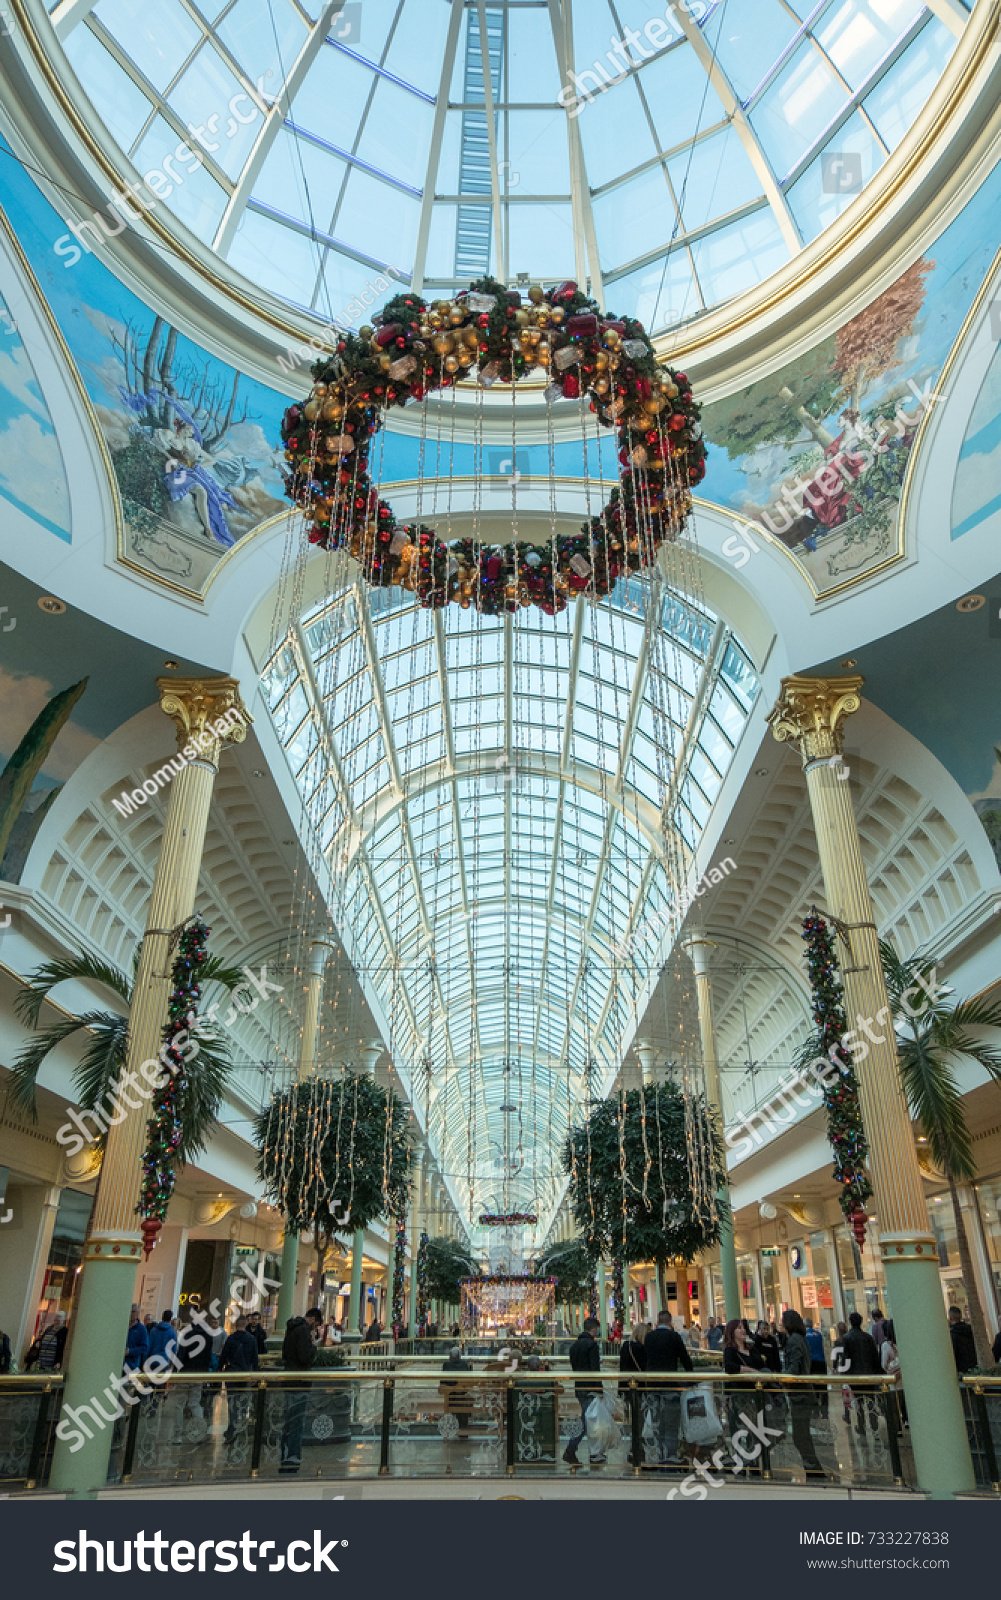
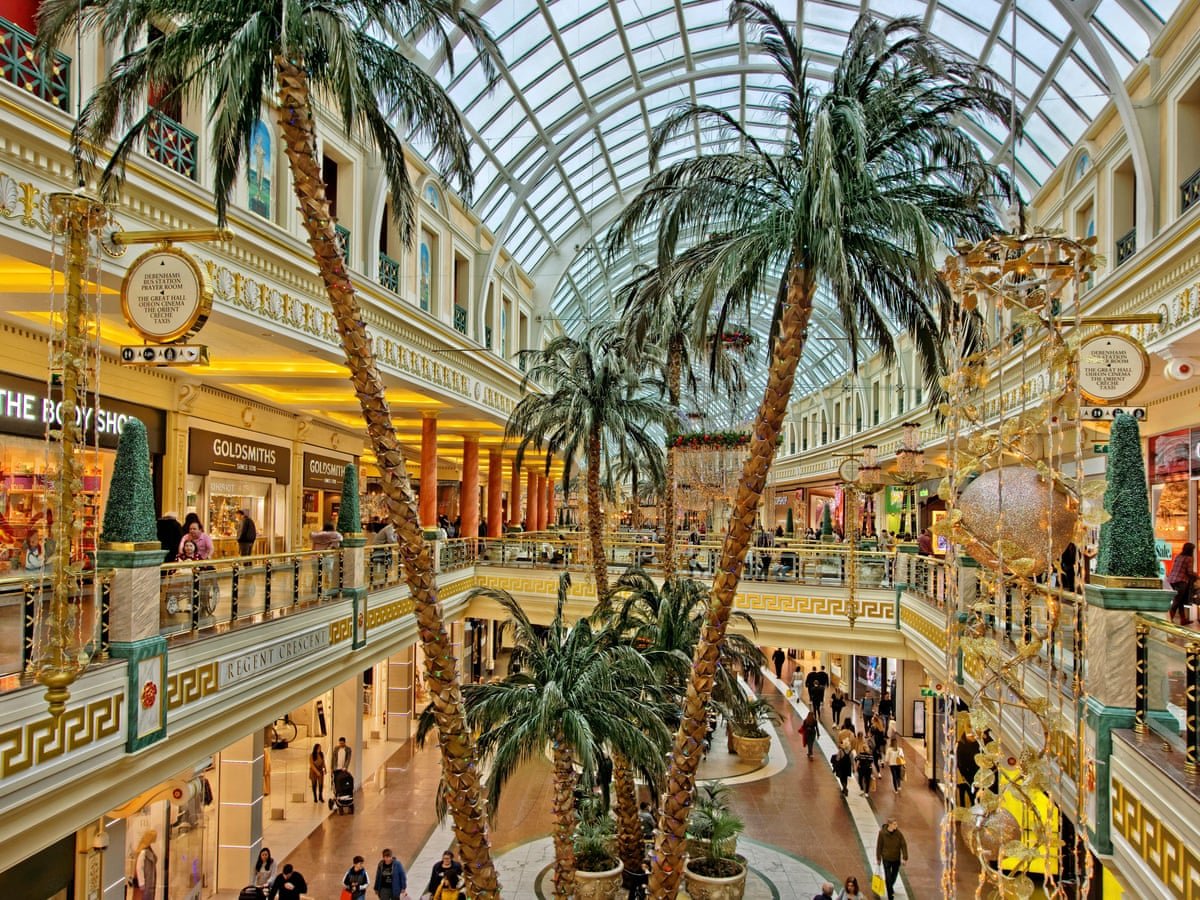
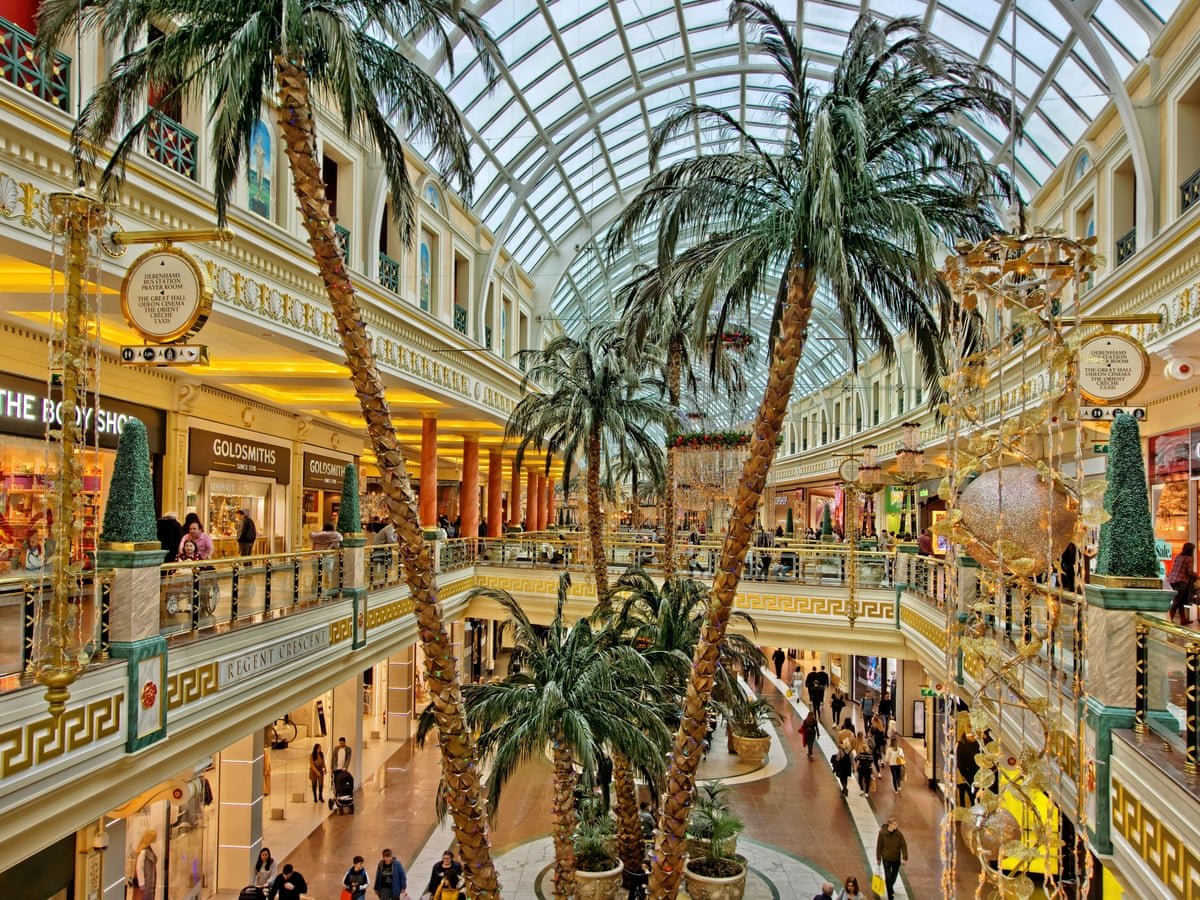
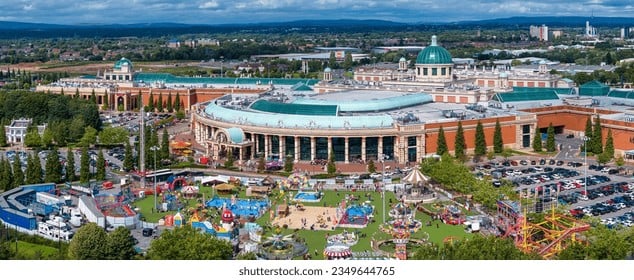
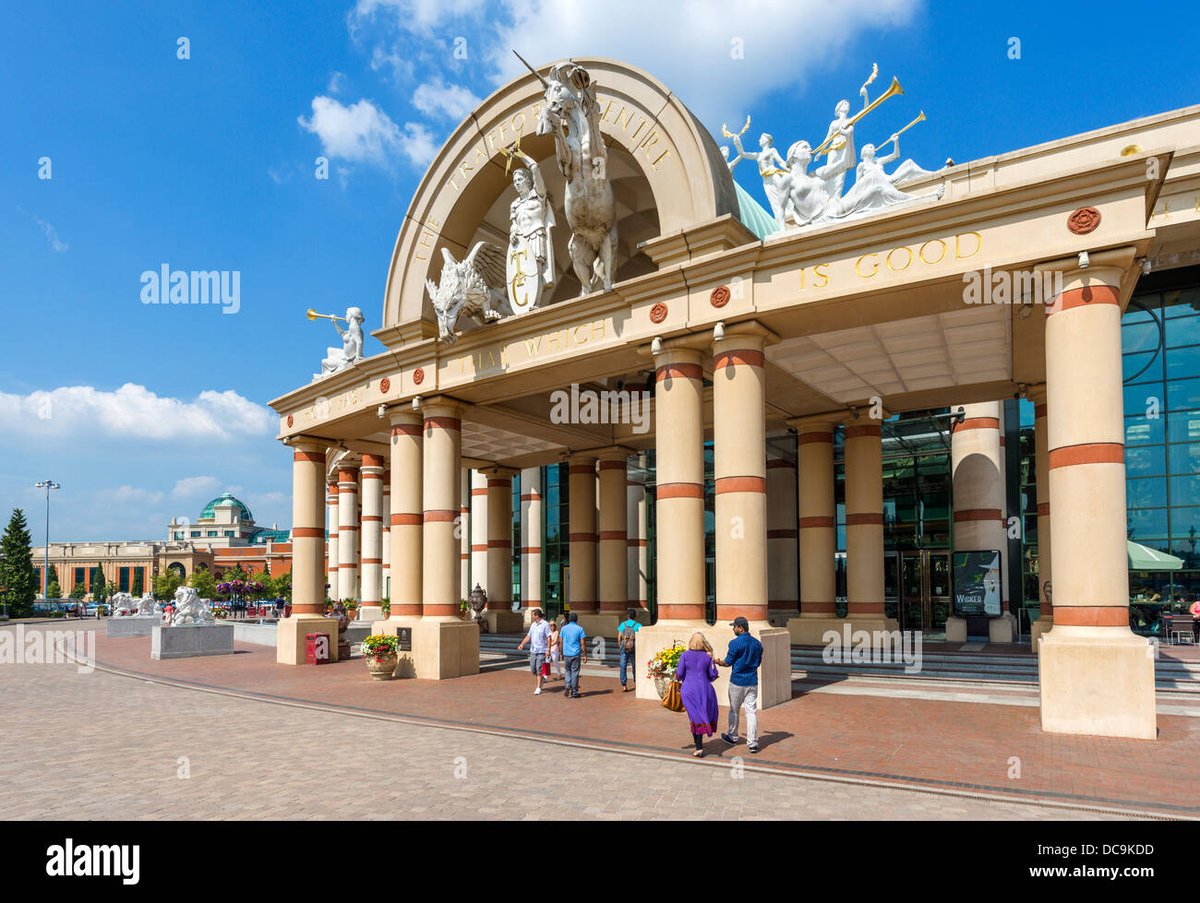
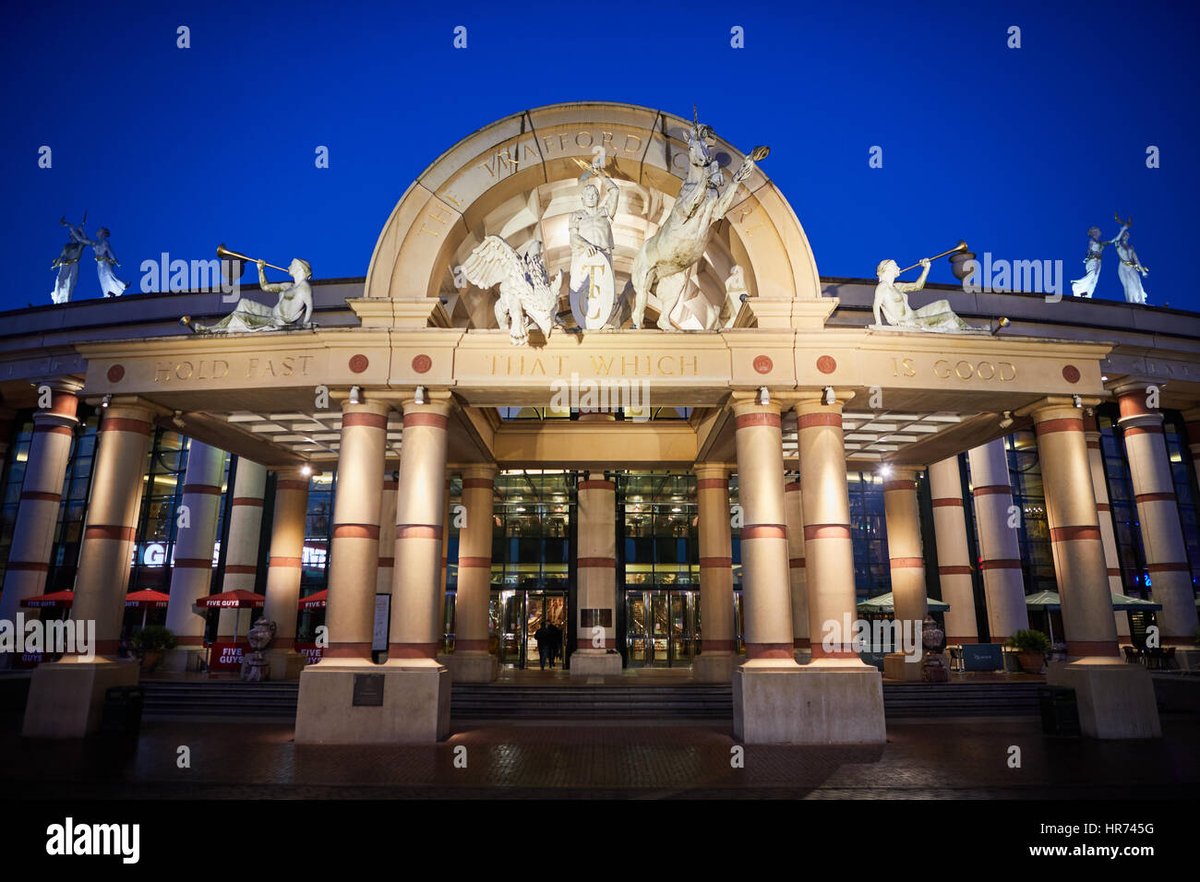
The Trafford Centre in Greater Manchester is a prominent super-regional shopping complex covering 147 acres with about 1.7 million square feet of gross leasable area. It draws approximately 29 million visitors yearly, supported by prime location near the M60 motorway for easy access from the North West region. Occupancy improved to 93% by end-2023, with projections exceeding 95% in 2025 amid active leasing of voids and regears.
Tenant mix features strong anchors including Selfridges (11% of rent), John Lewis (12%), and Marks & Spencer (7%), complemented by fashion brands like Zara and JD Sports, health & beauty outlets, and expanding food & beverage in areas like Eastern Garden. Sales turnover rose 11.3% in 2023, outperforming national averages, driven by categories such as health & beauty (+11%) and F&B (+10%). The catchment encompasses over 5 million residents, with demographics favoring middle to upper-income families from affluent suburbs like Altrincham and Sale, average household income around GBP 45,000.
Leasing benefits include high-visibility mid-mall positions, net effective rents 23% above ERV (around GBP 50-60 per sq ft), and incentives like rent-free periods for key units.
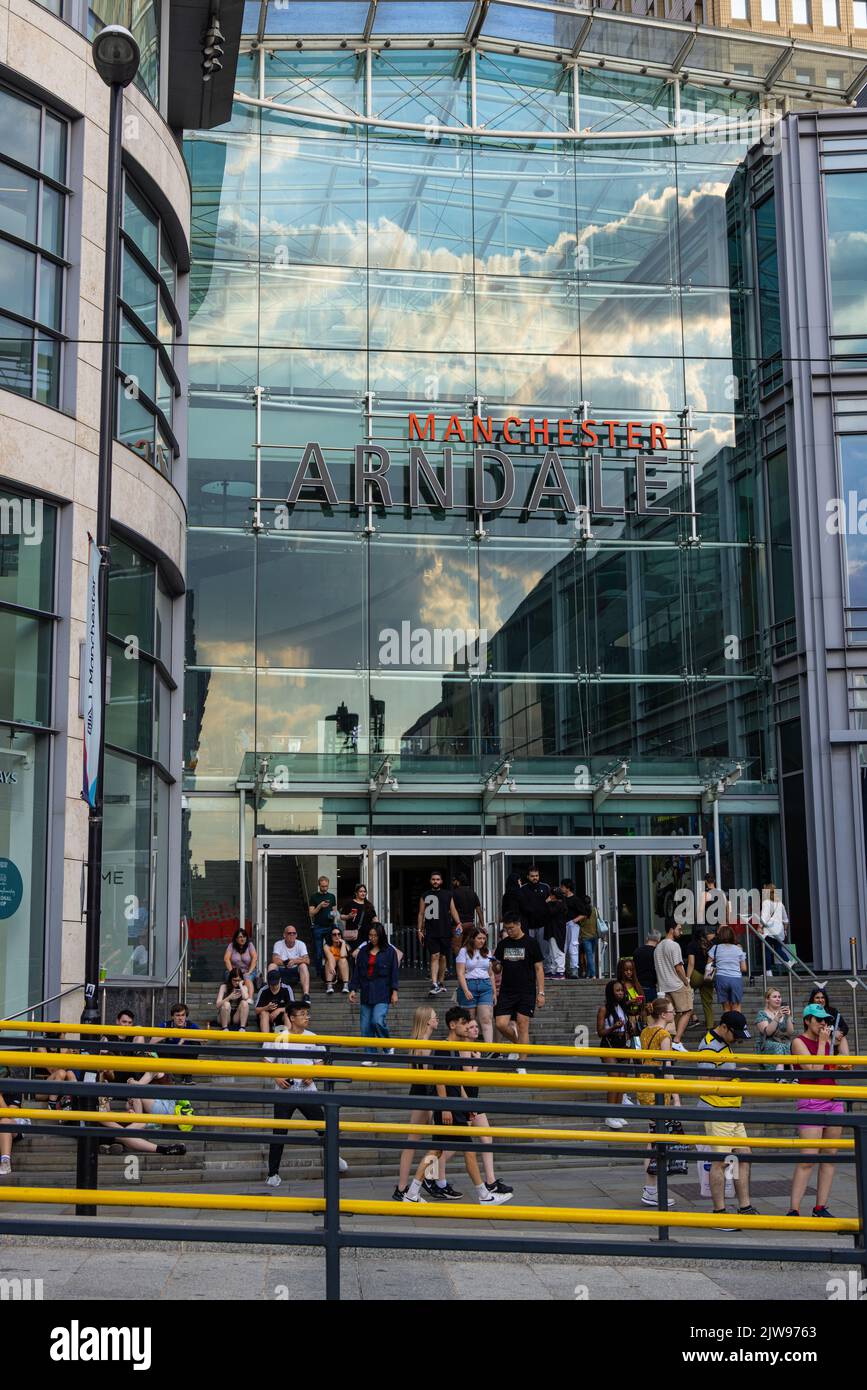
Operational quality is high with modern facilities, EV charging expansions, and ESG initiatives. However, drawbacks involve competition from Manchester Arndale (higher city-center footfall) and online retail, recent tenant failures (e.g., Ted Baker, The Body Shop impacting 1-2% of income), periodic footfall dips due to weather or economy, and reliance on car access potentially limiting public transport users.
Market saturation in fashion categories and aging elements in leisure zones require caution for new entrants.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 09:00 PM |
| Sunday | 12:00 PM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Footfall and Demographics
Annual footfall at the Trafford Centre averages 29 million visitors, with 2023 growth of 3.8% year-over-year, reflecting consolidation of shopping trips to major destinations amid cost-of-living pressures. Q1 2024 saw +11.8% increase versus prior year. The primary catchment covers Greater Manchester and surrounding areas, serving 5.3 million people within 30-45 minutes drive. Demographics skew towards families (35% of visitors) and 25-54 age group, with above-average incomes (GBP 42,000-50,000 household median) from suburbs like Trafford and Stockport. Accessibility is strong via M60/M56 motorways and 13,000 parking spaces, but public transport options (Metrolink nearby) account for only 10-15% of arrivals, posing challenges for non-drivers. This supports high dwell times (average 2-3 hours) and conversion rates for experiential retail, though economic slowdowns could reduce discretionary spending in weaker categories.
Occupancy and Rent Levels
Occupancy reached 93.4% by square footage in 2023 (95% by units), up from 80% post-COVID lows, with 2024 leasing activity completing 51 deals worth GBP 14.6 million in base rent. Voids are concentrated in smaller units (under 200 sqm), now mostly under offer. Rent levels show net effective rents at GBP 611 per sq m annually, 29.5% above valuation ERV, with total passing rent of GBP 60.7 million diversified across 155 tenants (top tenant <6%). Incentives include 6-12 month rent-free periods for flagship stores, and turnover rents on 9% of income tied to sales performance. Advantages for lessees include stable collections (98% in 2023) and regear flexibility, but risks involve service charges (GBP 4.9 million billed) rising with capex for sustainability upgrades. Compared to Manchester averages (GBP 40-55 per sq ft), Trafford offers premium positioning justifying higher costs for high-traffic spots.
Competition and Risks
The Trafford Centre faces competition from Manchester Arndale (city-center, 50 million footfall, 96% occupancy) and intu Trafford Park (industrial retail focus), alongside e-commerce eroding 10-15% of traditional sales. Regional market saturation in fashion (40% of mix) and jewelry (-4% sales growth) highlights weaknesses, with 2023 tenant administrations (e.g., The Body Shop, Ted Baker) affecting 1% of rent roll, though units relet at stronger terms. Broader risks include macroeconomic factors like inflation impacting middle-income demographics, potential footfall volatility (e.g., -1.3% in Q2 2023 due to weather), and infrastructure needs for aging leisure areas. Positive offsets are 2025 plans for outdoor events and global brand introductions, enhancing leisure draw (20% of mix). Retailers should assess category fit, as F&B and health & beauty show resilience, while avoiding over-reliance on car-dependent access in a shifting mobility landscape.
Building Details
Detailed Market Analytics
City Snapshot
Manchester
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Manchester
Discover more shopping centers in Manchester.
Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Manchester
Comprehensive market intelligence for retail expansion in this city