




Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
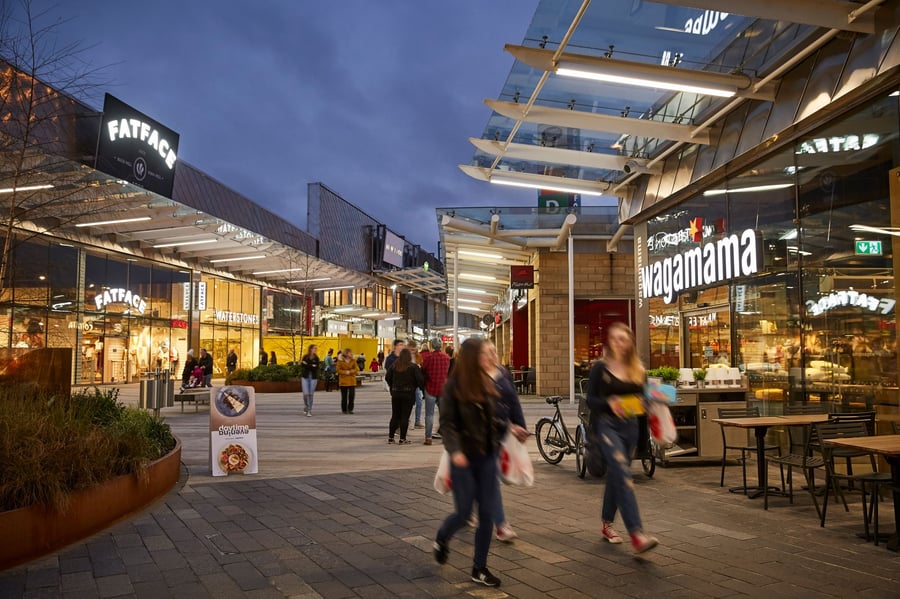
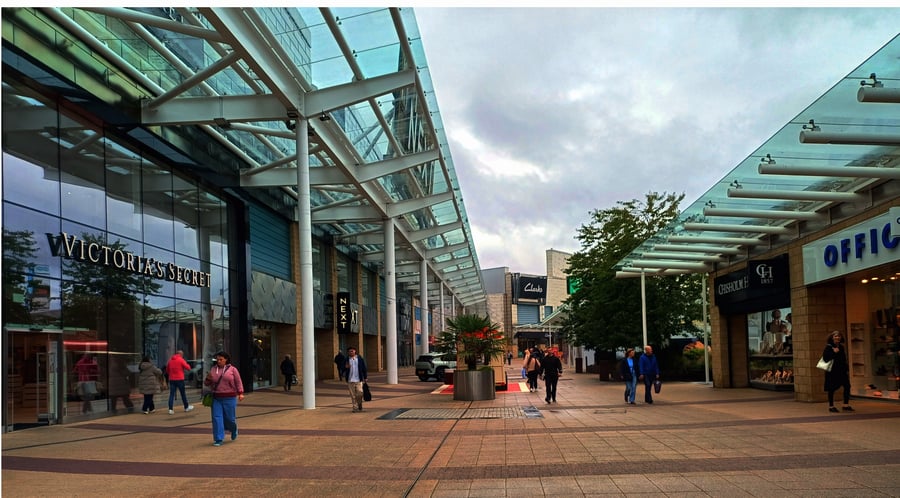
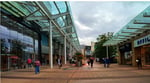
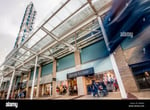
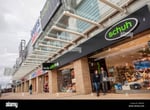
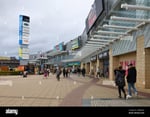
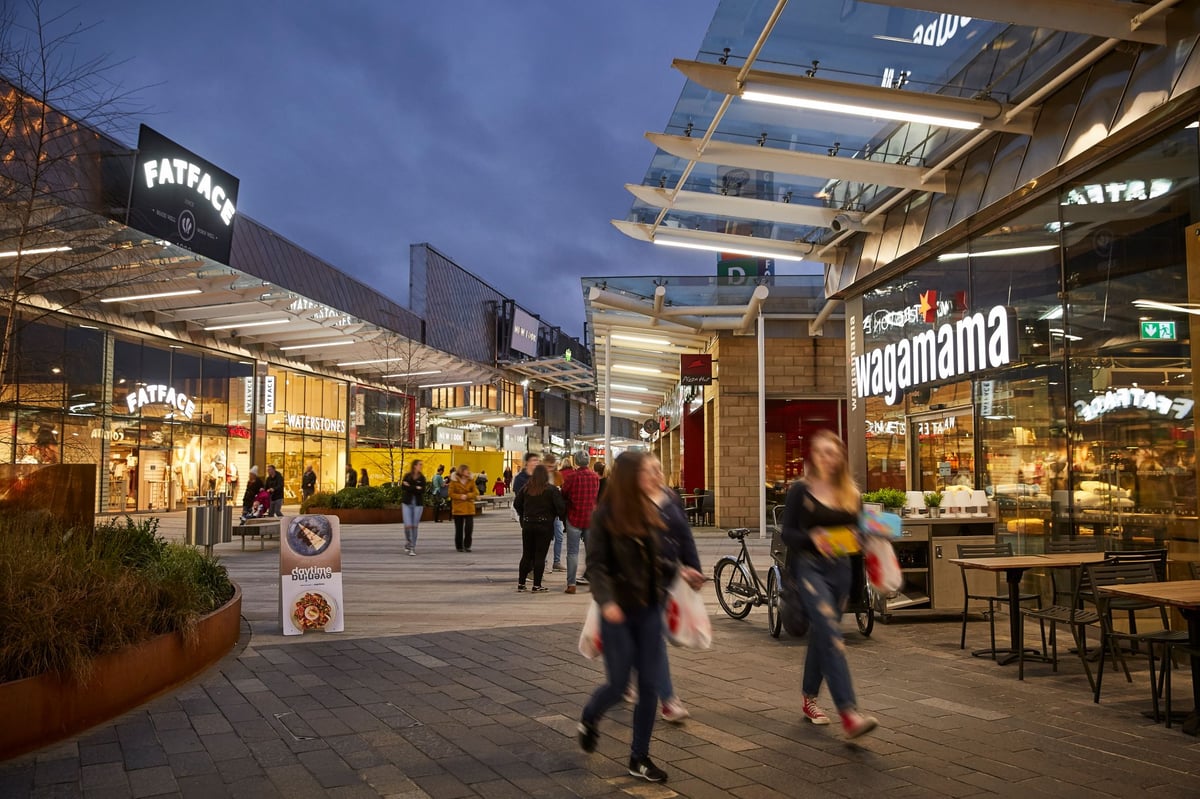
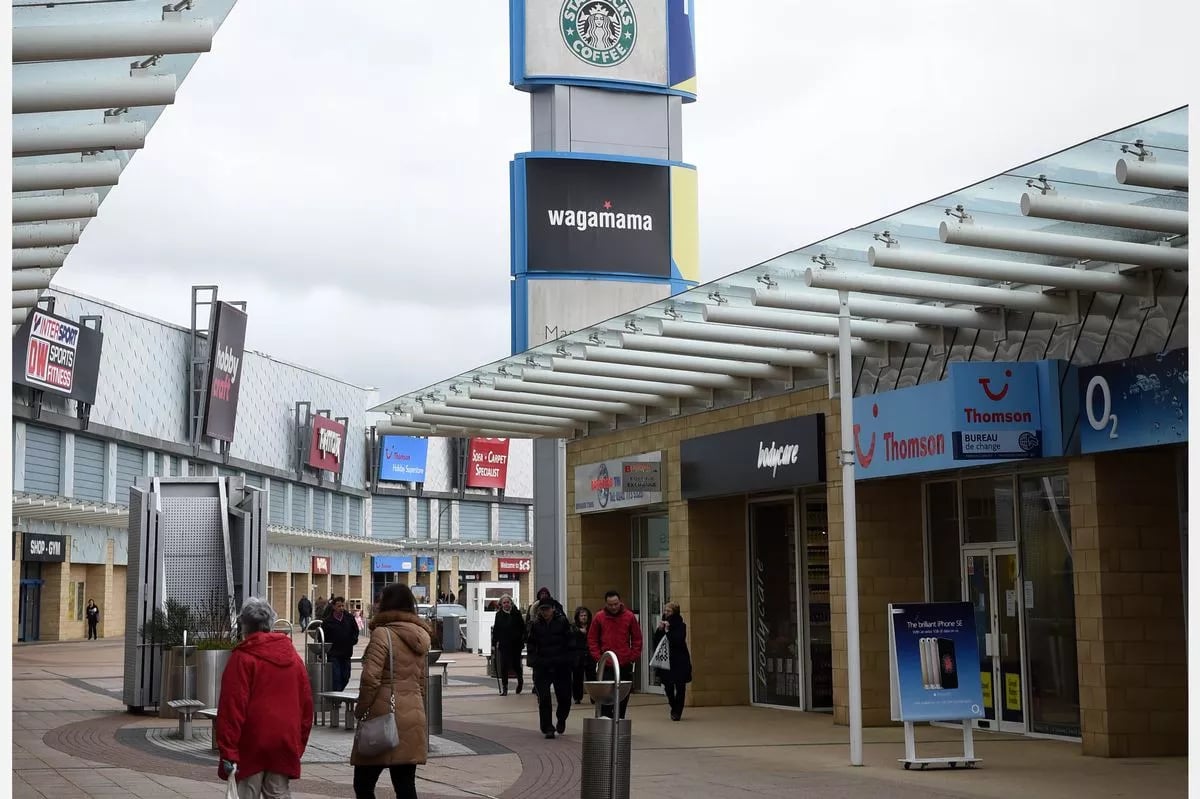
Glasgow Fort is an open-air shopping and leisure destination located in Easterhouse, on the northeastern outskirts of Glasgow, Scotland, approximately 5 miles from the city center. Opened in 2004 and expanded in subsequent years, it spans over 1.1 million square feet of retail space, accommodating more than 70 stores across fashion, home goods, electronics, and health and beauty categories. The tenant mix includes major national retailers such as Marks & Spencer, Next, H&M, and Boots, alongside dining options like Nando"s, Costa Coffee, and a 12-screen Cineworld cinema that enhances dwell time.
Positioned as a regional draw for north and east Glasgow, it benefits from strong accessibility via the M8 motorway, frequent bus services, and over 3,000 free parking spaces, attracting around 12 million annual visitors based on pre-2023 data. Market reports from Savills and Colliers highlight its stable occupancy rate of 95-98% in recent years, supported by a catchment area of 1.2 million people within a 20-minute drive, including middle-income families and young professionals.
Leasing advantages include flexible unit sizes from 1,000 to 50,000 square feet, competitive base rents averaging £25-£35 per square foot in prime locations, and turnover rents tied to sales performance, which can mitigate risks in fluctuating retail environments. However, challenges include exposure to online retail competition and seasonal weather impacts on open-air layouts, with overall sales per square foot reported at £400-£500 annually, below some enclosed urban malls.
The center maintains high operational quality through regular maintenance and security, but faces risks from nearby competing retail parks like Forge Shopping Centre. For retailers, it offers solid footfall from local demographics but requires consideration of transport dependencies for broader appeal.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 09:00 AM — 07:00 PM |
| Sunday | 10:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile
Glasgow Fort serves a diverse catchment of approximately 1.2 million residents within a 20-minute drive, primarily from north and east Glasgow areas like Easterhouse and Provanmill. According to ONS data and local market analyses, the profile features middle-income households with average annual earnings of £28,000-£35,000, a mix of families (35% with children under 18) and young adults aged 25-44 (28% of population). Footfall metrics indicate 12-14 million visitors yearly, with peak times during weekends and holidays, driven by convenience shopping and leisure. Strengths include high repeat visitation from loyal locals, but drawbacks involve lower disposable income compared to affluent west Glasgow suburbs, potentially limiting luxury retail performance. Retailers should note the area"s improving socioeconomic trends post-regeneration efforts, yet saturation in value-oriented categories could pressure margins.
Competitive Landscape
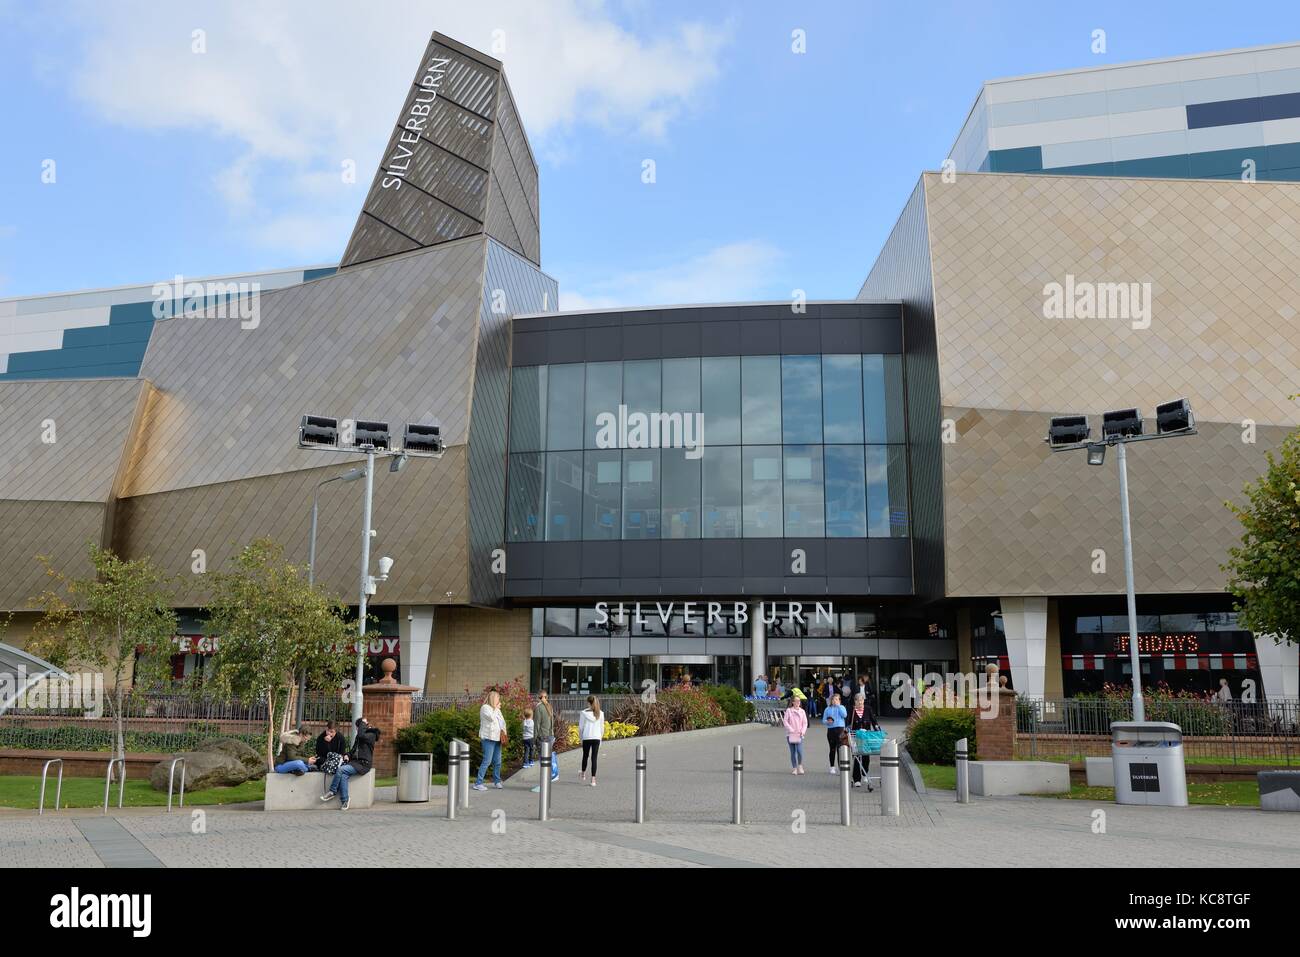
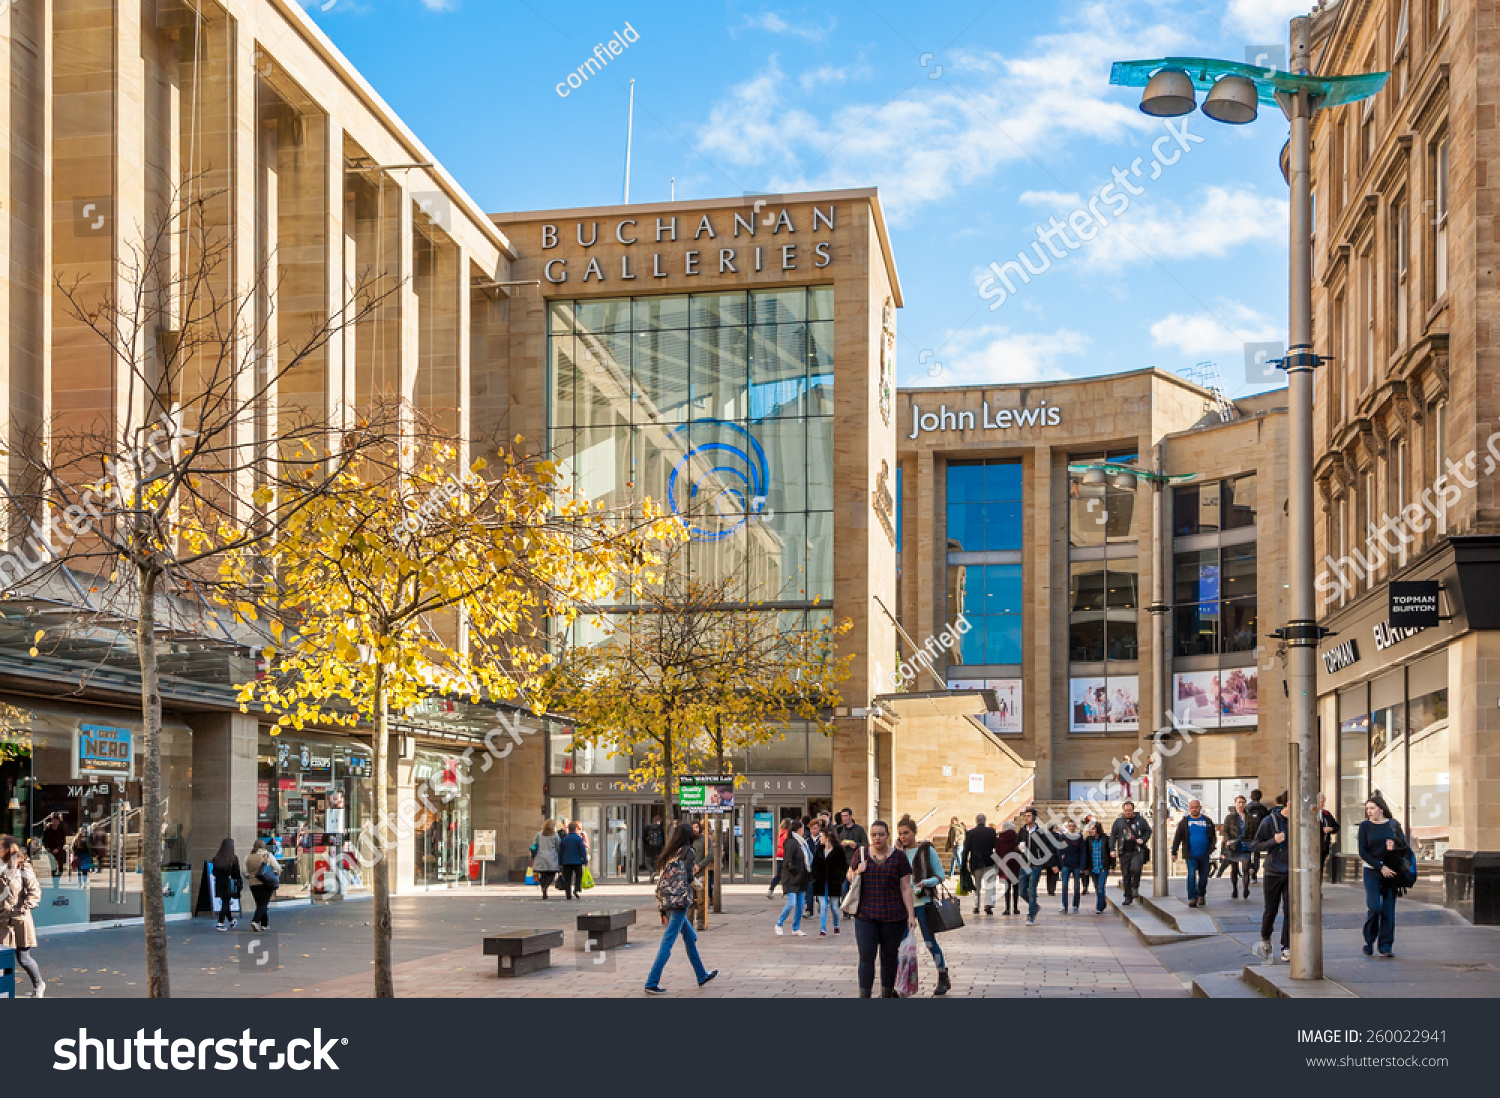
The surrounding retail market includes nearby competitors such as The Fort Shopping Park (0.5 miles away, focused on discount outlets) and Buchanan Galleries in central Glasgow (5 miles south, with higher-end tenants). JLL reports position Glasgow Fort as a mid-tier destination with 95% occupancy, but it faces pressure from e-commerce growth, which captured 25% of UK retail sales in 2023, and emerging out-of-town developments like Silverburn. Key risks include tenant mix overlap in fast fashion and homeware, leading to intra-mall competition, and access issues during peak traffic on the M8. Advantages lie in its leisure integration, boosting average spend by 20% via cinema and dining synergies. Retailers evaluating leases should assess category-specific saturation, as electronics and apparel show 5-7% vacancy risks amid market shifts toward experiential retail.
Leasing Metrics and Risks
Base rents at Glasgow Fort range from £25-£35 per square foot for ground-floor units, with service charges around £8-£10 per square foot covering maintenance and marketing, per Knight Frank data. Lease terms typically span 5-15 years with break clauses at year 5, and incentives like rent-free periods of 3-6 months for new tenants. Occupancy remains robust at 97%, supported by sales productivity of £450 per square foot annually, though below the UK average of £550. Operational challenges include aging infrastructure in some wings, requiring potential capex contributions, and weather-related footfall dips in winter. Market saturation in discount retail poses risks, with 10% of units in weaker categories like stationery facing renewals pressure. For balanced evaluation, retailers benefit from strong accessibility but must weigh competition from online channels and ensure alignment with the value-driven tenant mix to optimize ROI.
Building Details
Detailed Market Analytics
City Snapshot
Glasgow, SCT
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Glasgow
Discover more shopping centers in Glasgow.

Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Glasgow, SCT
Comprehensive market intelligence for retail expansion in this city