Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
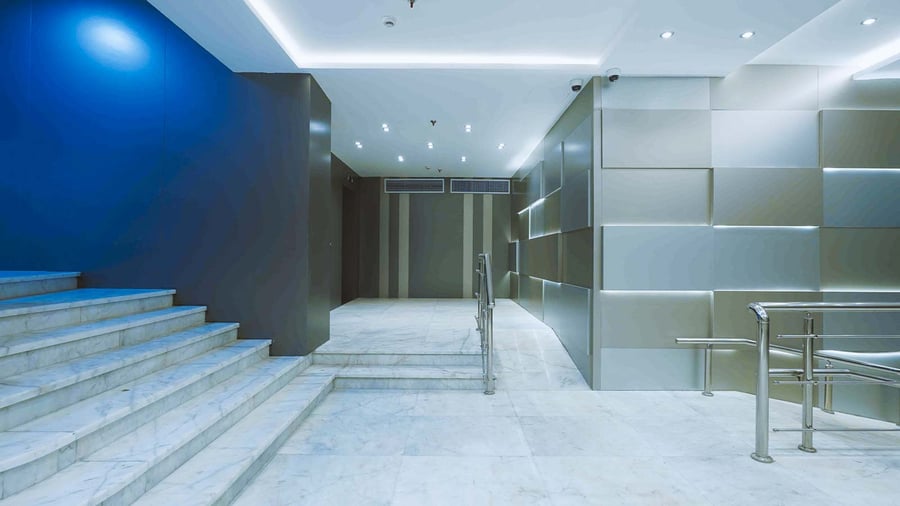
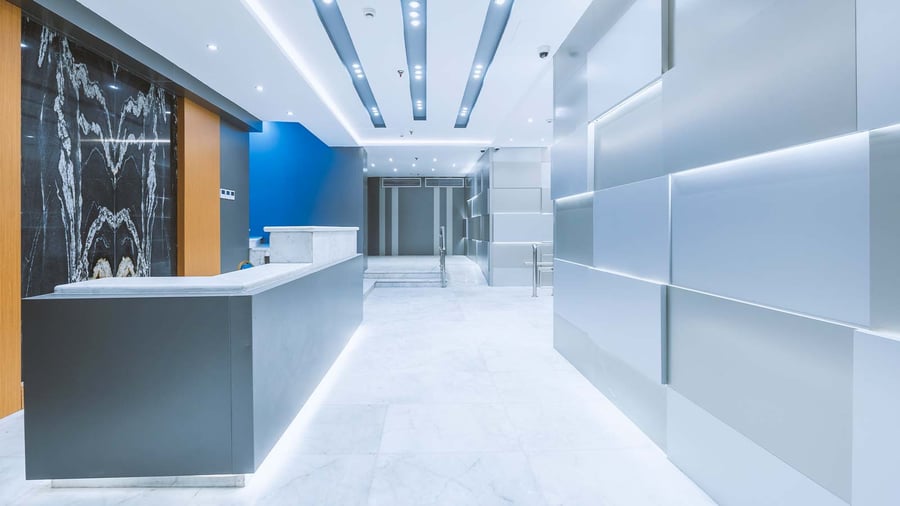
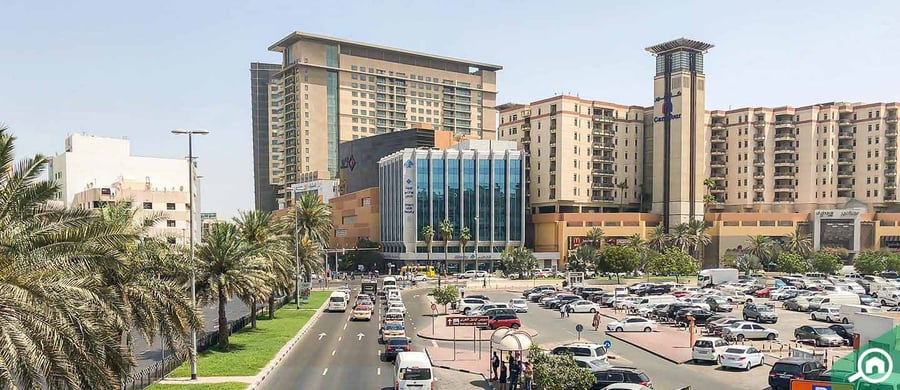
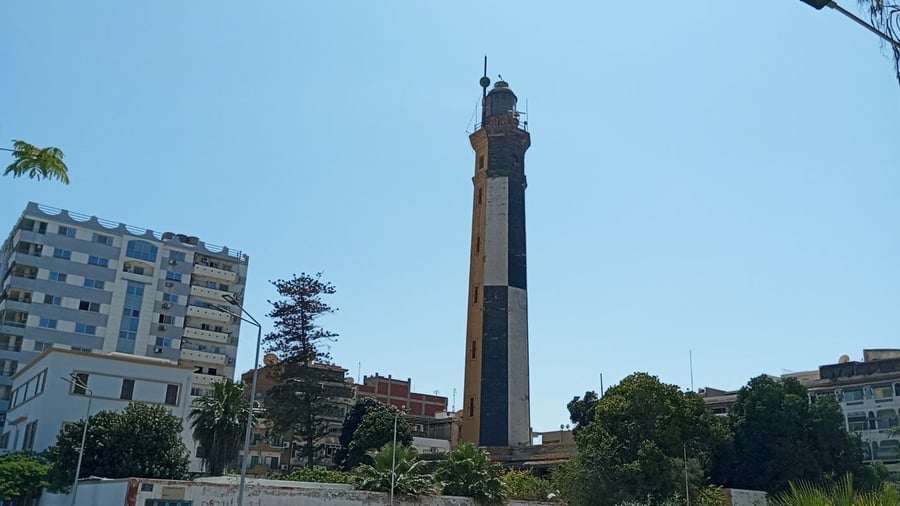
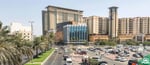
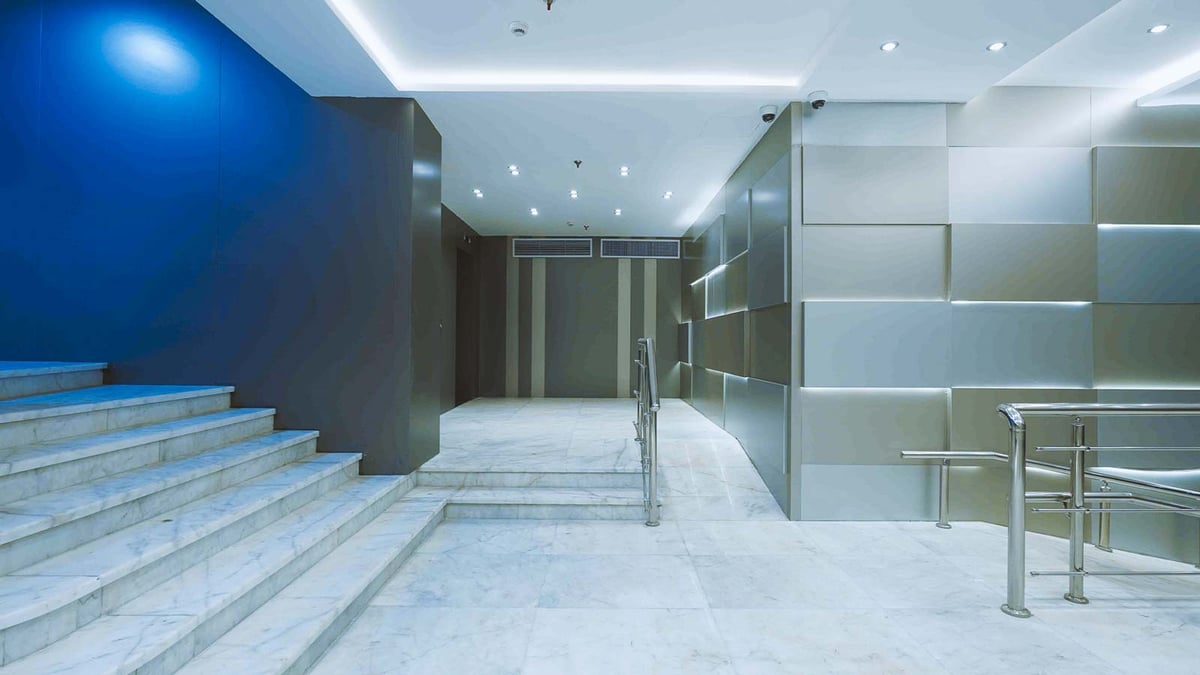
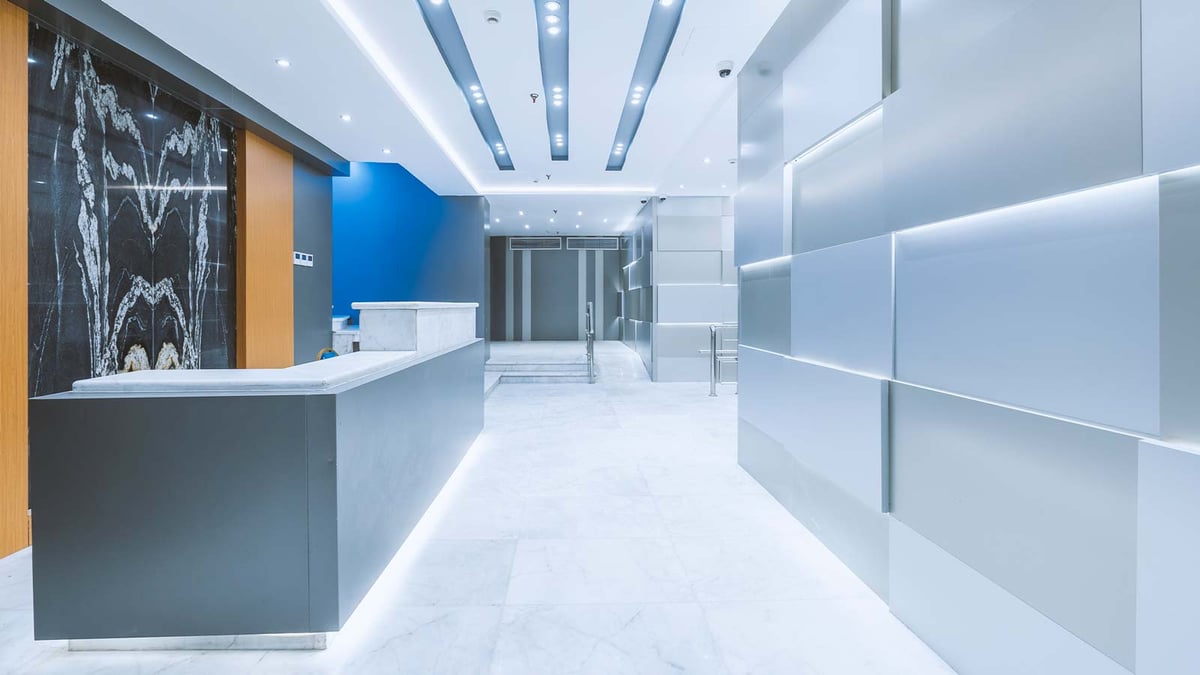
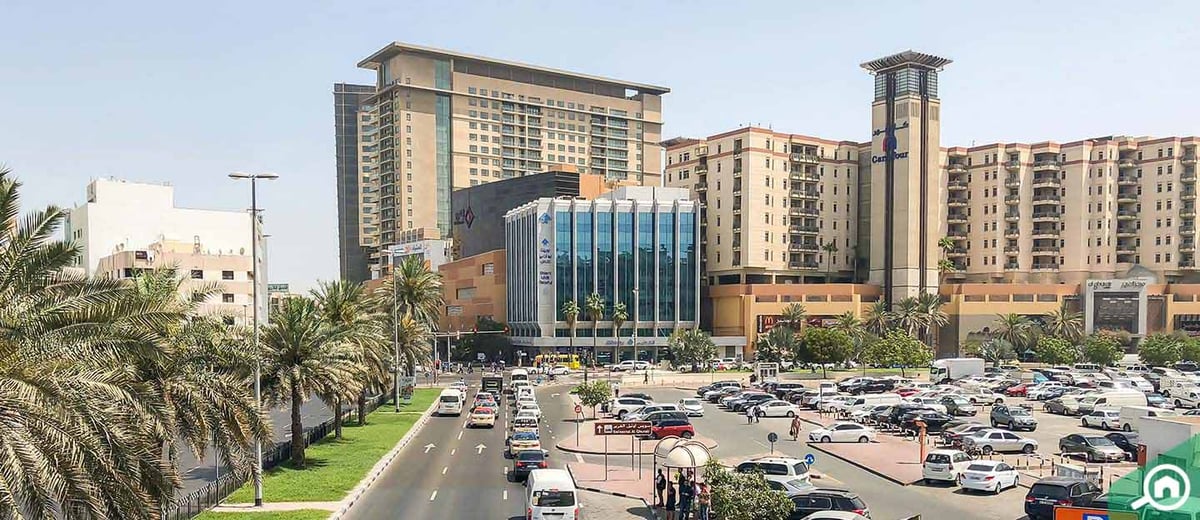
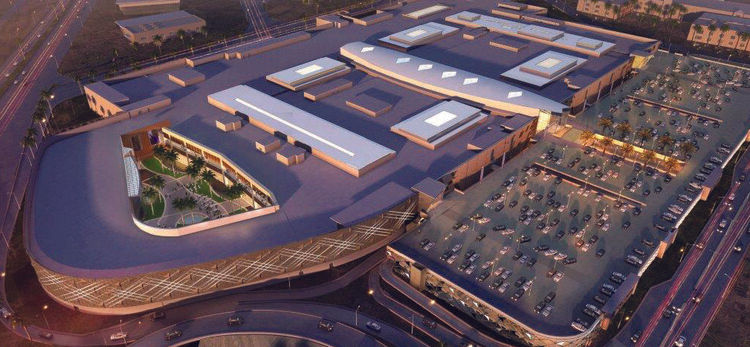
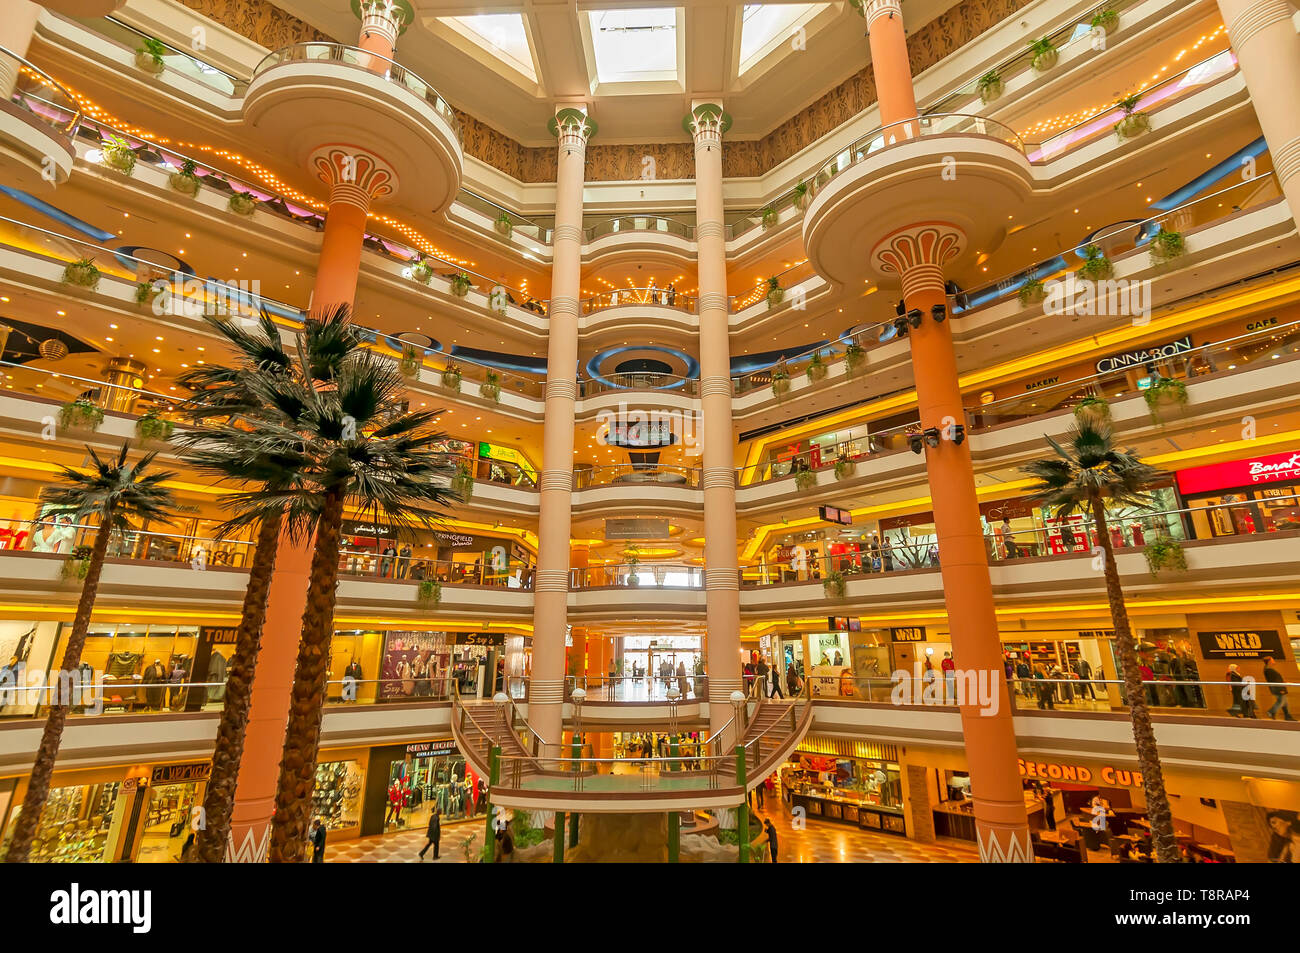
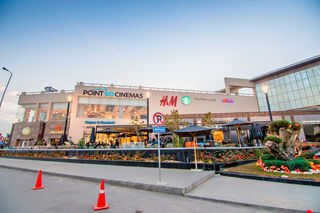
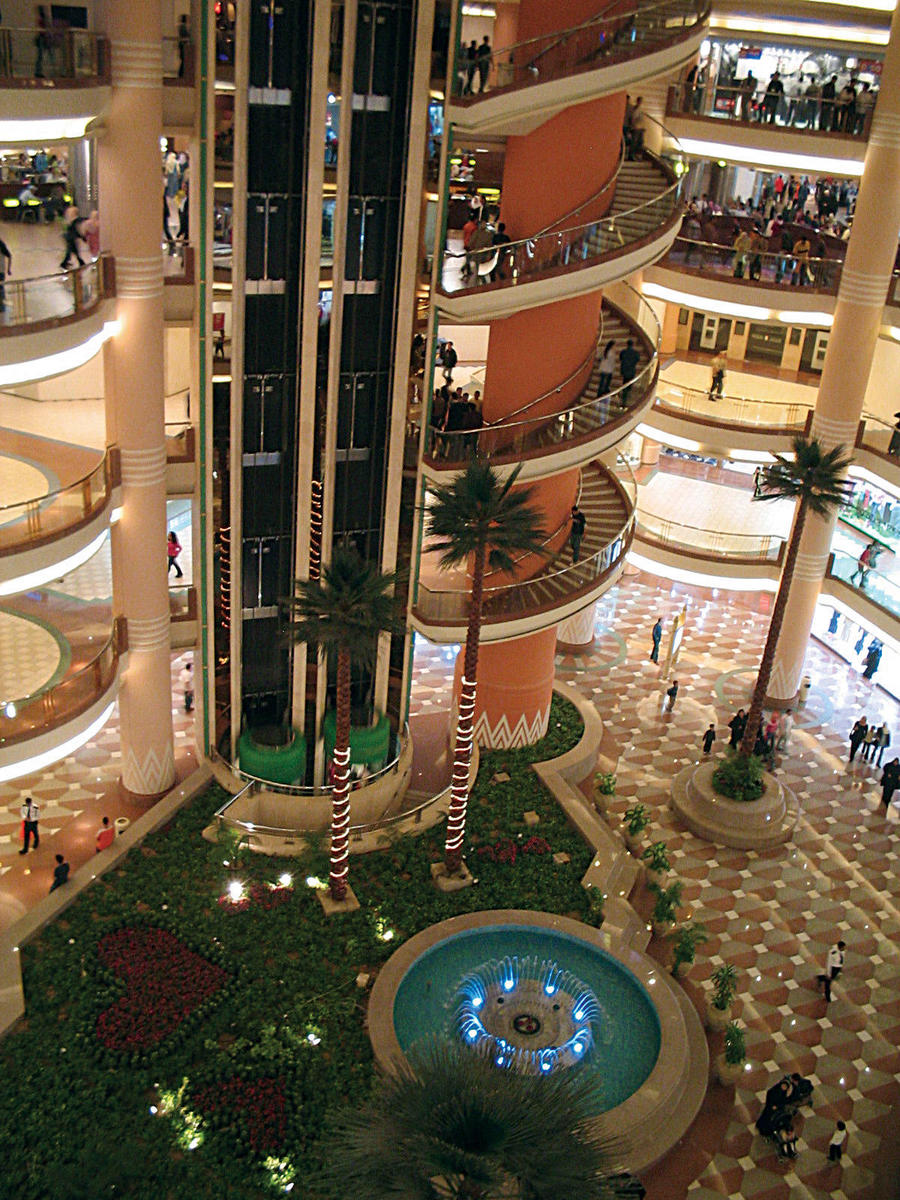
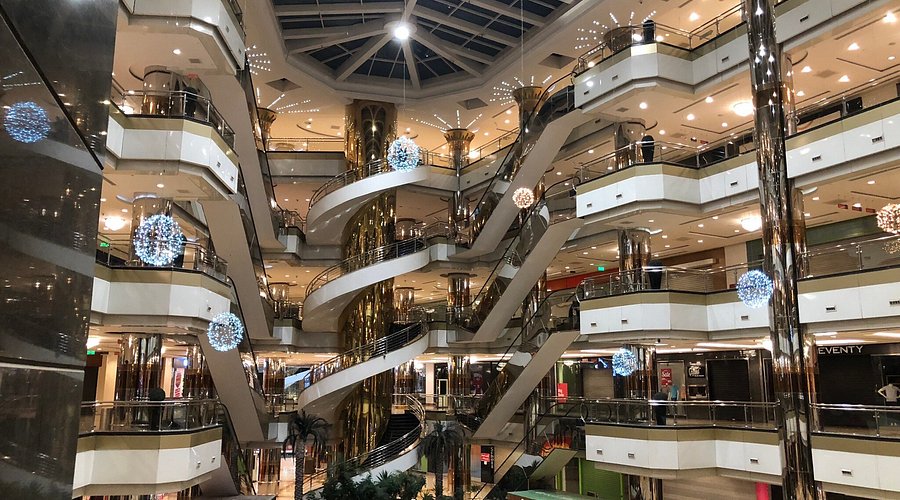
Port Said Mall is situated in the El Shark District of Port Said, Egypt, at the northern entrance to the Suez Canal, spanning 40,000 square meters of gross leasable area across 3 levels with 60-80 retail outlets. The tenant mix is value-oriented and diverse, comprising 40% fashion and apparel including LC Waikiki, 30% food and beverage with a food court offering Egyptian and Mediterranean options, 20% services, and 10% entertainment such as a cinema.
Anchor tenants include Carrefour Express supermarket and clothing stores, supporting synergy in apparel and F&B categories though with over-reliance on local brands. Occupancy stands at 88%, above the national average of 82% for secondary markets, with 3,200 square meters available and low tenant turnover. Average daily footfall is 6,000 visitors, peaking at 10,000 on weekends, driven by 70% local shoppers and 30% port-related visitors, yielding annual traffic of 4,000,000 with 2-hour dwell time and 25% conversion rate.
Rent levels range from EGP 300-500 per square meter annually for ground floor spaces, with leases of 3-5 years including inflation escalations, providing competitive rates in a market with 15-20% organized retail penetration. The primary catchment is 800,000 people within 10 km, secondary 1,500,000, featuring middle-income households averaging EGP 10,000-15,000 monthly, median age 25-28, and retail spending of USD 600 per capita yearly.
Market position is dominant locally, with sales per square meter at USD 5,000 annually, low competitor density, and growth projected at 5% for footfall amid Egypt's 7% CAGR in commercial real estate through 2025.
Leasing advantages include flexible terms for small retailers, fit-out incentives, stable demand from logistics and trade sectors, ample 600-1,000 parking spaces, and high accessibility via roads and public transport. However, challenges encompass economic volatility, inflation impacting disposable income, high e-commerce growth at 25% annually, and competition from informal markets capturing 60% of spend, alongside potential aging infrastructure in older sections requiring upgrades.
Operational quality is moderate, with monthly promotions and 40% loyalty penetration, but category saturation in F&B poses margin risks.
Overall, it offers practical opportunities for value-driven retailers in a growing secondary market influenced by Suez Canal activity.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 11:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment
Port Said Malls catchment encompasses 800,000 residents in a 10 km primary area and 1,500,000 in secondary, with 2% annual population growth. Median age is 25-28 years, household size 3.4, and 28% tertiary education level. Median household income stands at USD 4,000 yearly, with unemployment at 7.5% and cost of living index of 35 (NY=100). Retail spending per capita is USD 600 annually, including USD 124 on apparel, USD 450 on groceries, and USD 150 on electronics. The demographic profile targets families and young professionals in trade and shipping sectors, supported by Suez Canal economic activity, though economic volatility and inflation reduce disposable income, limiting premium retail potential and increasing risks for high-end tenants.
Competition and Market Factors
Competitor density is low for similar malls, but informal markets like El-Gaish Commercial Center capture 60% of retail spend, while e-commerce grows at 25% yearly with 82% internet penetration and 30% click-and-collect adoption. Organized retail penetration is 15-20%, below Cairo's levels, with medium saturation in basic goods categories. Port congestion and currency fluctuations affect imports and traffic. Strengths include proximity to port boosting transient visitors, but drawbacks involve seasonal tourism fluctuations and lower footfall (6,000 daily vs. 20,000+ in major cities), potentially challenging sales for non-essential categories amid market saturation in F&B and reliance on local brands limiting international appeal.
Lease Terms and Operational Quality
Leases offer 3-5 year terms with moderate flexibility, escalations tied to inflation, and incentives like fit-out contributions for small-format retailers. Average rent is EGP 900 per square meter monthly, competitive for secondary markets with USD 5,000 sales per square meter annually. Operational aspects feature high accessibility, 600-1,000 parking spaces, CCTV security, low crime rates, monthly promotions, digital signage, and 40% loyalty program penetration, with planned expansions and 10 new tenants in pipeline. Challenges include moderate maintenance in aging sections built in early 2000s (renovated 2018), over-reliance on local tenants, and F&B saturation pressuring margins, alongside access issues from port traffic, advising due diligence on infrastructure upgrades for long-term viability.
Building Details
Detailed Market Analytics
City Snapshot
Port Said
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Port Said
Discover more shopping centers in Port Said.
Popular in Egypt
Top retail destinations across Egypt.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Port Said
Comprehensive market intelligence for retail expansion in this city