Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
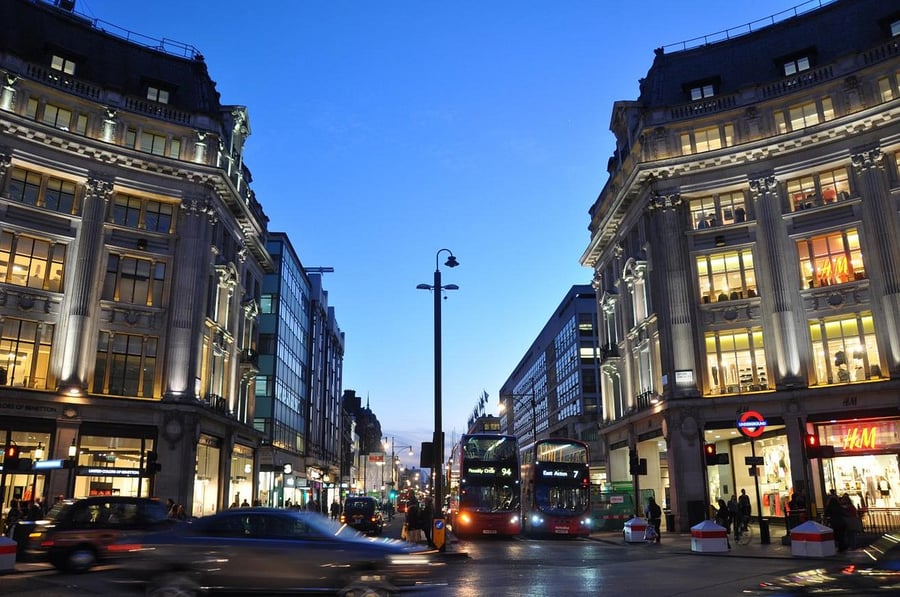
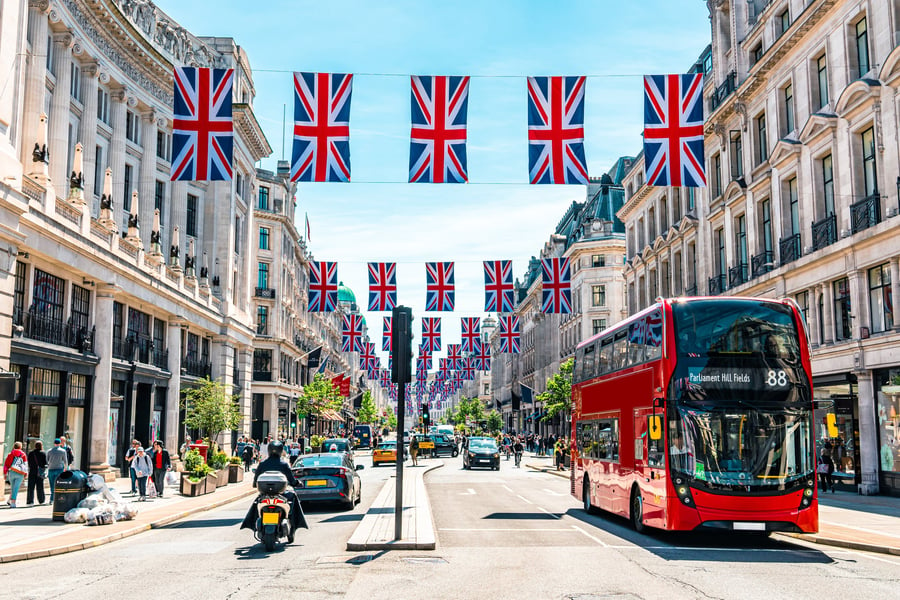
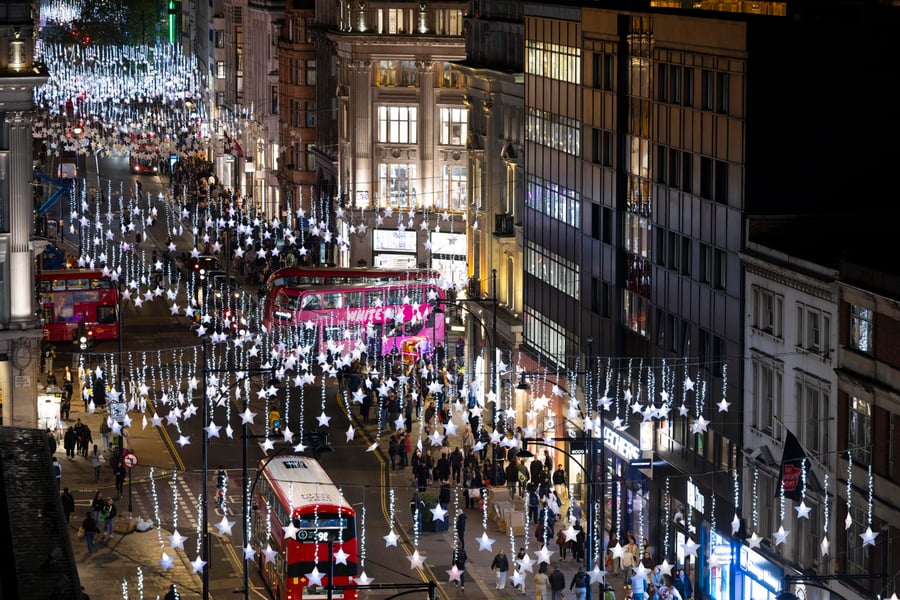
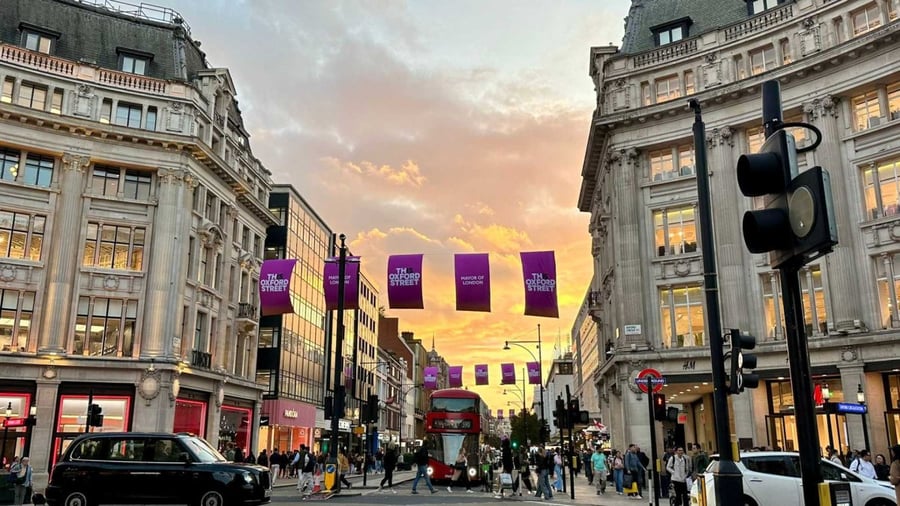
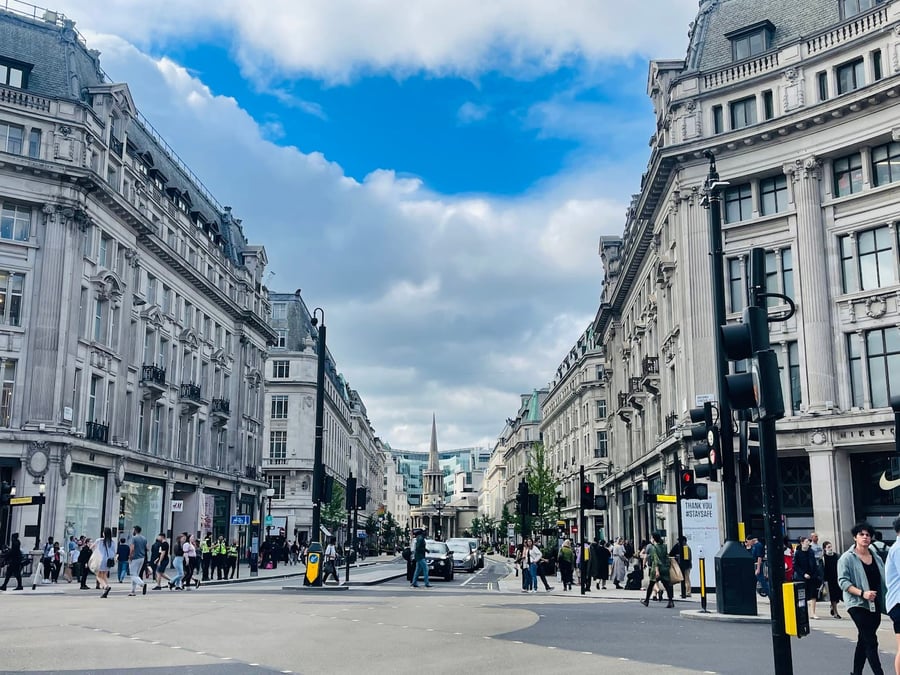
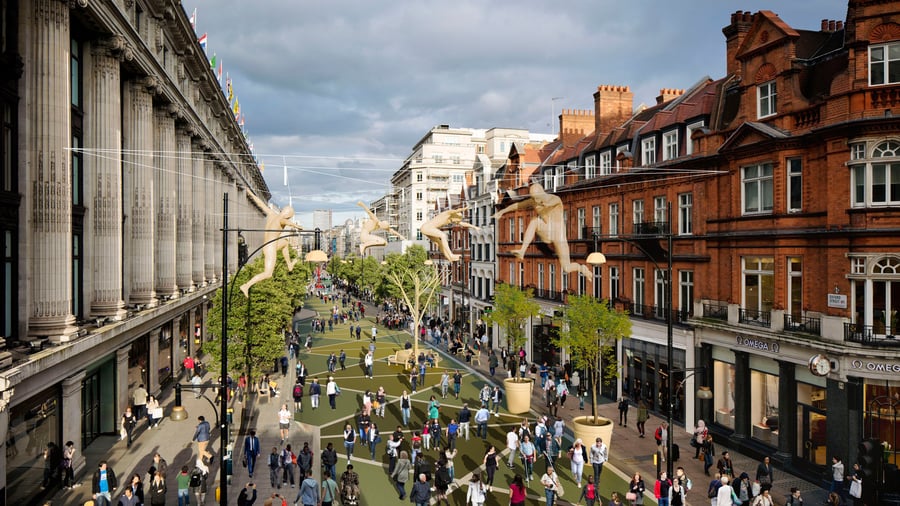
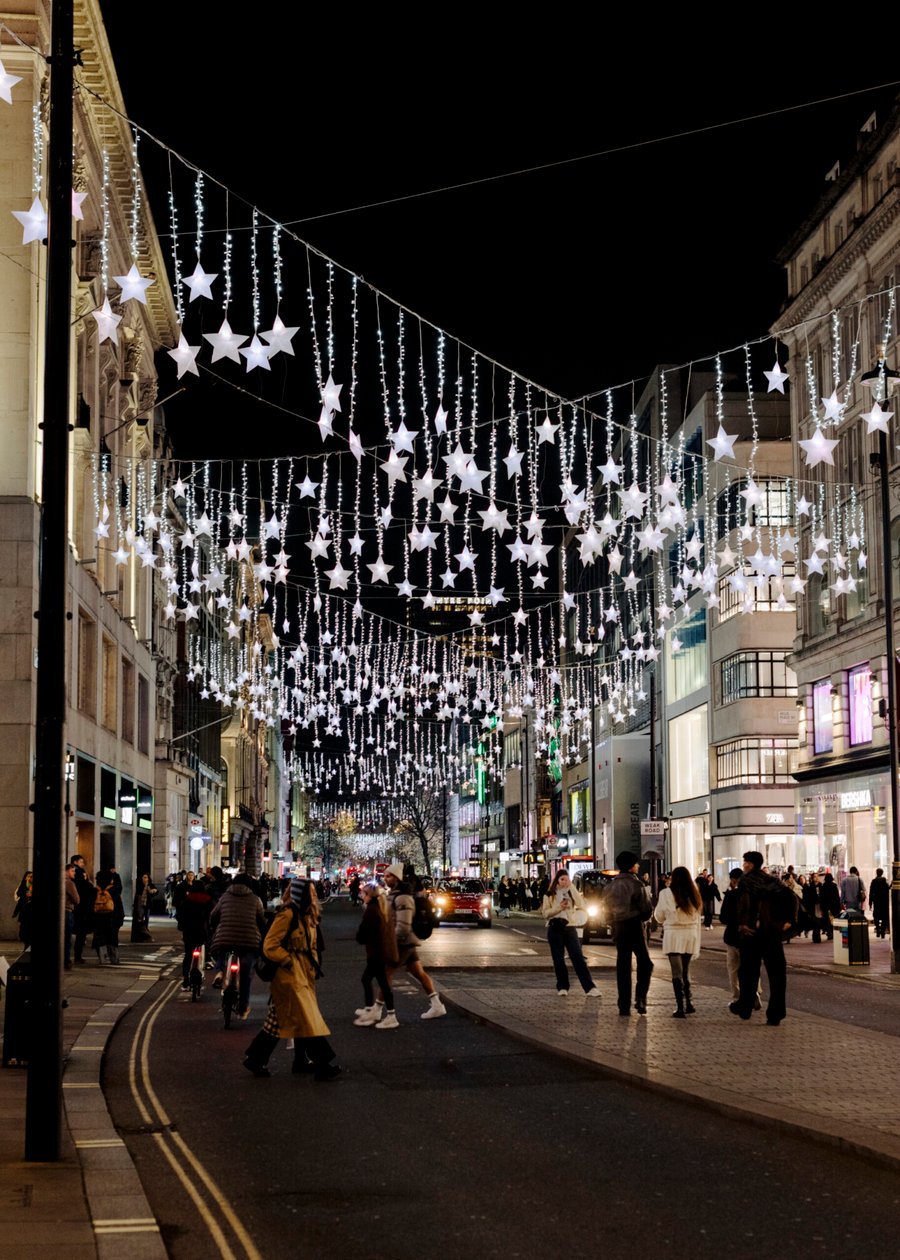
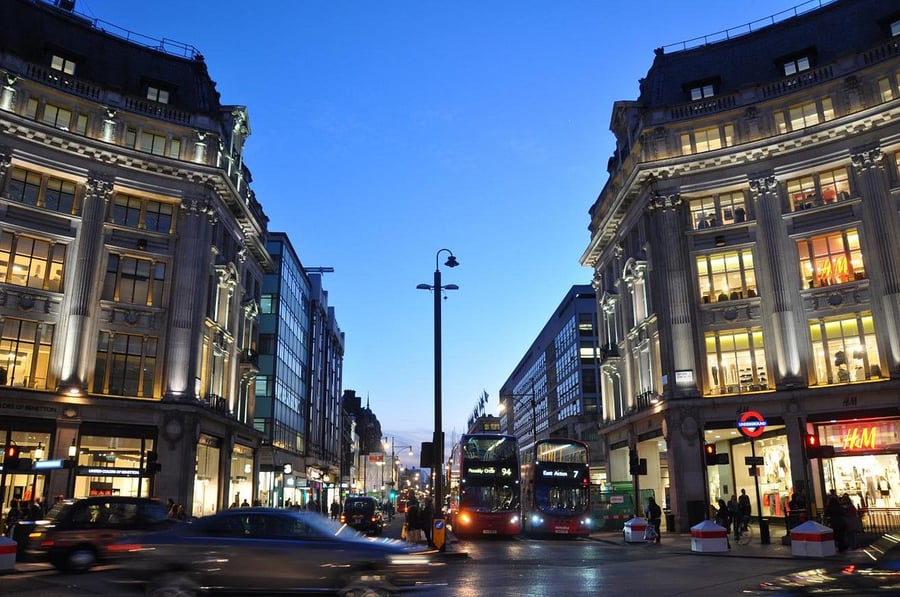
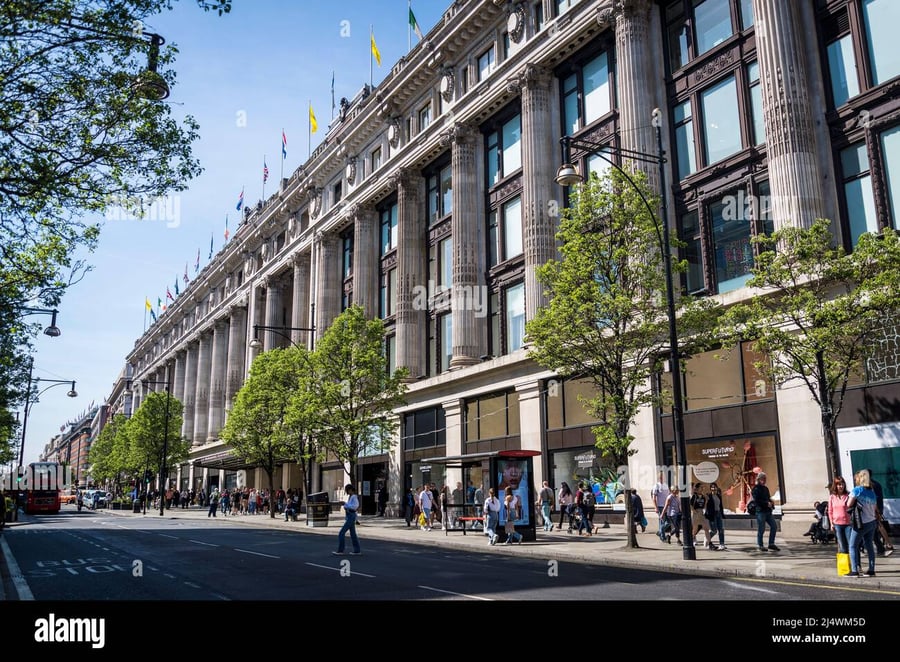
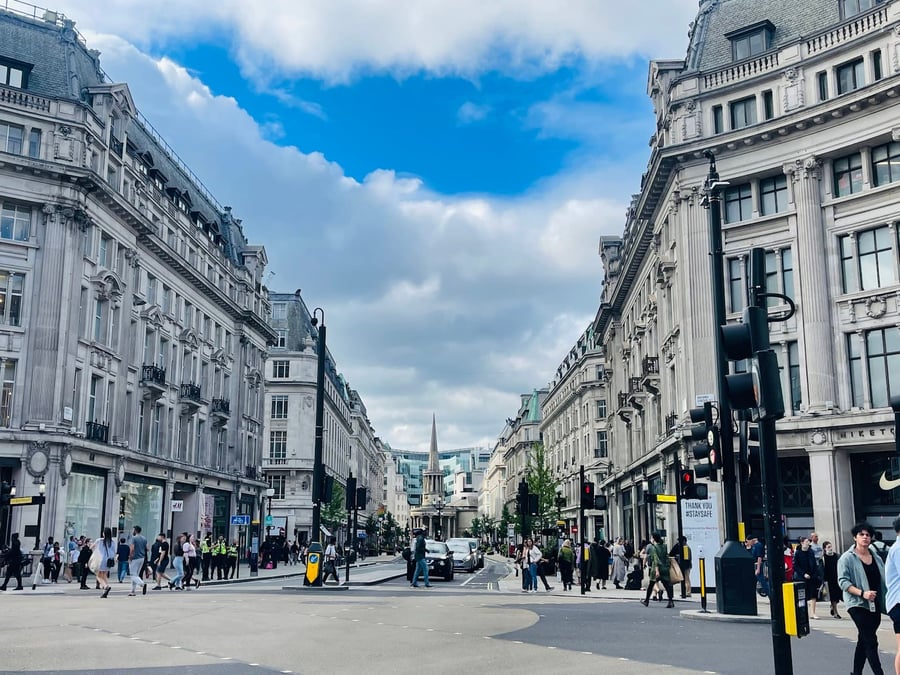
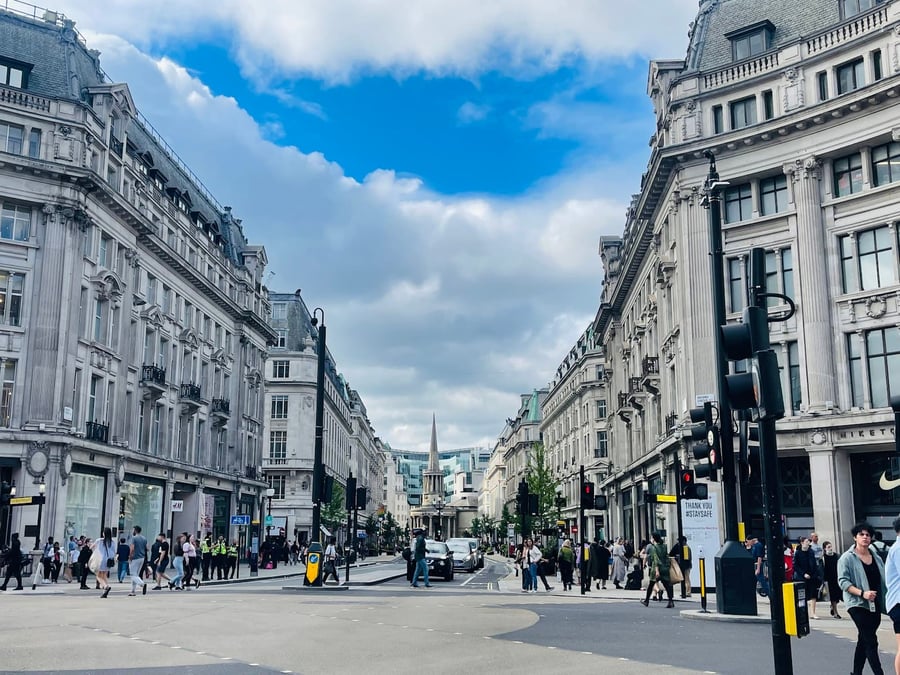
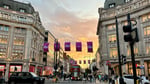
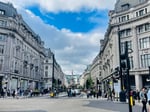
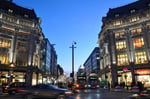
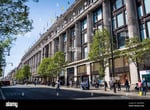
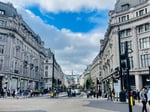
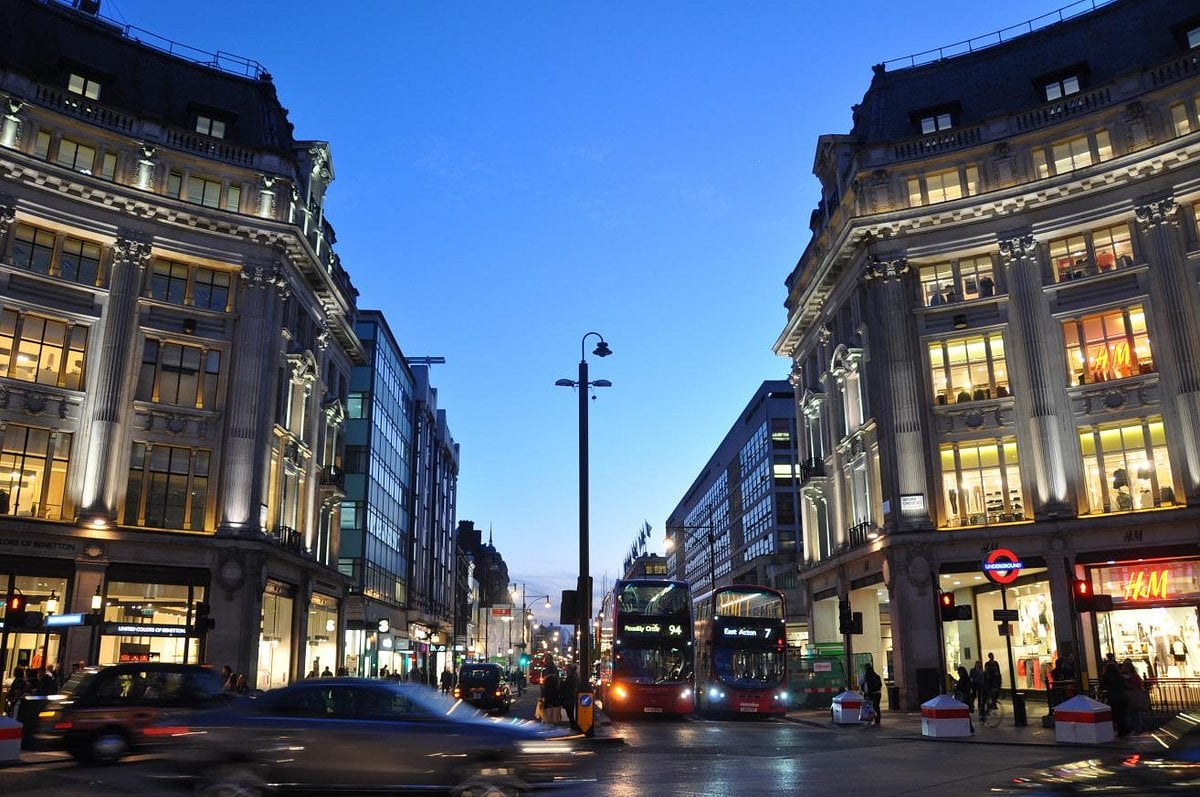
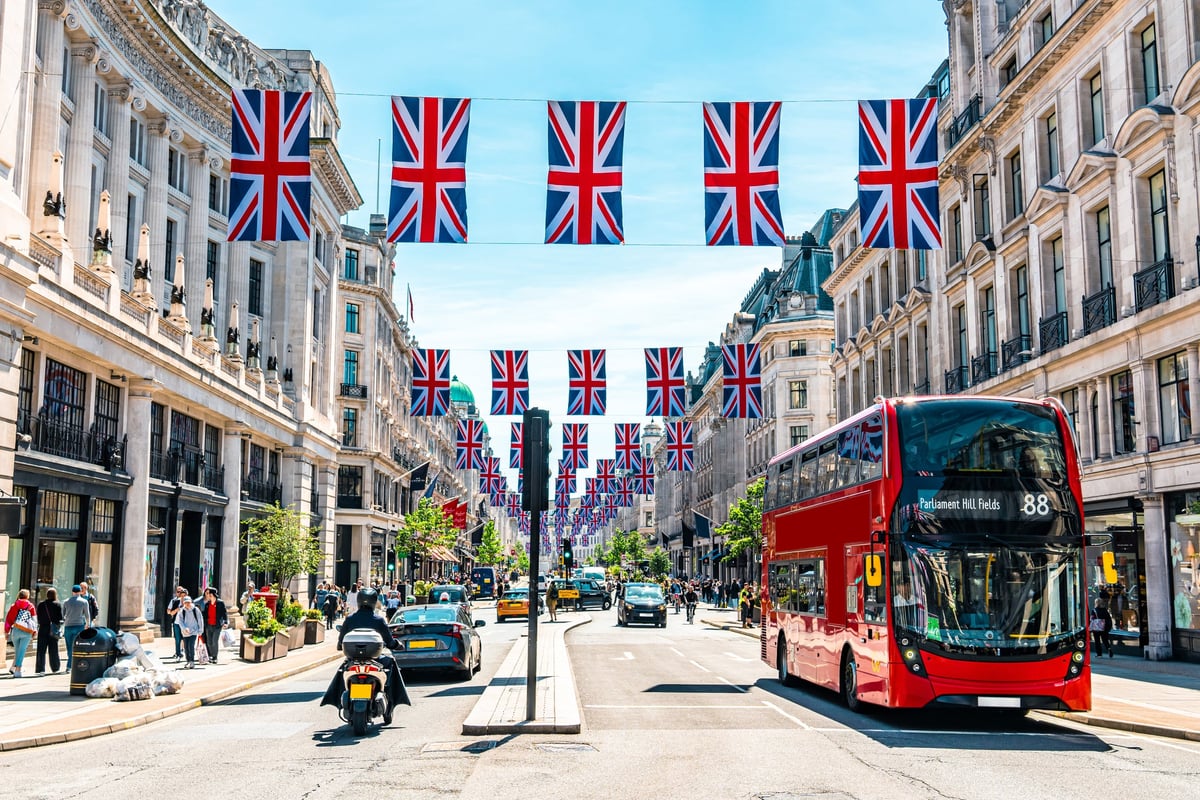
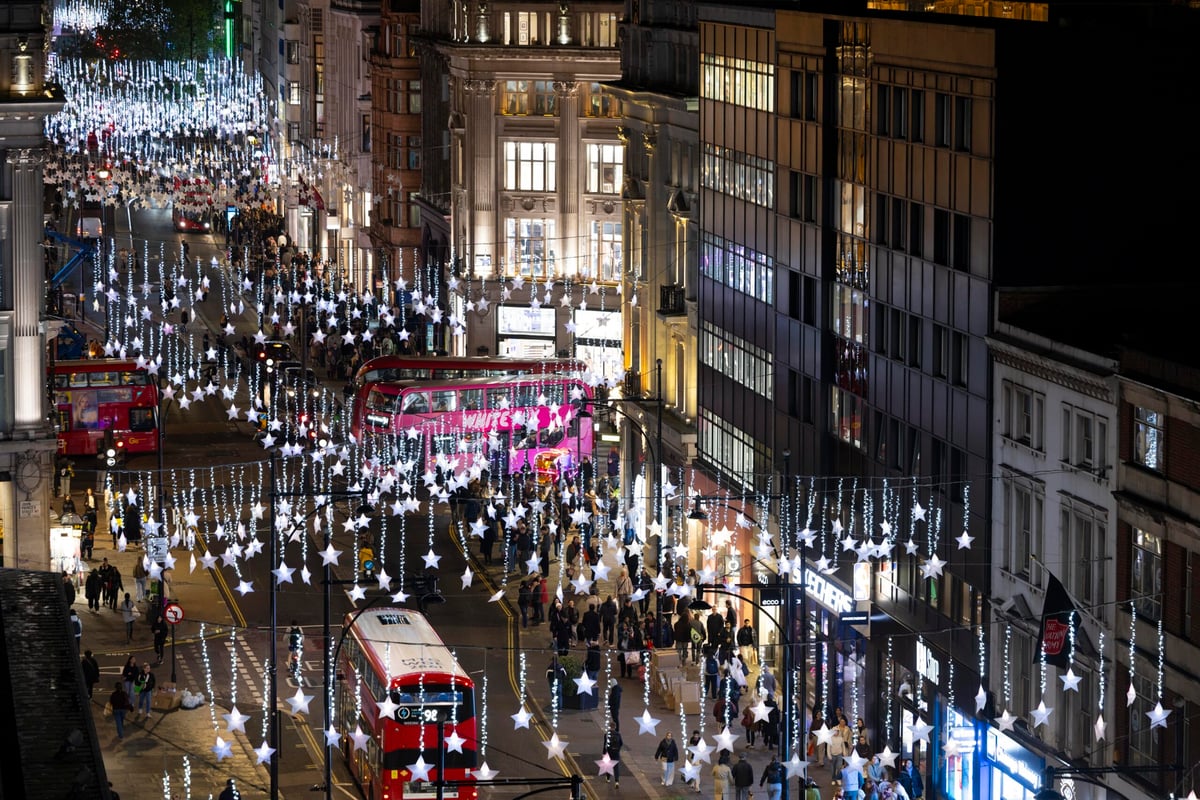
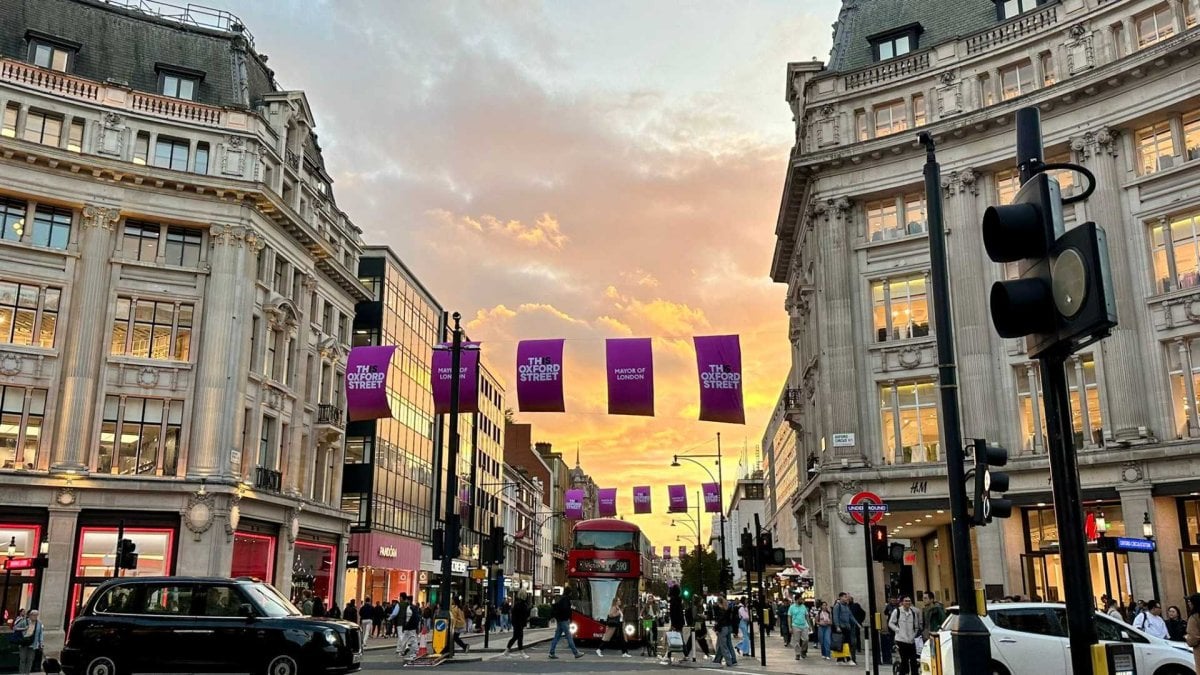
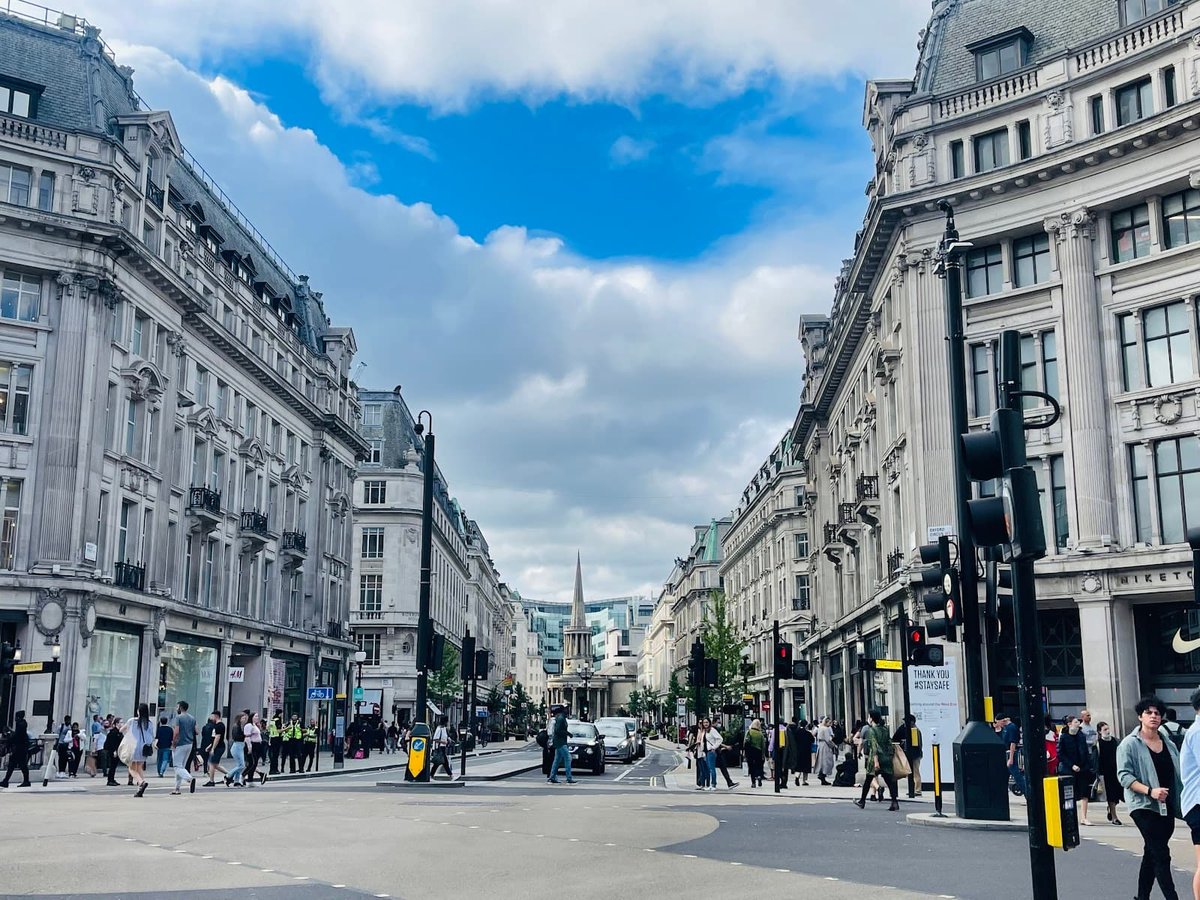
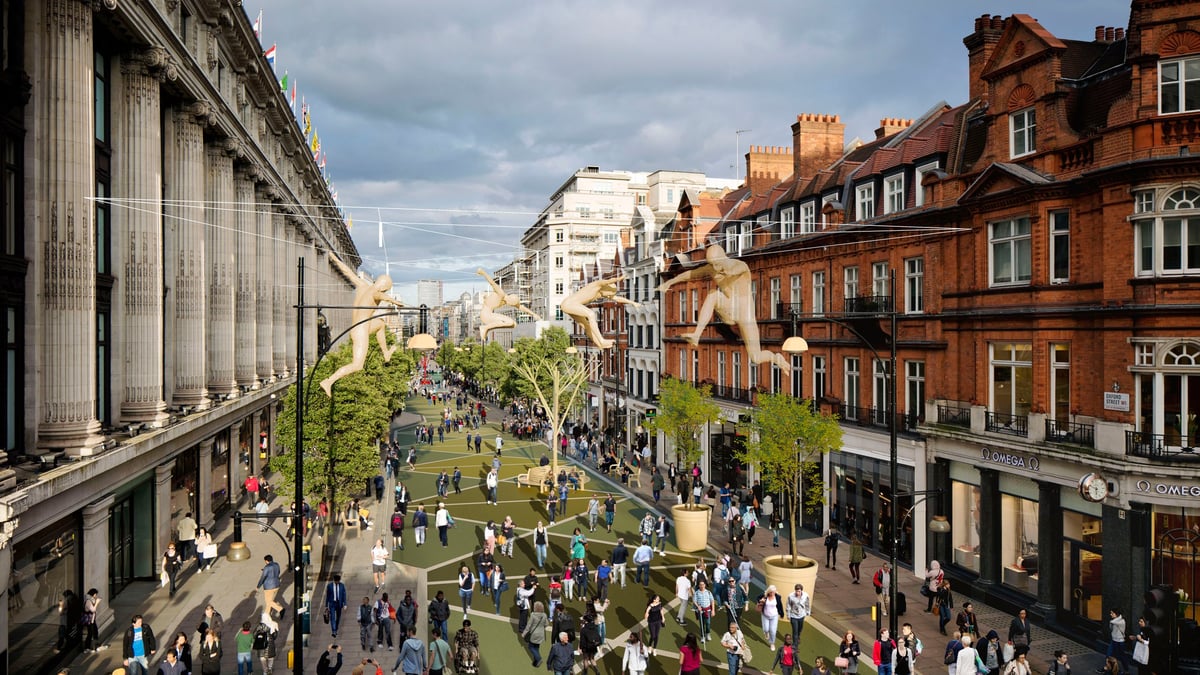
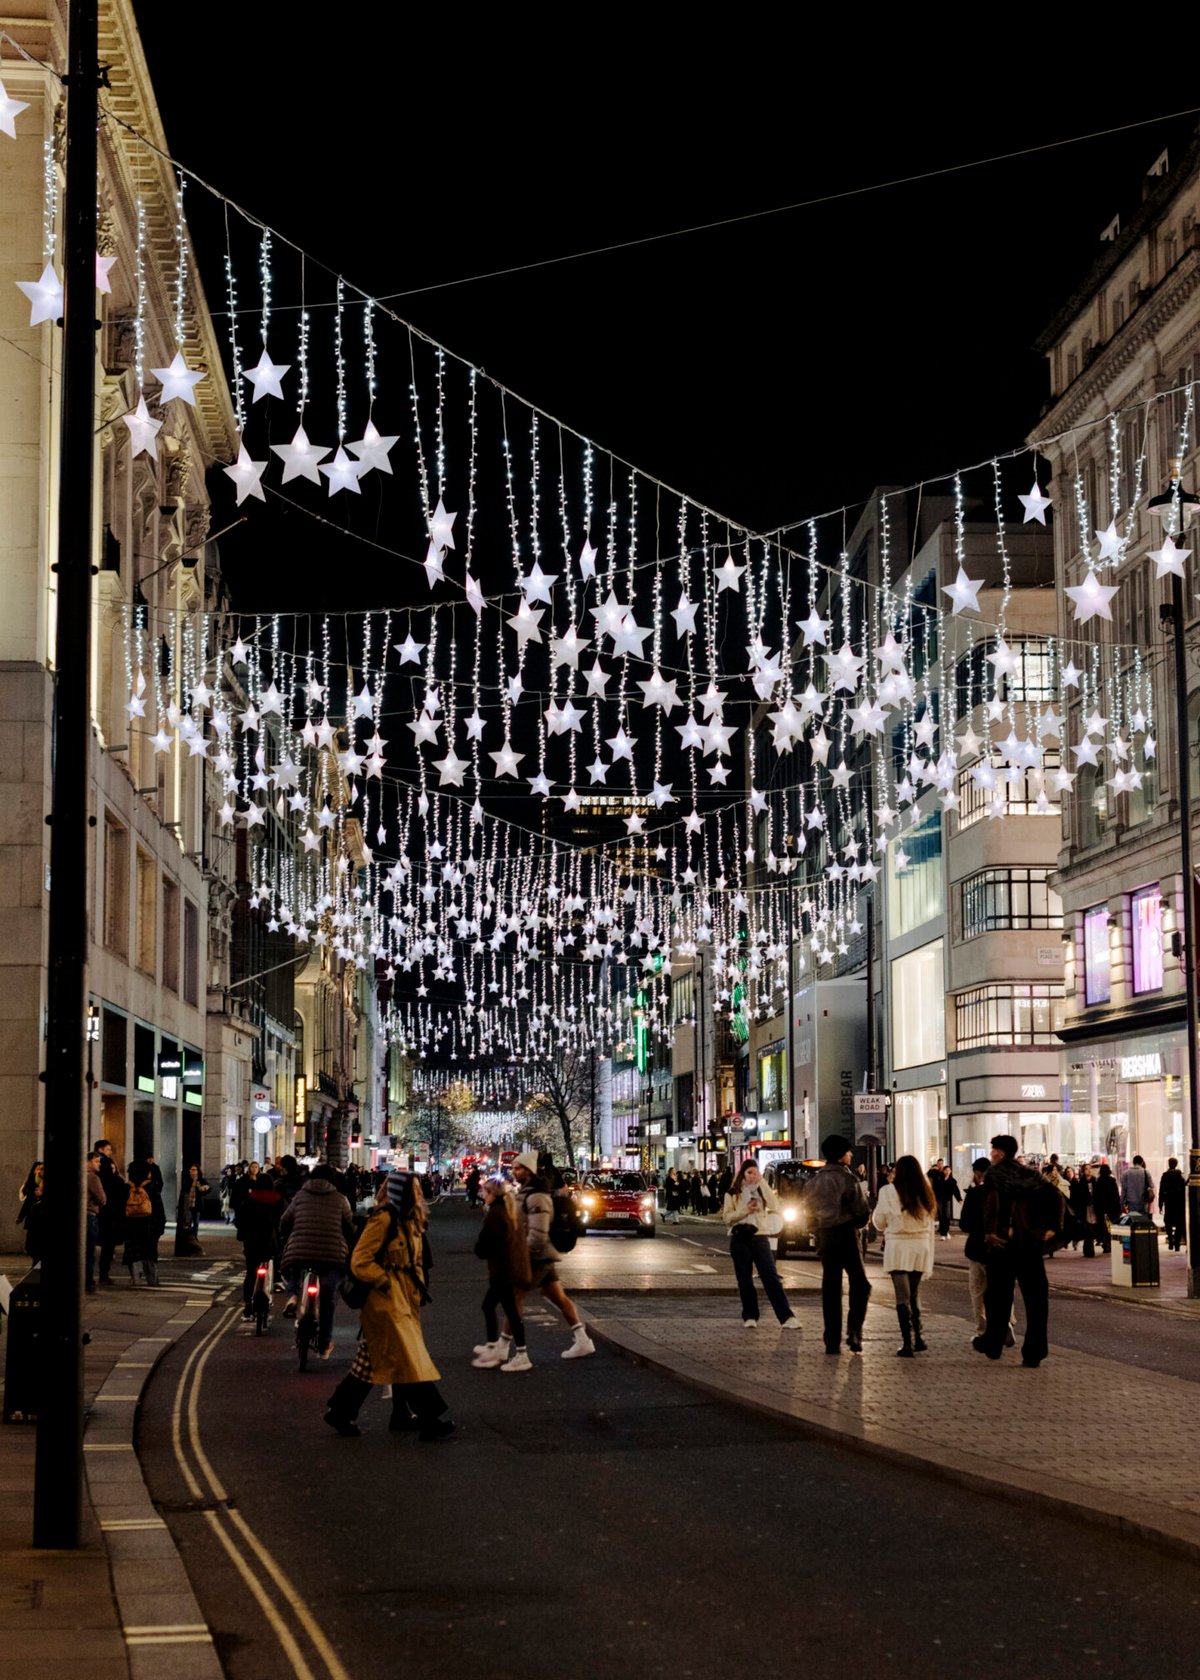
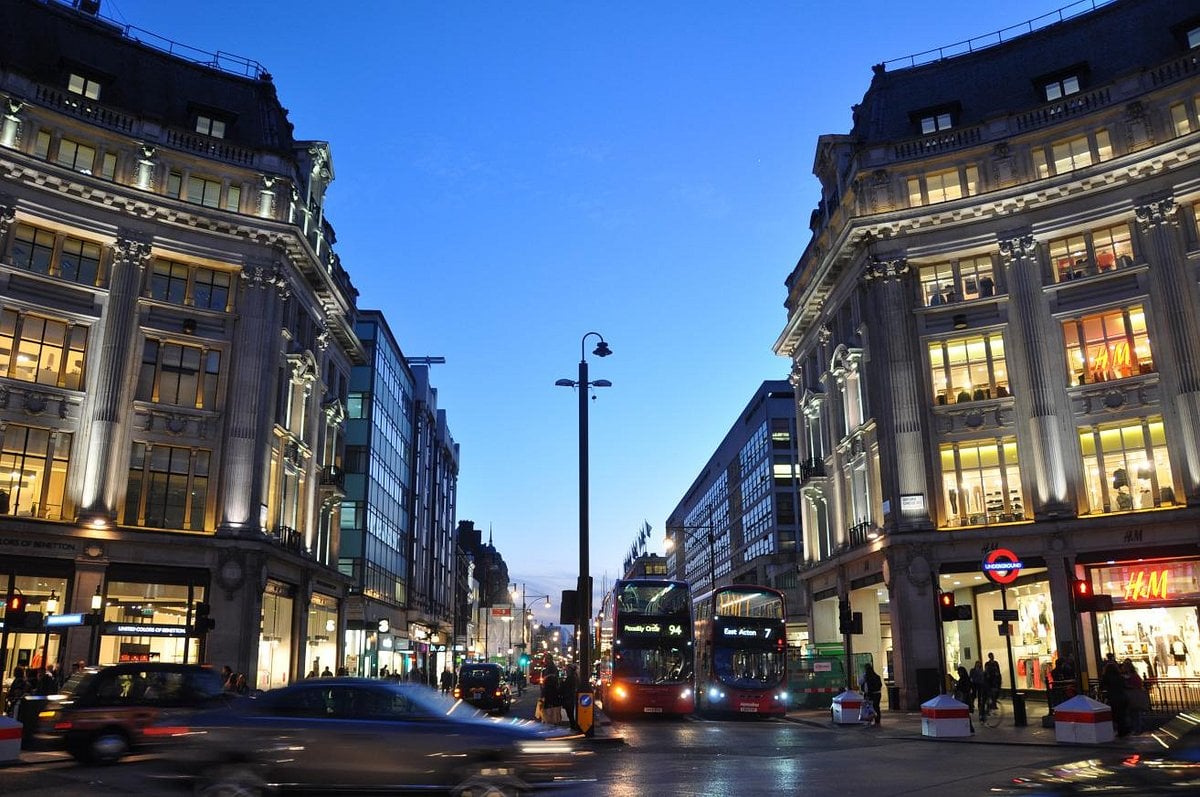
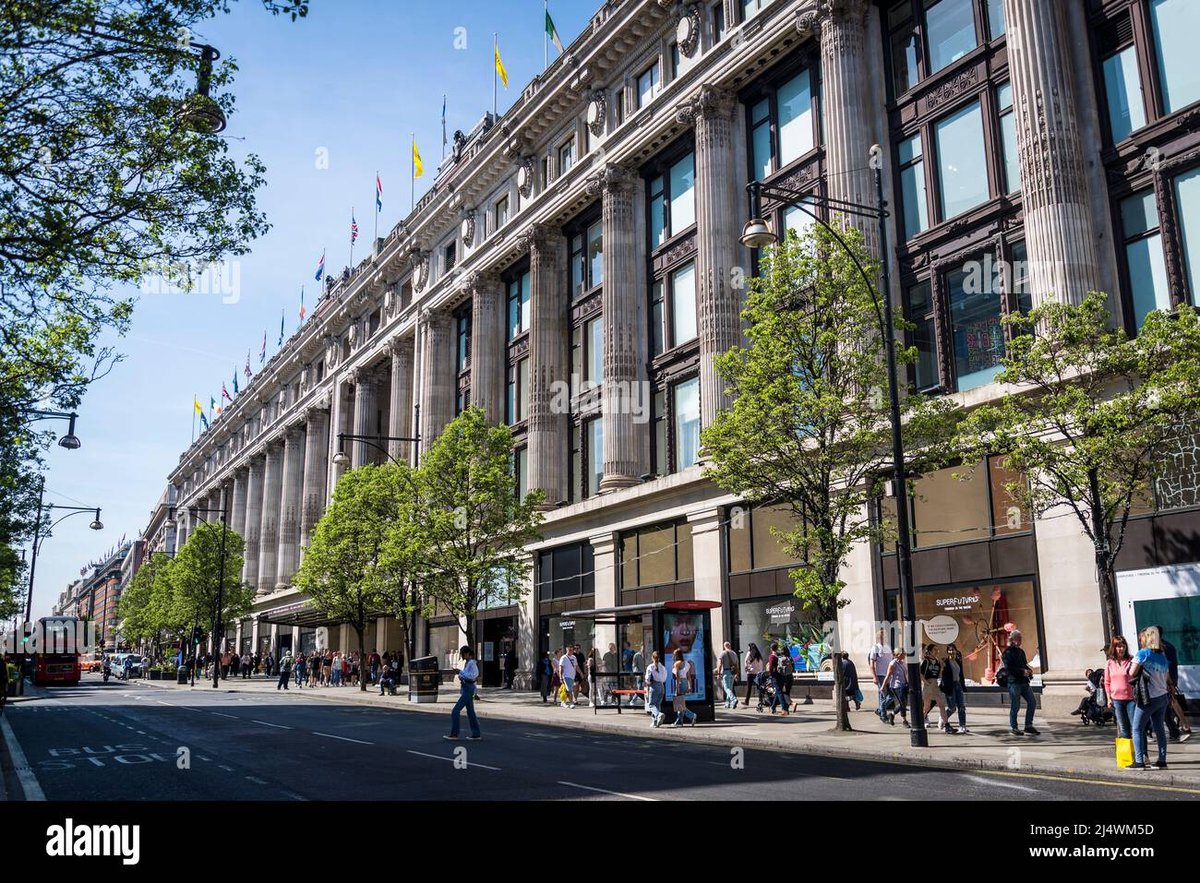
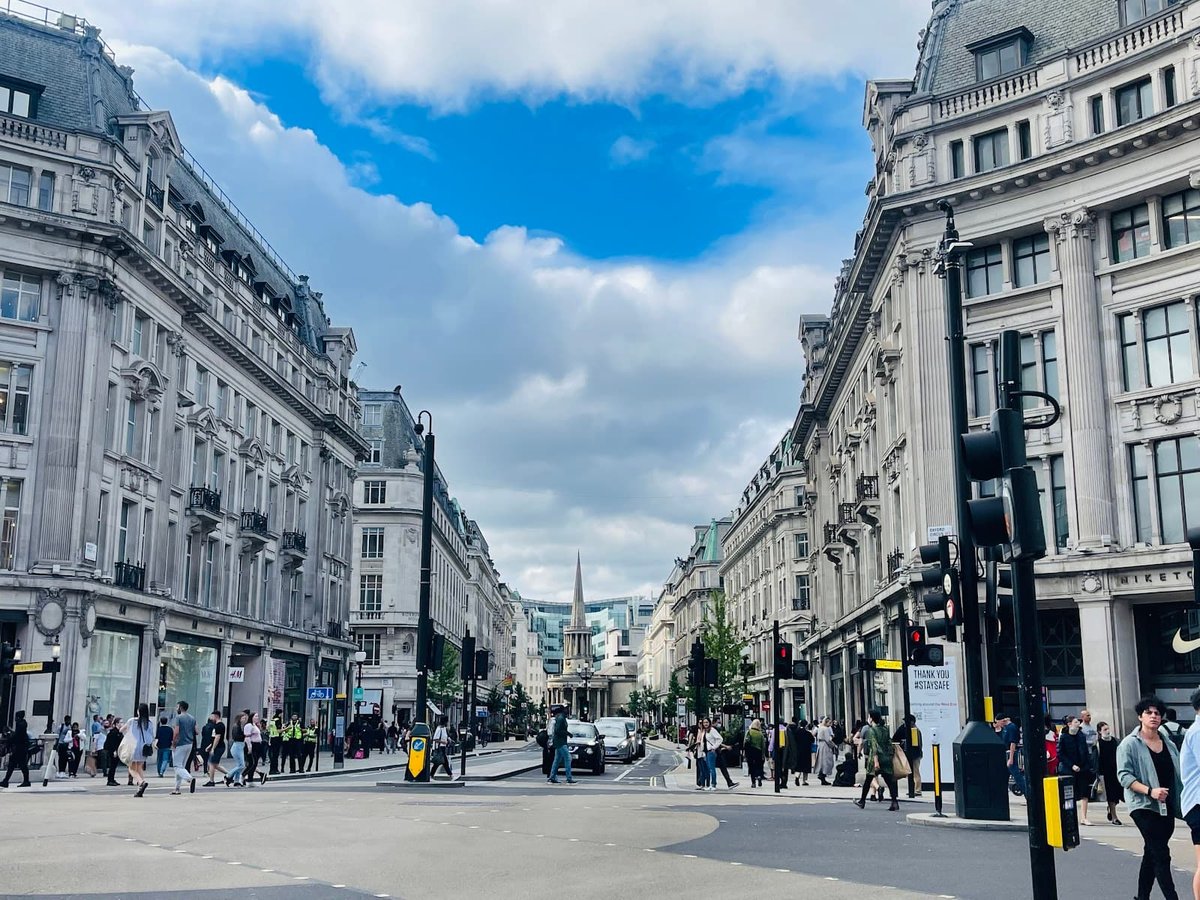
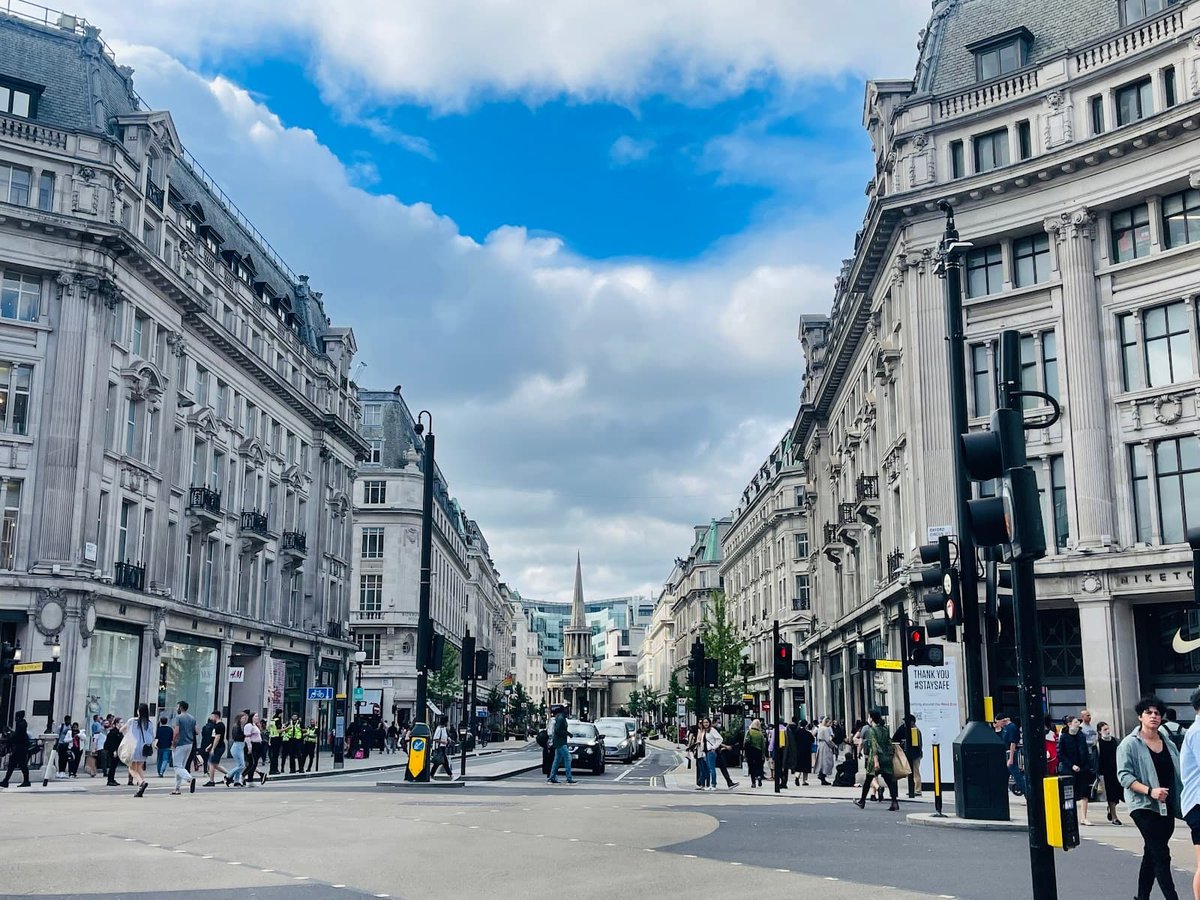
Oxford Street stands as one of the worlds most iconic retail corridors in central London, spanning 1.5 miles from Marble Arch to Tottenham Court Road, attracting approximately 200 million visitors annually in recent years, with footfall surging 45% during a September 2025 pedestrianisation trial that also boosted store sales. The areas market position has strengthened post-pandemic, with vacancy rates dropping to a historic low of 0.5% in Q1 2025, well below pre-pandemic levels of around 2-3%, reflecting robust demand from international brands.
Prime rents have risen sharply, with Oxford Street East seeing 33.3% year-on-year growth in Q4 2024 and overall West End prime rents up 19% in Q3 2025, averaging GBP 800-1,200 per sq ft, though turnover rents can mitigate upfront costs for high-volume tenants.
Tenant mix is dominated by fast fashion (H&M, Zara, Primark), department stores (Selfridges, John Lewis), beauty (Sephora, Boots), and luxury anchors, creating a diverse draw for mass-market and mid-tier retailers, supported by a 95%+ occupancy rate. Demographics skew towards young adults (18-34) at 60%, with 40% international tourists from Europe, Asia, and the US, plus local West End workers and students, driving impulse buys in apparel and accessories.
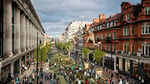
Leasing advantages include unparalleled visibility and global brand exposure, excellent accessibility via multiple Tube lines (Central, Bakerloo, Victoria at Oxford Circus and Bond Street stations) and Crossrail, plus ongoing public realm enhancements like wider pavements and reduced traffic. However, challenges encompass intense competition from nearby Regent Street and Bond Street for luxury segments, high operational costs including business rates up to GBP 500k annually for larger units, and occasional overcrowding impacting dwell time.
Market saturation in fast fashion categories poses risks, with some weaker performers exiting, while aging infrastructure in select buildings requires capex.
Overall, Oxford Street suits resilient, high-traffic retailers able to leverage its prestige despite elevated rents and competitive pressures, with pedestrianisation poised to enhance long-term viability amid a recovering UK retail sector projected at 2-3% rental growth in 2025.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 09:00 PM |
| Saturday | 10:00 AM — 09:00 PM |
| Sunday | 12:00 PM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Footfall and Accessibility
Oxford Street records annual footfall of around 200 million, with peaks during tourist seasons and events, enhanced by a 45% uplift from the 2025 pedestrianisation trial that improved pedestrian flow and safety. Accessibility is strong via six Tube stations, including Oxford Circus handling 100 million passengers yearly, and Elizabeth Line connections, though pre-trial traffic congestion reduced efficiency; post-trial metrics show increased dwell times of 20-30 minutes, benefiting conversion rates. Risks include seasonal dips in winter and potential overcrowding during sales, with competition from Westfield malls drawing suburban shoppers away. Data from Springboard and TfL reports confirm its status as Europes busiest high street, supporting sales densities of GBP 10,000-15,000 per sq ft for prime units.
Demographics and Tenant Mix
The visitor profile features 60% aged 18-34, 40% international tourists (top sources: US 15%, China 12%, France 10%), and 20% local professionals, per 2024-2025 New West End Company data, fostering strong demand for affordable fashion, cosmetics, and experiential retail. Tenant mix includes 45% apparel, 20% beauty/health, 15% food/beverage, and anchors like Selfridges (500,000 sq ft), creating synergy but saturation in fast fashion with 25+ similar outlets; weaker categories like electronics show 10% vacancy risk. Balanced mix supports cross-shopping, though luxury brands prefer adjacent Bond Street, limiting upscale opportunities here. Insights from Savills and CBRE highlight demographic shifts towards sustainable and digital-integrated stores for sustained performance.
Lease Terms and Market Risks
Prime rents average GBP 900 per sq ft in 2025, up 25-33% YoY, with leases typically 5-15 years including turnover clauses (10-20% above base) to share upside in high-volume locations, per Cluttons Q2 2025 report; incentives like 6-12 months rent-free apply for flagship commitments. Occupancy nears 99.5%, signaling tight supply but high entry barriers for smaller retailers due to costs exceeding GBP 1 million setup. Risks include economic sensitivity to tourism fluctuations (down 5% in off-peak), intense competition from 50+ nearby high streets, and regulatory changes like business rates reform potentially adding 2-5% costs. Balanced view: strong for established chains, cautious for independents amid 2.5% projected rental growth and low vacancy stabilizing at 1-2%.
Building Details
Detailed Market Analytics
City Snapshot
London
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in London
Discover more shopping centers in London.

Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
London
Comprehensive market intelligence for retail expansion in this city