Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
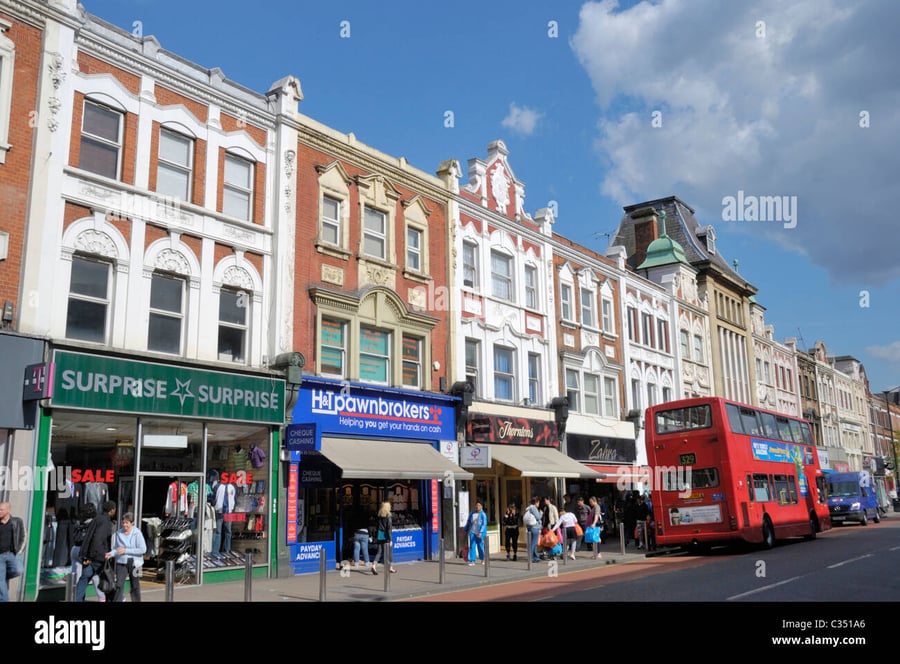
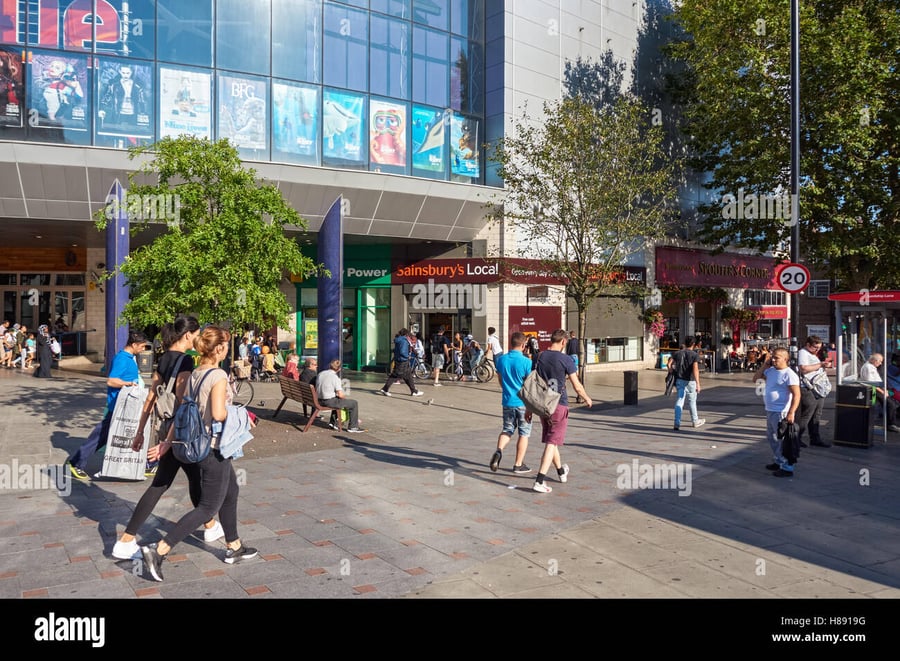
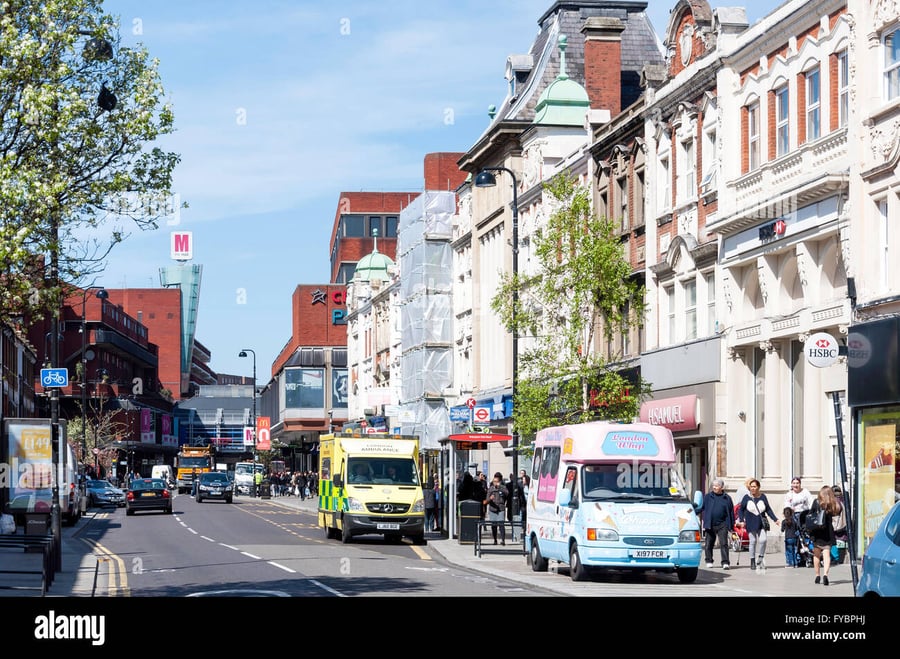
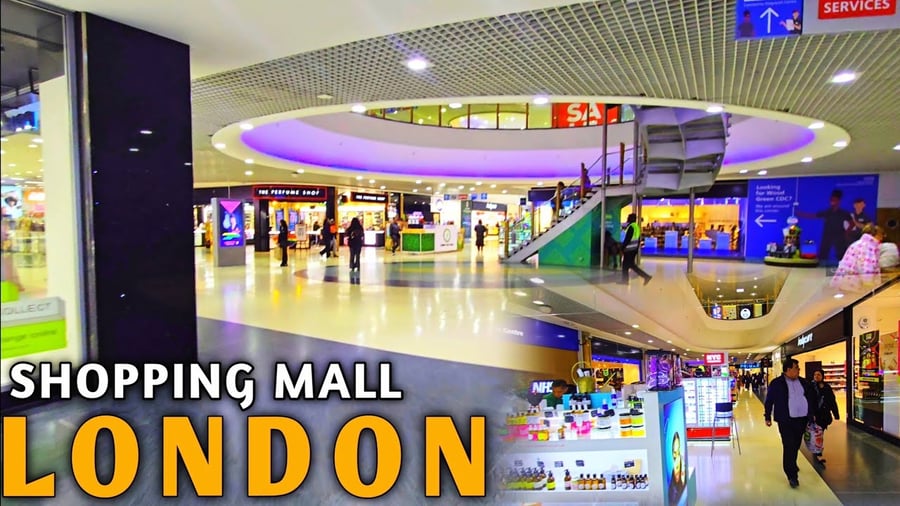
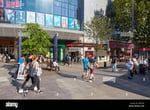
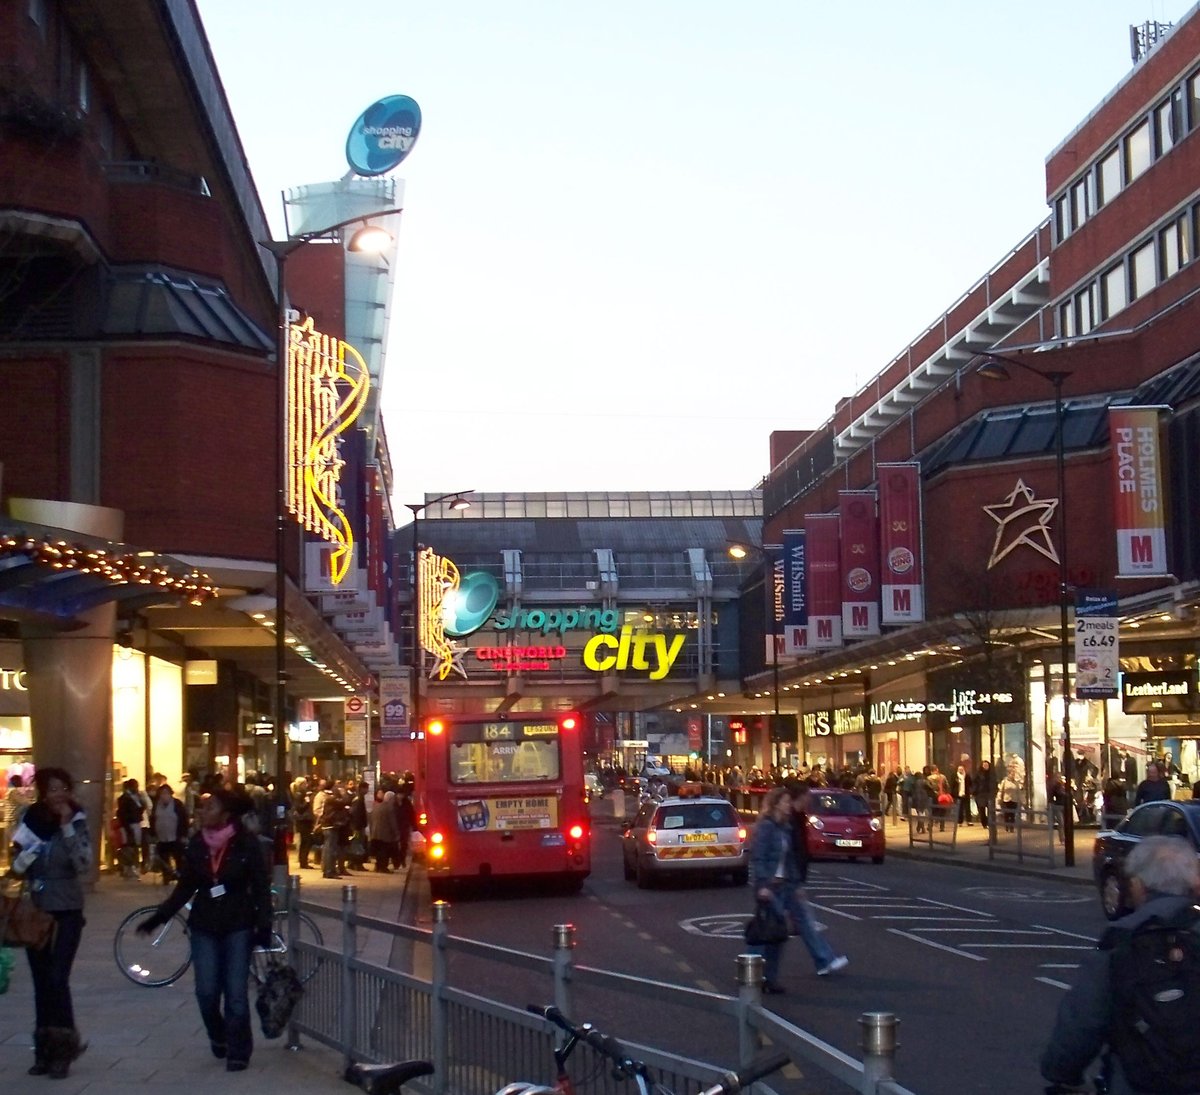
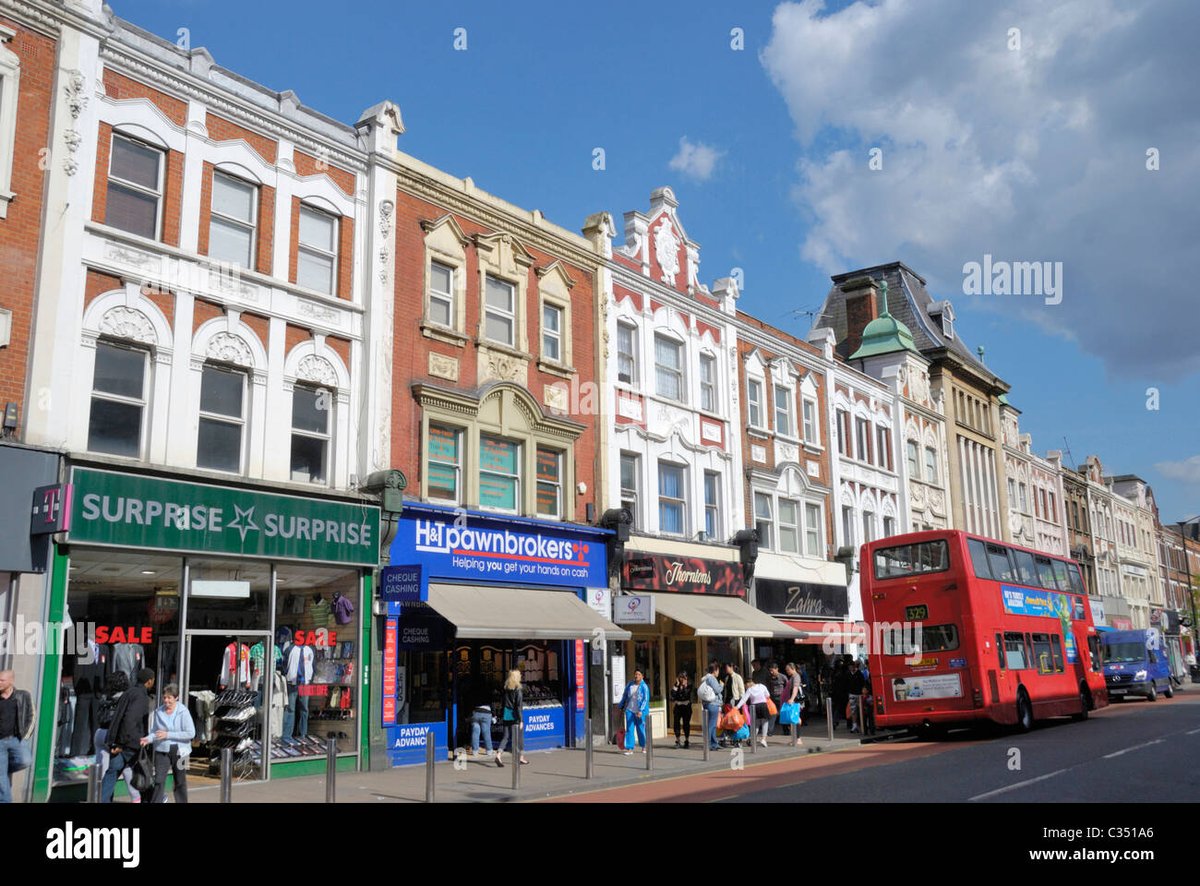
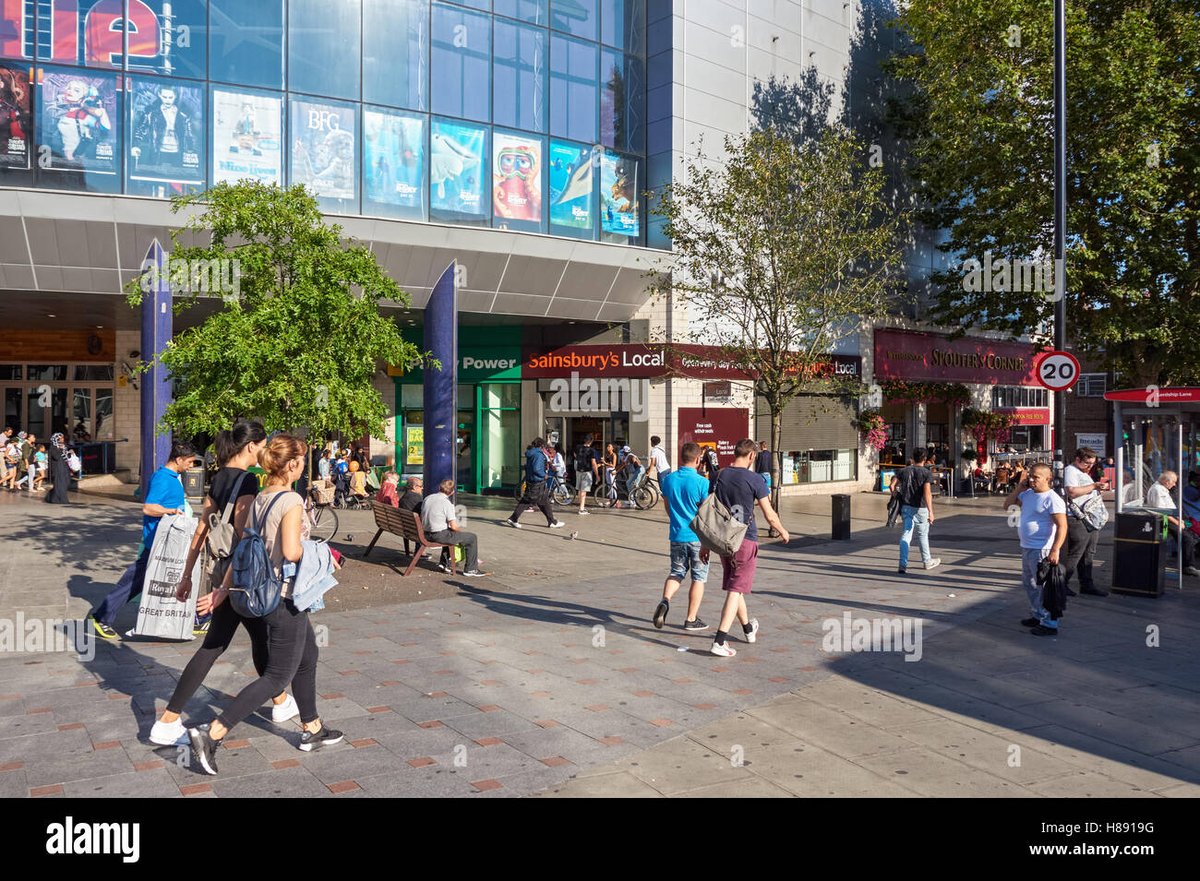
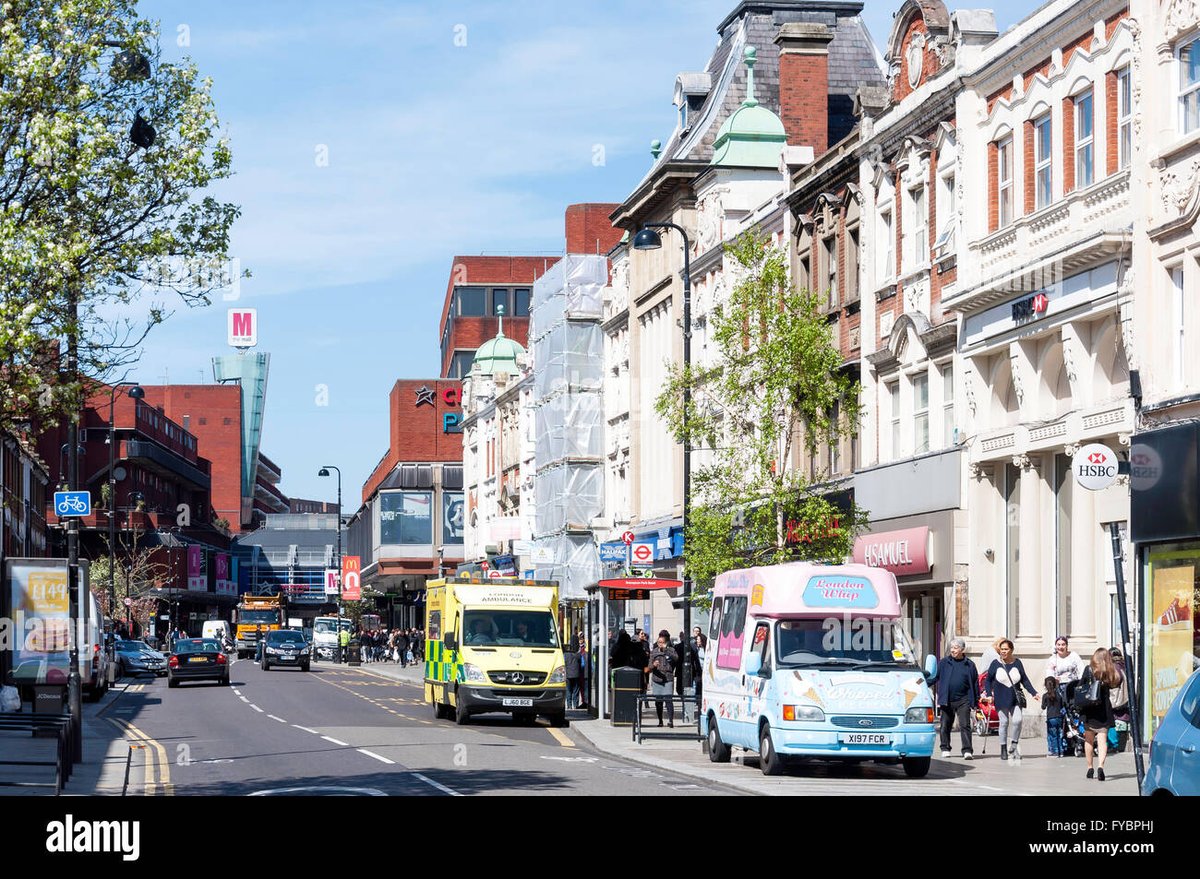
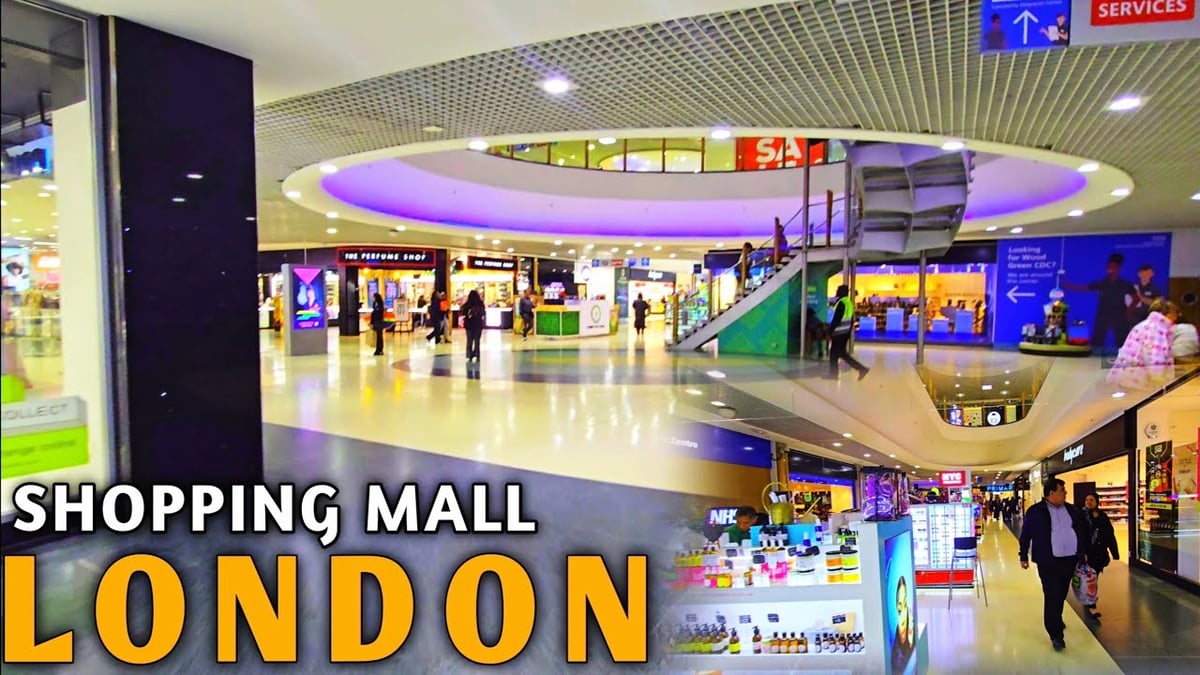
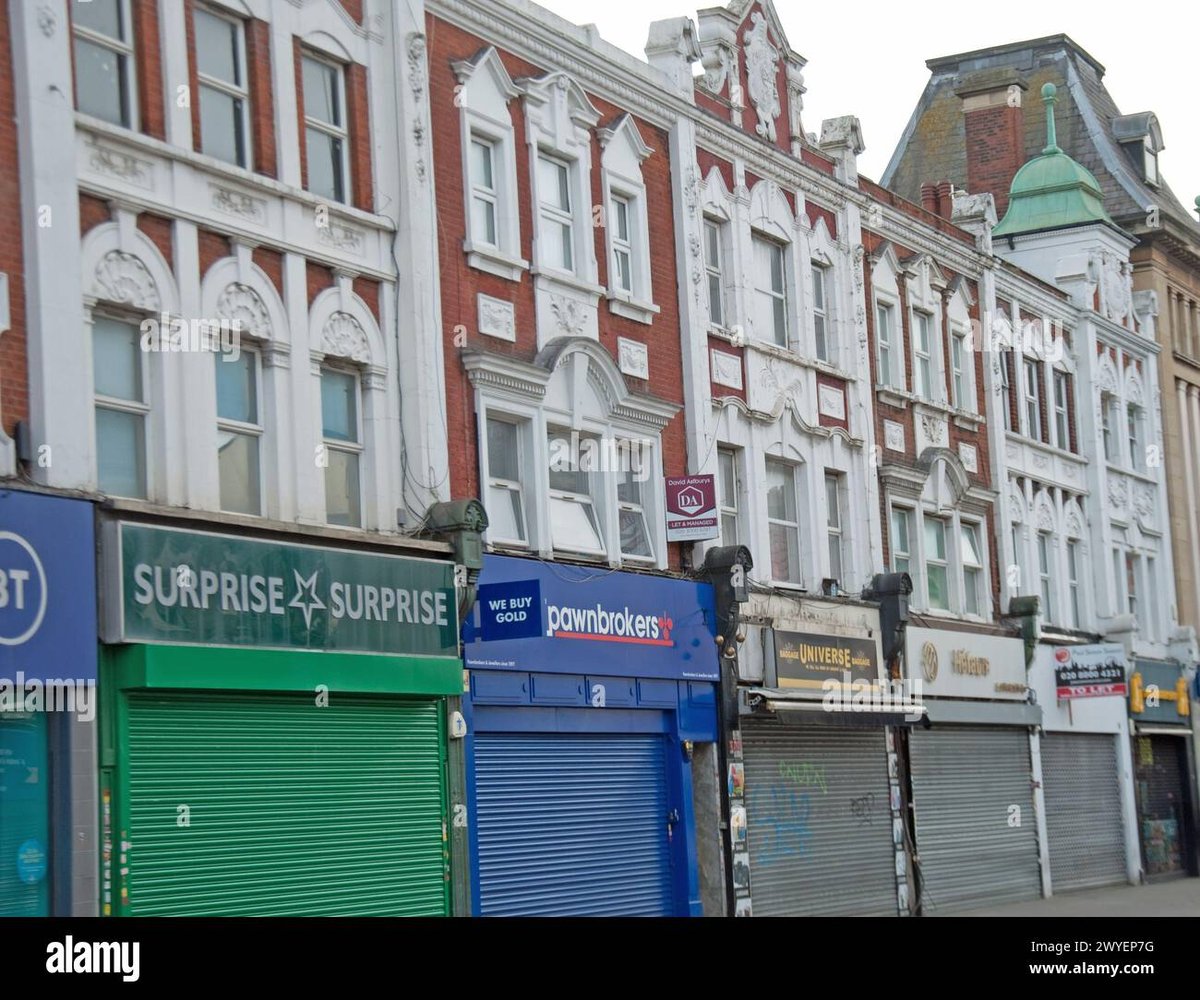
Wood Green Shopping City, also known as The Mall Wood Green, is a 656,000 sq ft regional shopping centre located in the heart of Wood Green, north London, straddling the High Road (A105). Opened in 1981 and extensively refurbished in recent years, it features over 100 retail units across two levels, linked by bridges, with the road running through it for direct street access. Key anchors include Primark (largest store at around 40,000 sq ft), Sports Direct, and a 12-screen Vue Cinema, alongside a 30,000 sq ft indoor Market Hall with independent traders.
Tenant mix comprises fashion (40%), health and beauty (15%), food and beverage (20%), services (15%), and leisure (10%), attracting a diverse, multi-ethnic catchment from Haringey borough, characterized by young families and lower-to-middle income households (average income £32,000, IMD rank 5th most deprived in London). Annual footfall stands at approximately 12-14 million visitors, supported by excellent accessibility via Wood Green Underground (Piccadilly line), Overground, and bus interchanges, drawing 70% public transport users.
Occupancy rate hovers around 92-95% as of 2024 data from Capital & Regional reports, with passing rents averaging £250-£350 per sq ft in prime units, reflecting suburban London stability amid regeneration efforts under Haringey Council plans.
Leasing advantages include flexible unit sizes (500-50,000 sq ft), turnover rents tied to performance, and proximity to residential growth (10,000 new homes planned by 2030), boosting local demand. However, challenges persist from high street saturation, e-commerce pressures, and competition from larger destinations like Brent Cross (15 miles away) and Westfield Stratford (5 miles), potentially capping sales at £350-400 per sq ft.
Operational quality is solid with modern facilities, but aging infrastructure in adjacent areas and occasional access disruptions from traffic pose risks.
Market position as a convenience-led community hub suits value-oriented retailers, though weak categories like department stores (post-Debenhams collapse) highlight vulnerabilities in non-essential retail amid 5-7% annual vacancy creep in outer London per Savills 2025 report.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 07:00 PM |
| Tuesday | 09:00 AM — 07:00 PM |
| Wednesday | 09:00 AM — 07:00 PM |
| Thursday | 09:00 AM — 07:00 PM |
| Friday | 09:00 AM — 07:00 PM |
| Saturday | 09:00 AM — 07:00 PM |
| Sunday | 11:00 AM — 05:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment
Wood Green serves a primary catchment of 250,000 within 2 miles, predominantly diverse ethnic groups (60% BAME, including Turkish, African, and Caribbean communities), with 35% under 30 years old and high family density (25% households with children). Secondary catchment extends to 1 million across north London, supported by strong public transport links generating 80,000 daily passengers at Wood Green station. Income levels are modest (median £28,000 household), favoring value fashion, discount groceries, and affordable leisure, but limit luxury positioning. Regeneration initiatives, including 5,000 new jobs projected by 2028, could enhance spending power, though current deprivation (top 10% nationally) risks lower conversion rates (around 25% vs. 35% London average). Positive for ethnic food/beauty tenants, but requires targeted marketing to counter low disposable income impacts on discretionary spend.
Competition and Market Saturation
Faces moderate competition from nearby high streets like Green Lanes (independent focus) and larger malls such as Brent Cross (premium, 18M footfall) and Westfield Stratford City (42M visitors, upscale mix). Local market saturation in fast fashion and electronics (15% oversupply per Haringey 2024 study) pressures margins, with online shifts reducing physical visits by 10-15% YoY. Strengths include unique indoor market for independents and cinema-driven dwell time (average 2 hours), differentiating from pure high street rivals. Risks involve potential tenant churn in weak categories like books/media (vacancy up 20%), exacerbated by economic slowdowns; however, transport hub status sustains baseline traffic, positioning it resiliently against pure e-commerce threats in a post-pandemic landscape.
Accessibility and Operational Risks
Excellent connectivity via Piccadilly line (Zone 3, 20 mins to central London), national rail, and 50+ bus routes, with 1,200 parking spaces (though utilization peaks at 85% weekends). Pedestrian footfall benefits from adjacent residential density (population growth 8% since 2020), but High Road traffic congestion and occasional tube disruptions (e.g., 2024 strikes) hinder reliability. Infrastructure shows signs of age in non-mall areas, with flood risks from River Moselle noted in planning docs, potentially raising insurance costs. Operational quality includes clean, secure environment (CCTV coverage 95%), but petty crime rates (theft index 1.5x London average) around transport nodes may deter evening trade. Leasing perks like inclusive service charges (£15-20/sq ft) offset some risks, aiding smaller retailers in a high-access but volatile suburban setting.
Building Details
Detailed Market Analytics
City Snapshot
London
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in London
Discover more shopping centers in London.

Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
London
Comprehensive market intelligence for retail expansion in this city