
Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
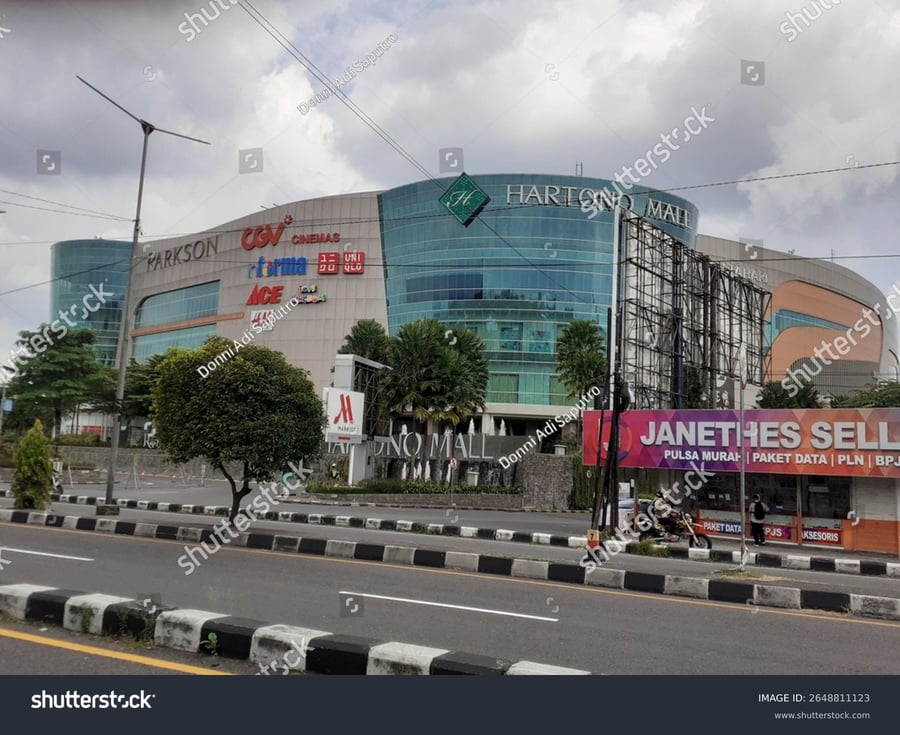
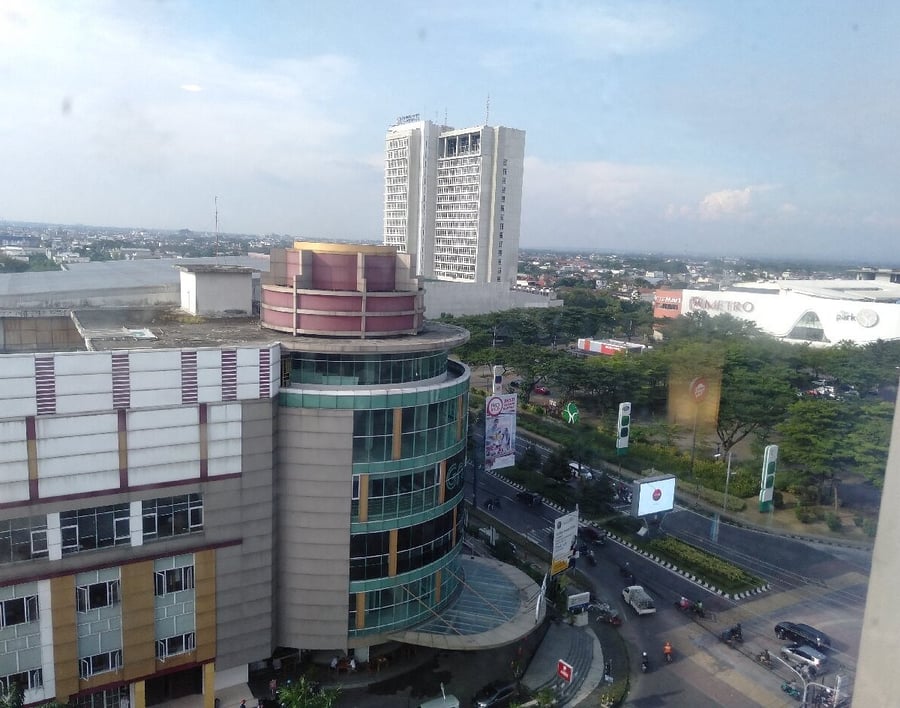
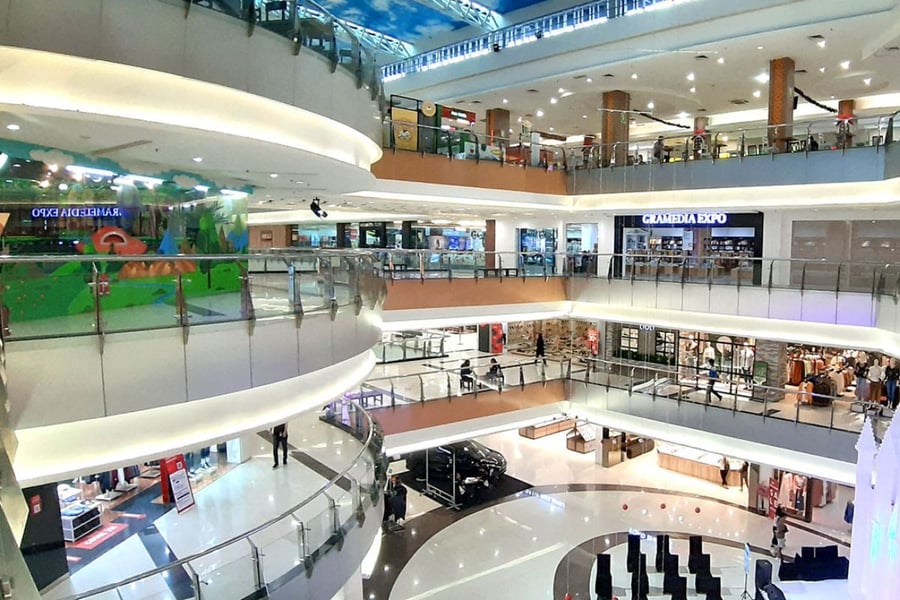
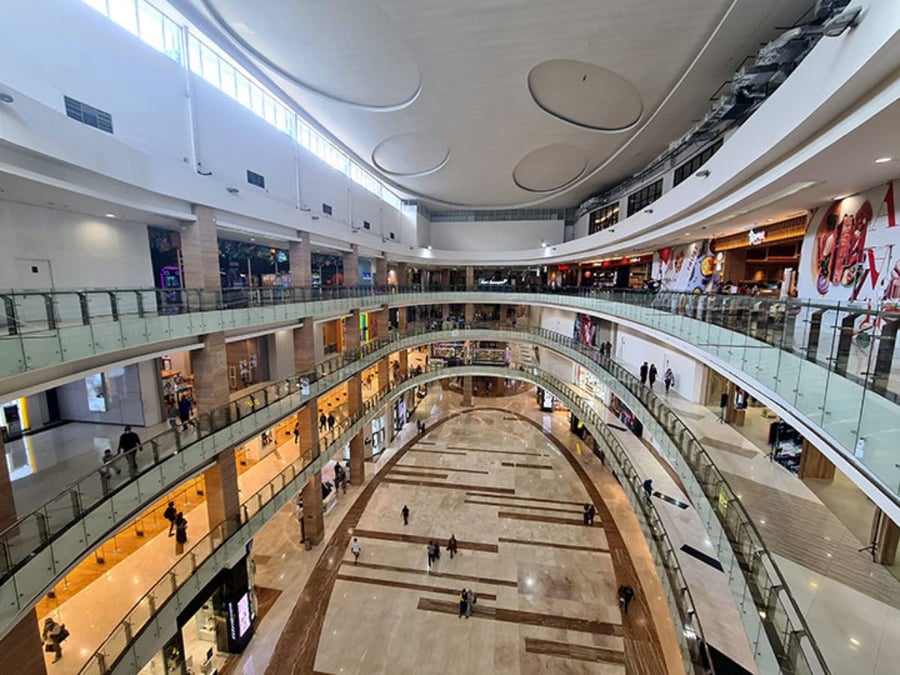
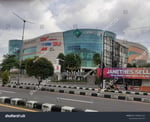
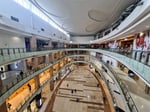
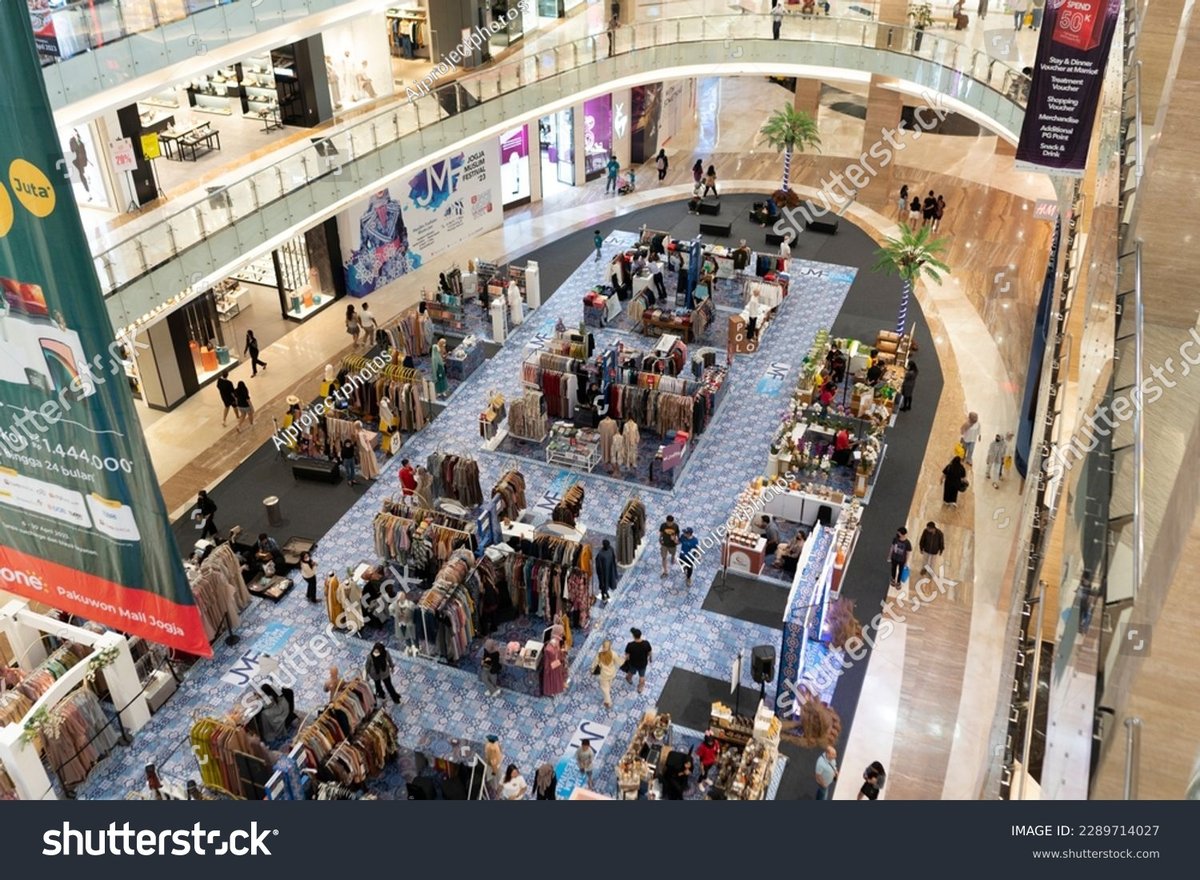
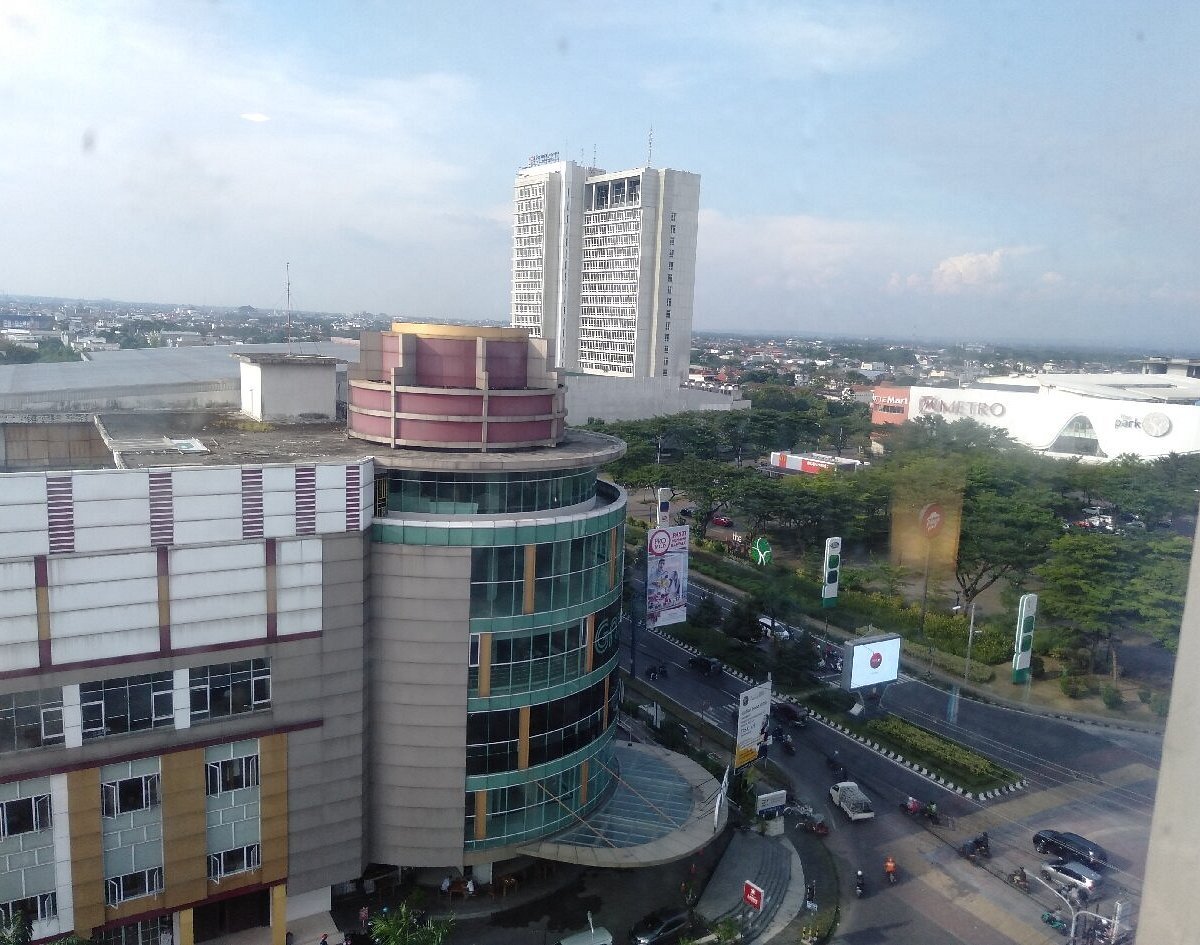
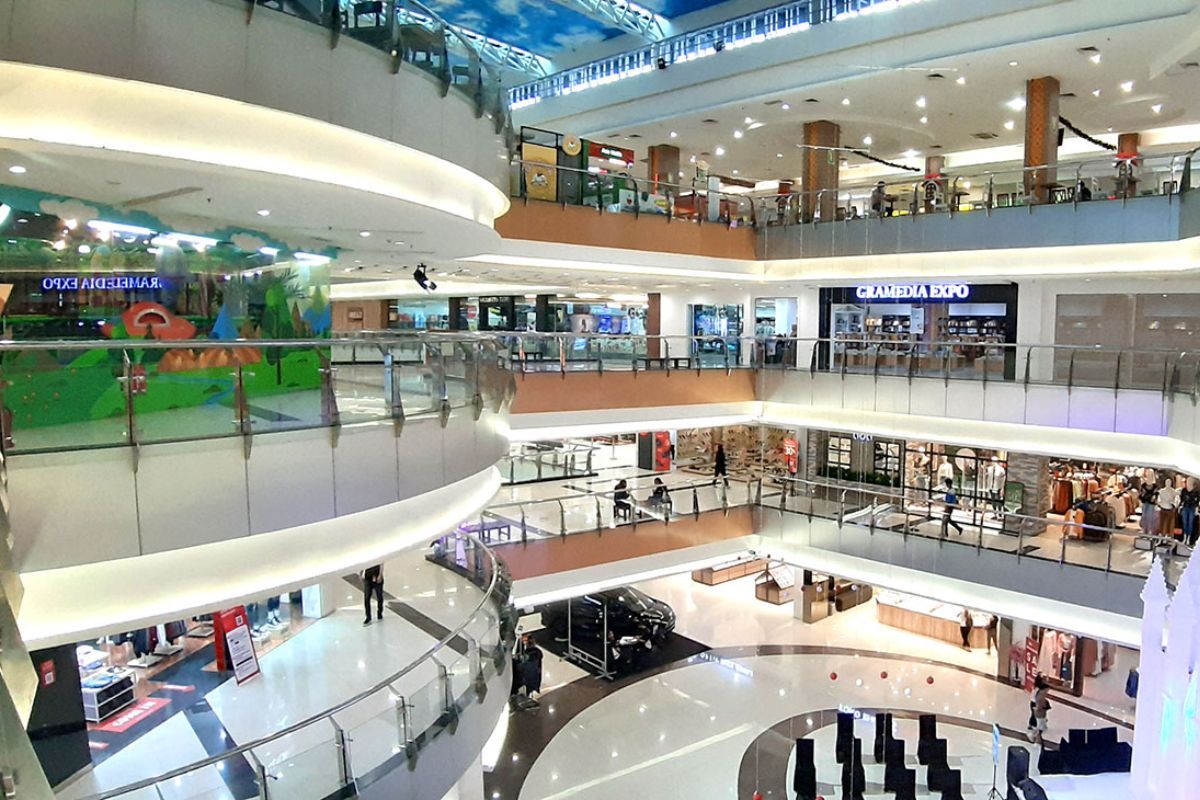
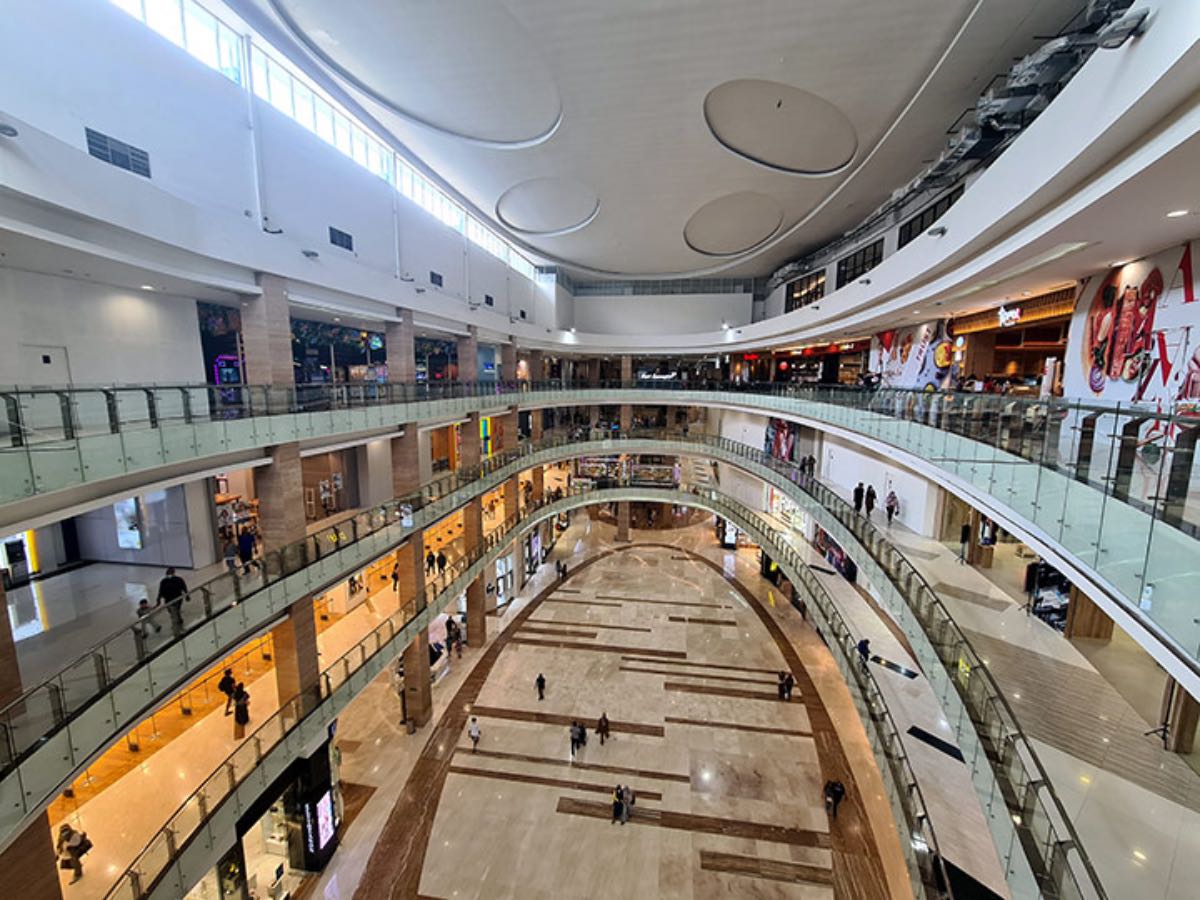
Hartono Mall Solo, situated in Grogol, Sukoharjo Regency, adjacent to Surakarta (Solo) in Central Java, Indonesia, opened in 2012 as the inaugural shopping center in the emerging Solo Baru commercial district. Covering 33,000 square meters across five retail levels, it was acquired by Pakuwon Jati Tbk in 2020 for part of a IDR 1.36 trillion deal and rebranded as Pakuwon Mall Solo Baru, enhancing its management and appeal.
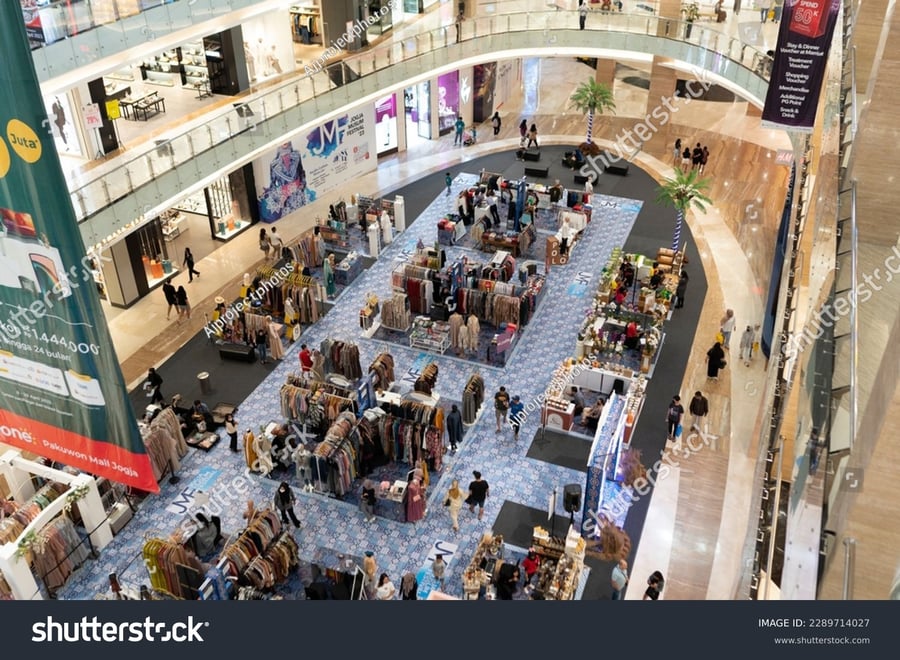
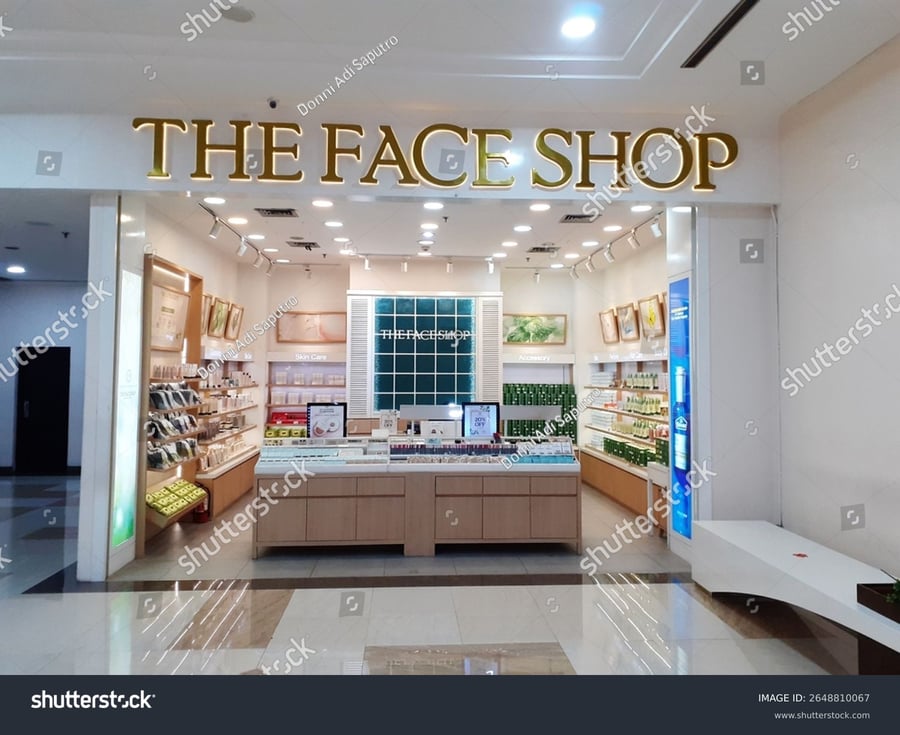
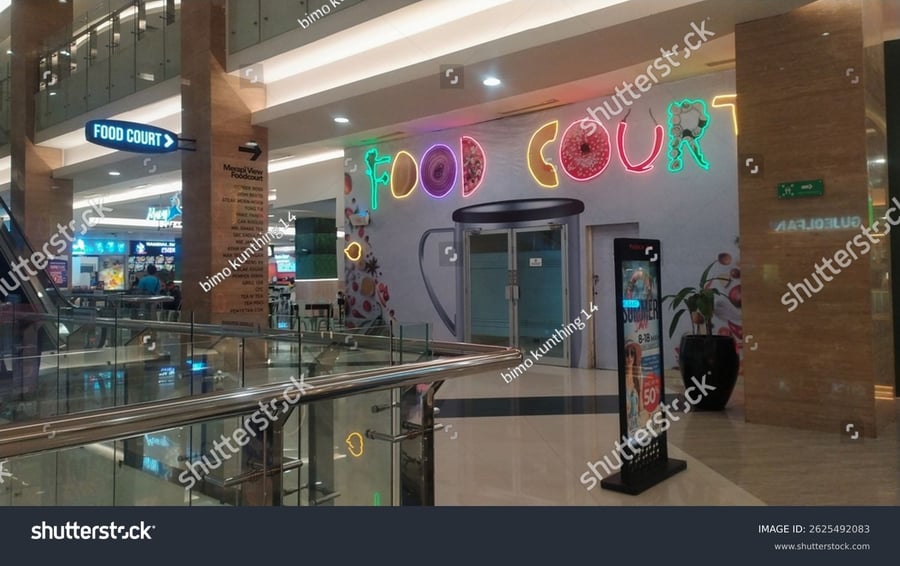
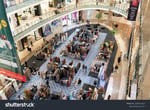
The tenant mix comprises anchor retailers such as Matahari Department Store on upper ground and first floors, Hypermart on lower ground, fashion outlets like Uniqlo, home goods from Informa, and electronics via Azko Nobel. Entertainment facilities include Funworld and Dream Land on lower levels, while food and beverage options feature international chains like Sushi Tei, RamenYa, and Kimukatsu, alongside local eateries, fostering a family-oriented environment.
In the regional retail landscape, Central Java's malls maintain occupancy rates of 80-90%, with Pakuwon's properties averaging 94%, indicating solid performance amid post-pandemic recovery. The site targets middle-class demographics in Sukoharjo, a regency with 941,650 residents and a minimum wage of IDR 2.36 million, supporting value-driven shopping.
Accessibility relies on Jalan Solo Baru, connecting to Surakarta's urban core, though public transport options are moderate.
Leasing advantages encompass competitive rents estimated at IDR 500,000-800,000 per square meter annually, below Jakarta's IDR 1-2 million, with flexible terms potentially including percentage rents tied to sales. However, drawbacks include proximity to rival The Park Mall, which draws premium footfall, and competition from traditional markets like Klewer for budget segments. Market saturation in apparel and F&B categories, combined with occasional infrastructure strains in the area, could impact performance.
Footfall metrics, while not publicly detailed, benefit from local events and weekend crowds, estimated at moderate levels for a tier-2 mall, with opportunities in underserved categories like health and wellness.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile and Footfall
Sukoharjo Regency, encompassing the mall's location, reports a 2024 population of 941,650 with a density of 1,907 persons per square kilometer, predominantly middle-income households reliant on manufacturing and agriculture. The regional minimum wage stands at IDR 2,359,488, fostering demand for affordable retail. Footfall draws from nearby Surakarta's 550,000 residents, peaking on weekends and holidays, though exact figures are unavailable; similar regional malls see 5,000-10,000 daily visitors. Strengths include growing urbanization in Solo Baru, but challenges arise from economic disparities, limiting high-end spending and exposing to downturns in local industries.
Tenant Mix and Competition
The tenant composition balances essentials with leisure: anchors like Hypermart and Matahari occupy prime spaces, complemented by fashion (Uniqlo), home (Informa), and entertainment (Funworld). F&B diversity includes Asian chains (Sushi Tei, RamenYa) and casual dining, promoting dwell time. Occupancy aligns with Pakuwon's 94% group average, suggesting stability. Competition intensifies from adjacent The Park Mall, targeting upscale shoppers, and traditional outlets like Pasar Klewer for bargains, potentially fragmenting traffic. Weaknesses in niche categories like luxury goods highlight risks of cannibalization, yet the mix supports cross-traffic for mid-tier retailers.
Lease Terms and Operational Risks
Rent levels in Solo Baru malls range from IDR 500,000 to 800,000 per square meter yearly, with base plus turnover structures common, aiding cash flow in variable markets. Operational quality has uplifted under Pakuwon management, featuring modern amenities and events to boost engagement. Accessibility via main roads is adequate, but parking constraints during peaks and reliance on private vehicles pose issues. Risks include 2012-era infrastructure showing age, market saturation in core categories, and sensitivity to Central Java's retail slowdowns, where vacancy can rise above 20% in weaker periods. Balanced evaluation recommends due diligence on renewal clauses and footfall guarantees.
Building Details
Detailed Market Analytics
City Snapshot
Surakarta
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Surakarta
Discover more shopping centers in Surakarta.
Popular in Indonesia
Top retail destinations across Indonesia.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Surakarta
Comprehensive market intelligence for retail expansion in this city