Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
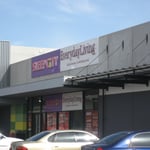
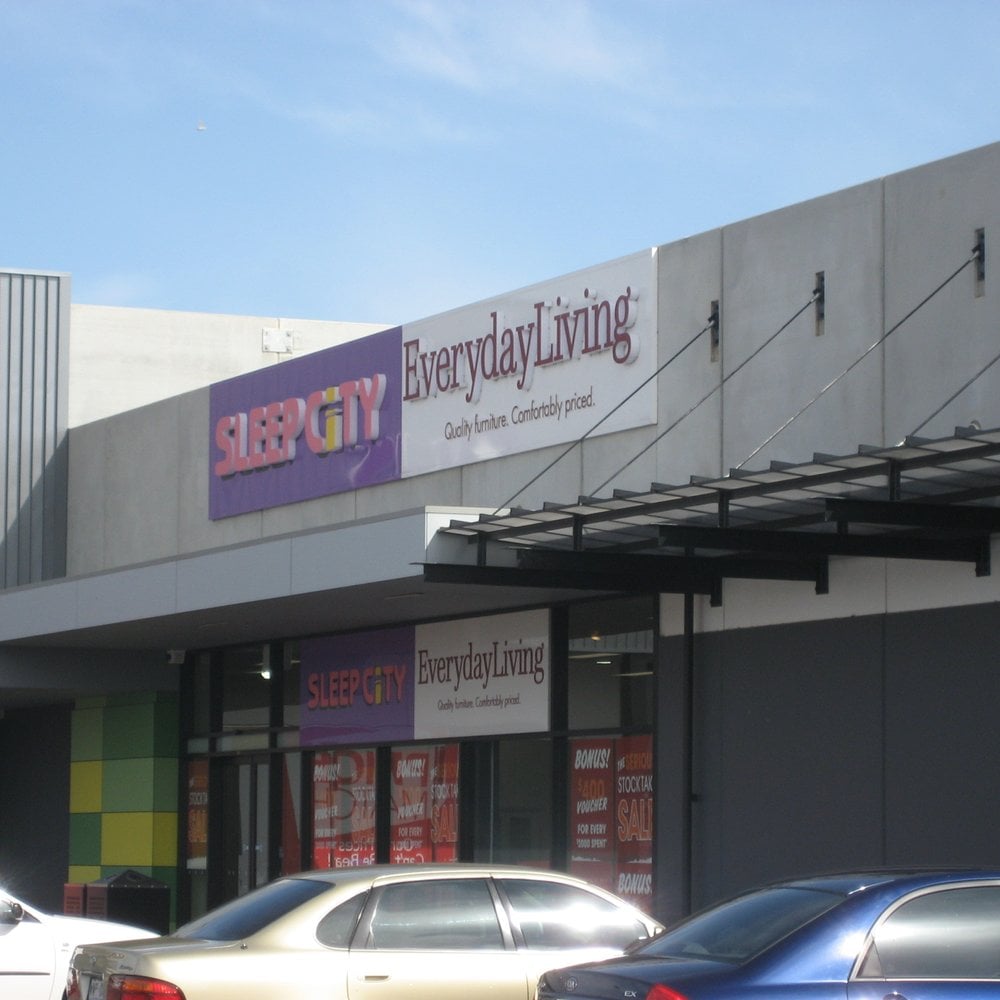
Gepps Cross Shopping Centre, situated at 750 Main North Road in the northern suburb of Gepps Cross, Adelaide, operates as a major bulky goods and homemaker retail complex covering approximately 63,000 square meters of gross leasable area. Positioned 12 kilometers north of the Adelaide CBD along the Northern Growth Corridor, it enjoys strong accessibility via arterial roads, proximity to the Gepps Cross interchange, and public transport links including bus routes.
The tenant mix emphasizes large-format stores specializing in home improvement, furniture, electronics, and outdoor products, with key anchors such as Harvey Norman (SAs largest outlet), JB Hi-Fi Home, The Good Guys, Super Amart, Baby Bunting, Toyworld, Amart Furniture, Spotlight, BCF, and Fantastic Furniture, comprising over 30 specialty retailers. This configuration caters to family-oriented shoppers in the Enfield-Gepps Cross area, characterized by a demographic profile of median age 36, household size 2.5, and median income around $85,000, with population growth of 2% annually per ABS data.
Occupancy stands at approximately 95%, aligned with Adelaides suburban retail vacancy rate of 4.2% in Q3 2025 per JLL reports, bolstered by 4.1% year-on-year household spending growth. Leasing opportunities benefit from competitive net rents of $220-320 per sqm, turnover rents, and marketing synergies from anchors, though the centres focus on destination bulky goods may result in lower footfall of 1.2-1.8 million visitors annually compared to regional malls.
Operational quality includes modern warehousing-style infrastructure built in 2007 with recent upgrades, but challenges encompass e-commerce pressures on physical retail and occasional traffic congestion at the junction.
Overall, it holds a solid market position as South Australias largest homemaker centre, with potential for stable performance amid regional expansion.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 05:30 PM |
| Tuesday | 09:00 AM — 05:30 PM |
| Wednesday | 09:00 AM — 05:30 PM |
| Thursday | 09:00 AM — 09:00 PM |
| Friday | 09:00 AM — 05:30 PM |
| Saturday | 09:00 AM — 05:00 PM |
| Sunday | 11:00 AM — 05:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Accessibility
The surrounding Gepps Cross and Enfield suburbs feature a diverse, working-class demographic with 25% families with children under 15, 15% aged 65+, and unemployment at 6.5%, per 2021 Census updates. Median household income of $85,000 supports spending on home goods, but lower affluence than southern suburbs may cap premium sales. Accessibility is a strength with 50,000 daily vehicles on Main North Road and O-Bahn bus corridor nearby, yet peak-hour congestion reduces convenience. Public transport serves 70% of tenants via Adelaide Metro routes, enhancing draw from a 20km radius catchment of 150,000 residents. Footfall averages 3,500-5,000 daily, peaking weekends, but lags traditional malls due to format; parking for 2,500 cars mitigates this. Risks include reliance on car-dependent shoppers amid rising fuel costs.
Competition and Tenant Mix
Competition includes nearby Regency Plaza and Northpark Shopping Centre for general retail, plus online platforms like IKEA and Amazon eroding 20% of bulky goods market share per Retail Doctor reports. Gepps Xs tenant mix is 70% home/furniture, 20% electronics, 10% services, providing synergy but vulnerability to category downturns; weak apparel or food presence limits cross-shopping. Market saturation in northern Adelaide is moderate, with 15% growth in homemaker space since 2020, but strong anchors ensure 80% tenant retention. Operational challenges involve aging signage and shared loading bays causing delays, though centre management invests $500,000 annually in maintenance. Overall, balanced mix supports 5-7% sales growth, tempered by 10% e-commerce shift.
Lease Terms and Risks
Net lease terms offer 5-10 year options with 3-5% annual escalations, incentives like 6 months rent-free for 1,000+ sqm commitments, and percentage rents on turnover exceeding $5,000/sqm. Asking rents range $250-300/sqm for prime frontage, below CBD averages but above big-box norms, reflecting 95% occupancy and low 2% churn. Operational quality is good with 24/7 security, energy-efficient HVAC, but infrastructure from 2007 shows wear in some bays, requiring $10-15/sqm capex. Risks include economic sensitivity in manufacturing-heavy suburbs (10% job exposure), potential oversupply from corridor developments, and access issues from roadworks. Balanced view: Attractive for durable goods retailers, but monitor online trends and ensure robust escape clauses for market shifts.
Building Details
Detailed Market Analytics
City Snapshot
Adelaide, SA
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Adelaide
Discover more shopping centers in Adelaide.


Popular in Australia
Top retail destinations across Australia.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Adelaide, SA
Comprehensive market intelligence for retail expansion in this city