

Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
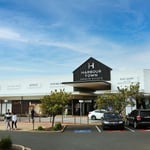
District Outlet Centre, commonly referred to as DFO Adelaide, is a purpose-built undercover outlet shopping centre located at 22-24 Nobby Buckley Drive, Parafield, in northern Adelaide, South Australia. Opened in July 2023, it spans a gross leasable area of approximately 14,000 square meters with 54 tenancies focused on discounted retail. The tenant mix emphasizes value-oriented fashion, sportswear, accessories, and lifestyle brands, including anchors like Cotton On Mega, Puma, Hype DC, Forever New, Supre, Ally Fashion, Strandbags, and Kaisercraft, alongside categories such as kids and family, beauty, home and electronics, and sports and leisure.
Positioned on the high-exposure Main North Road, it serves a growing northern metro catchment of over 995,000 residents, with projected population increases of 113,000 by 2046, driven by suburban expansion and diverse demographics including families and middle-income households.
Accessibility includes a 30-minute drive from the Adelaide CBD, nearby bus stops (Stop 40 on Main North Road), and nearly 600 free on-site parking spaces with accessible bays. In the broader Adelaide retail market, where sales grew 3.6% year-over-year as of mid-2025 and large format retail yields stand at 6.13%, this centre offers leasing advantages through outlet-style rents typically 20-40% below prime mall levels, attracting budget-conscious retailers amid stable occupancy trends in suburban assets.
However, as one of only 19 national outlet centres, it faces unique risks from receivership proceedings initiated in October 2025 due to developer financial issues, potentially impacting operational stability. Footfall benefits from its status as Adelaides only undercover outlet, drawing regional shoppers, though specific metrics are not publicly detailed; initial opening saw strong reception with over 70% pre-leased space.
Operational quality includes extended Thursday hours to 9 PM and daily openings, supporting consistent trade in a market with low retail vacancy rates around 9-11% in key areas. Leasing opportunities highlight low entry costs and growth potential in a resilient SA economy, balanced against northern suburbs competition and infrastructure reliance on road access.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 05:30 PM |
| Tuesday | 09:00 AM — 05:30 PM |
| Wednesday | 09:00 AM — 05:30 PM |
| Thursday | 09:00 AM — 09:00 PM |
| Friday | 09:00 AM — 05:30 PM |
| Saturday | 09:00 AM — 05:00 PM |
| Sunday | 10:00 AM — 05:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment Area
The centre serves northern Adelaides expansive catchment of 995,000 residents across suburbs like Parafield, Elizabeth, and Mawson Lakes, characterized by diverse, middle to lower-income families with a median household income around AUD 80,000-100,000. Population growth is robust, with forecasts adding 113,000 people by 2046, fueled by affordable housing and migration, supporting demand for value retail. Age demographics skew towards families (25-44 years old comprising 35% of the area), aligning with the centres youth-oriented tenant mix in fashion and sports. However, economic pressures in outer suburbs may limit discretionary spending, with local retail expenditure projected to rise 3.8% annually to AUD 28.2 billion by 2041, per market reports.
Competition and Market Factors
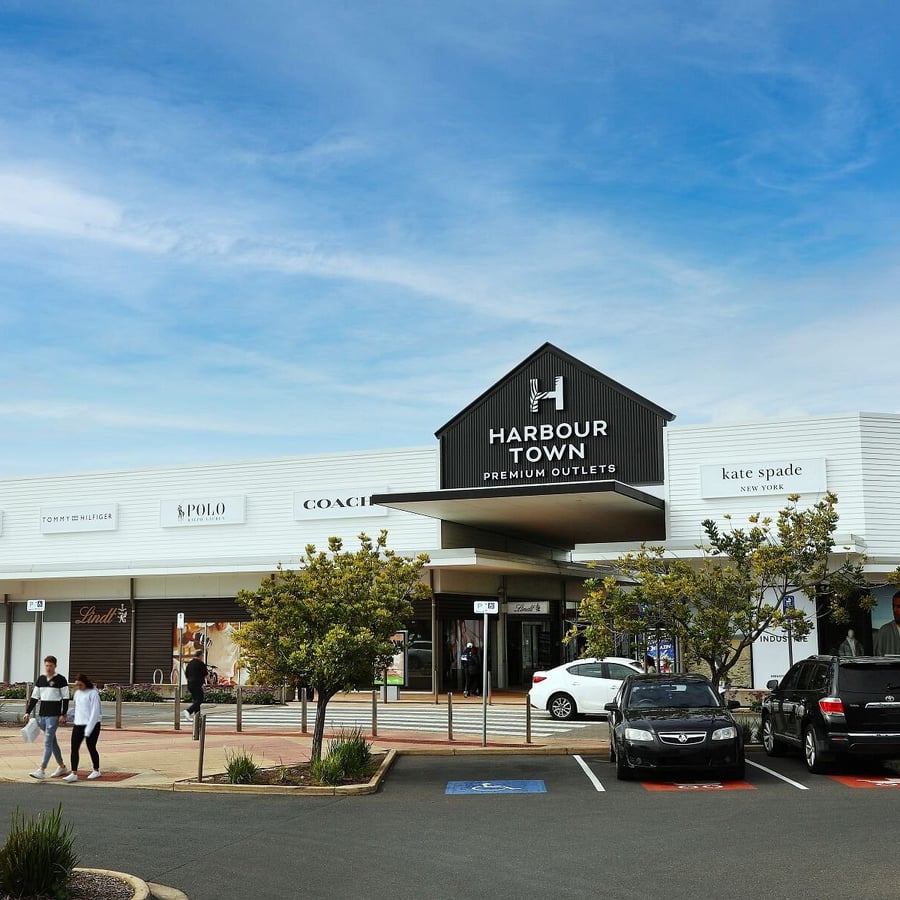
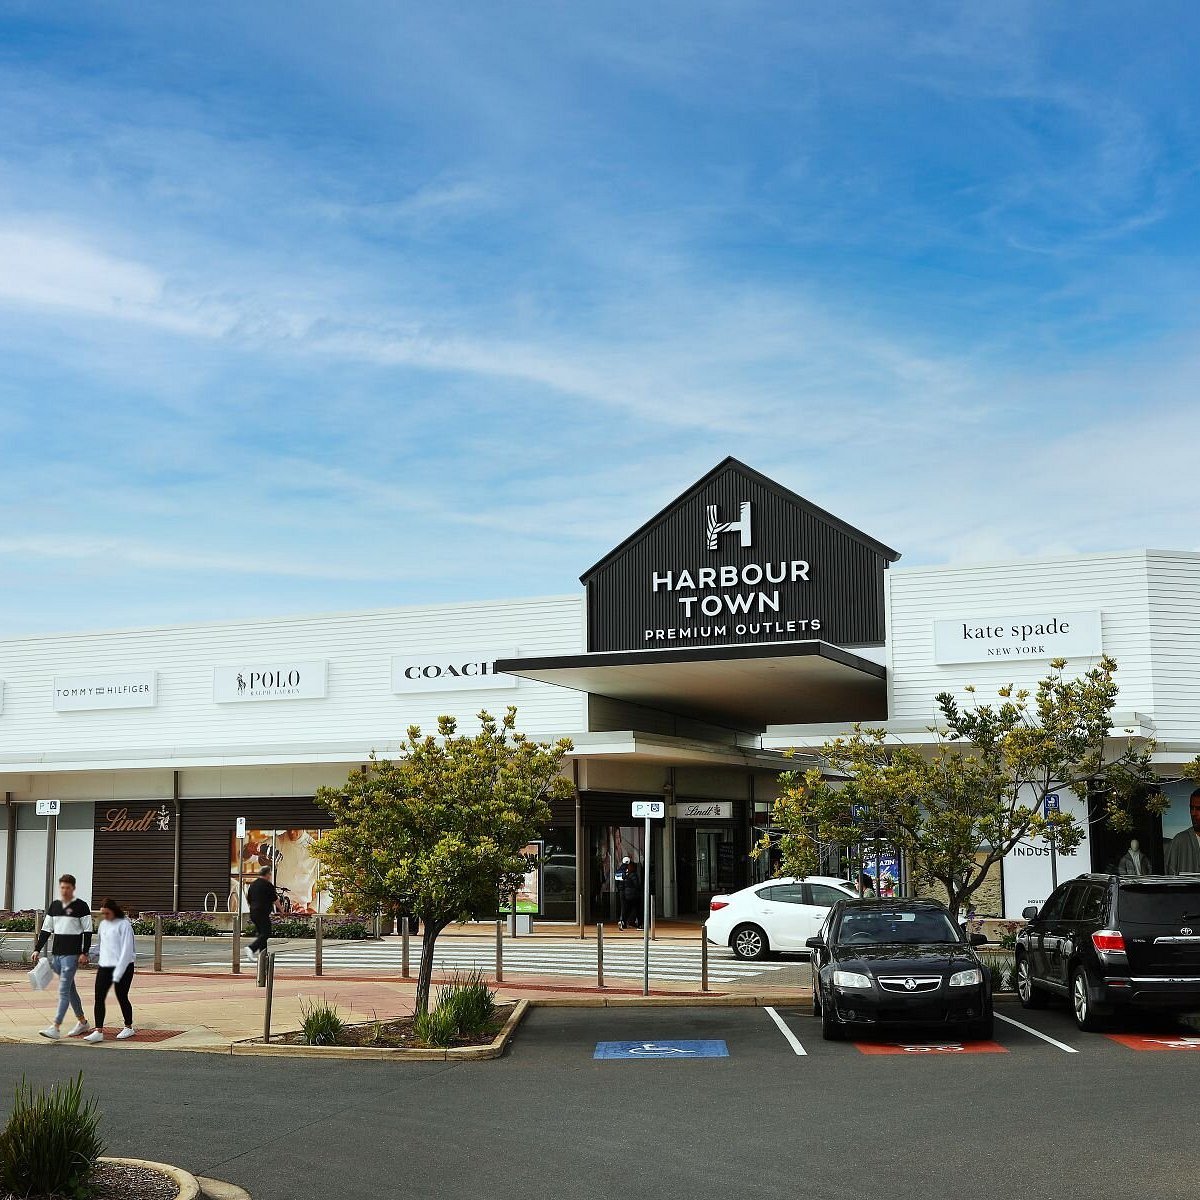
Northern Adelaide features established competitors like Parabanks Shopping Centre (GLA 45,000 sqm, 120 stores) and Elizabeth City Centre (GLA 50,000 sqm), offering broader mixes including supermarkets and dining, potentially drawing general shoppers away from outlets. Harbour Town Premium Outlets in southern Adelaide provides the closest rival outlet experience but serves a different trade area. Market saturation in fashion categories is moderate, with Adelaide retail sales up 3.6% y-o-y in 2025, yet outlet formats face online competition from platforms like The Iconic. Strengths include minimal direct outlet rivals, enabling 30-70% discounts to capture price-sensitive traffic; risks involve regional economic ties to manufacturing, which could soften footfall during downturns.
Lease Terms and Operational Risks
Leasing at DFO Adelaide targets outlet retailers with terms featuring base rents estimated at AUD 200-400 per sqm annually, plus turnover percentages (5-10%), lower than prime CBD rates of AUD 500+ per sqm, providing cost advantages for expansion. Occupancy was over 70% at launch but current levels are undisclosed amid October 2025 receivership, signaling potential vacancies and renegotiation opportunities for new tenants. Operational challenges include aging regional infrastructure and reliance on car access, with public transport limited to buses; free parking mitigates this. Market reports note stable suburban occupancy at 92-95%, but the centres newness and financial oversight pose risks to maintenance and marketing, though growth in northern retail expenditure offers upside for long-term leases of 5-10 years.
Building Details
Detailed Market Analytics
City Snapshot
Adelaide, SA
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Adelaide
Discover more shopping centers in Adelaide.


Popular in Australia
Top retail destinations across Australia.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Adelaide, SA
Comprehensive market intelligence for retail expansion in this city