Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
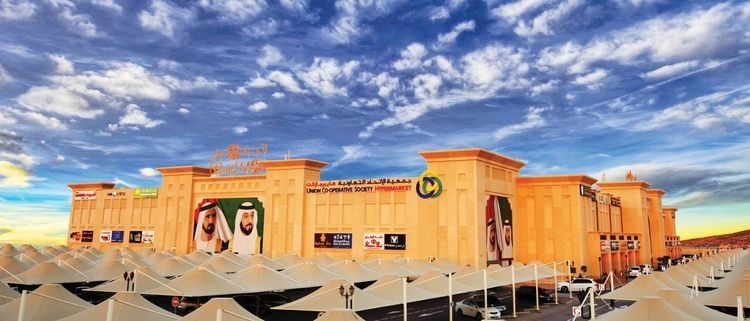
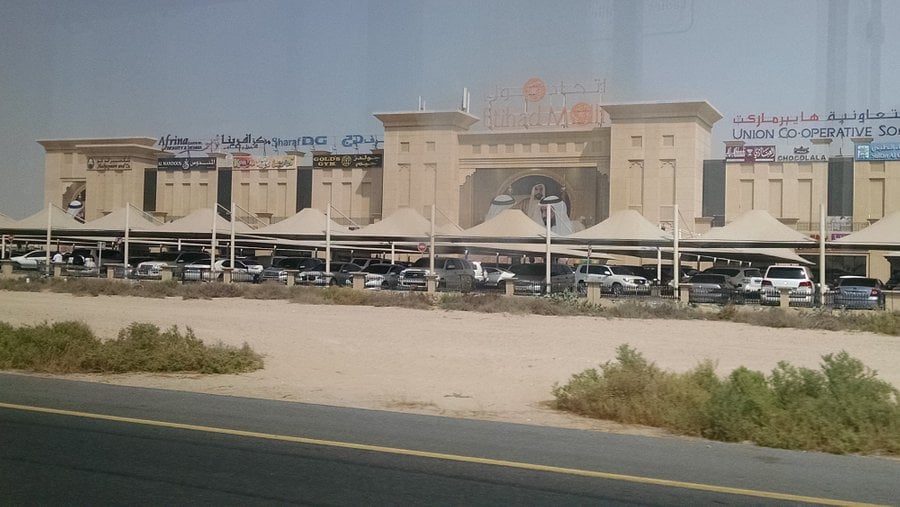
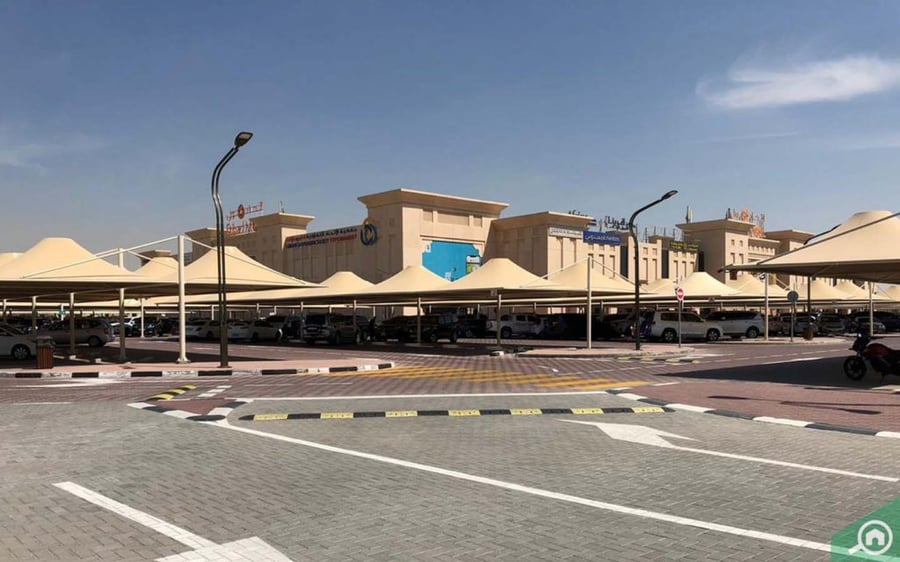
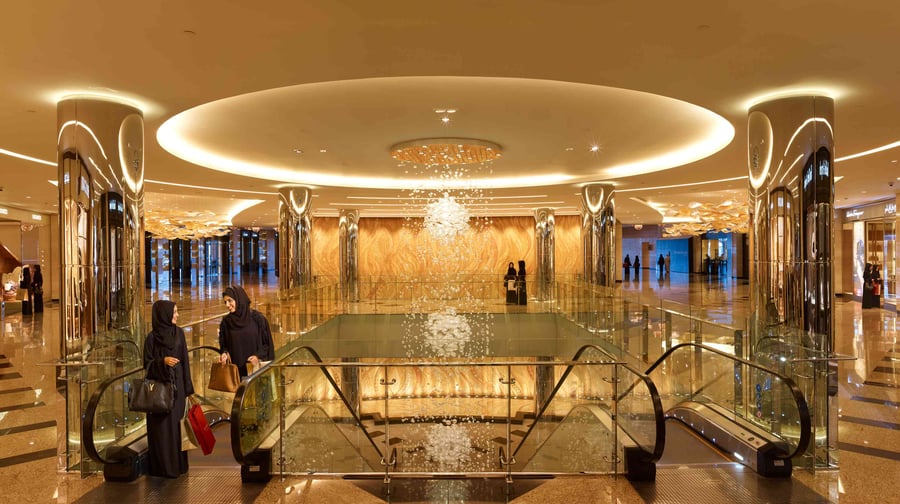
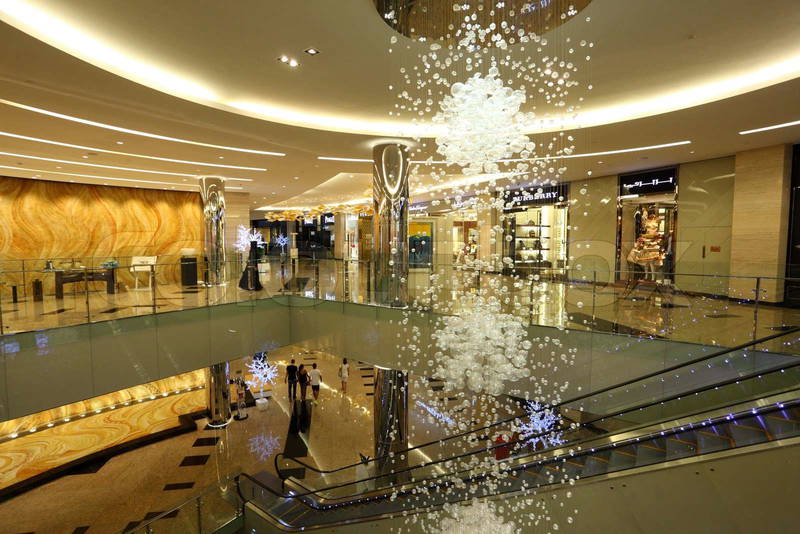
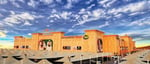
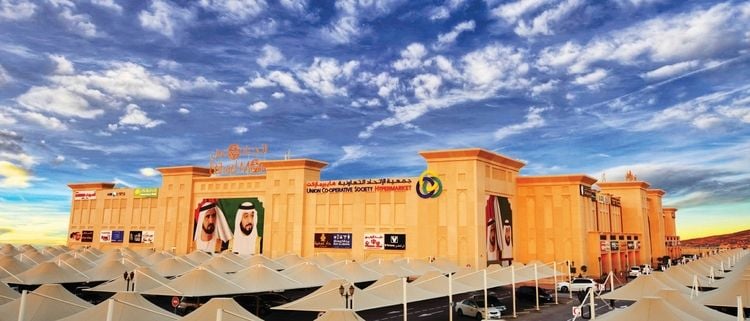
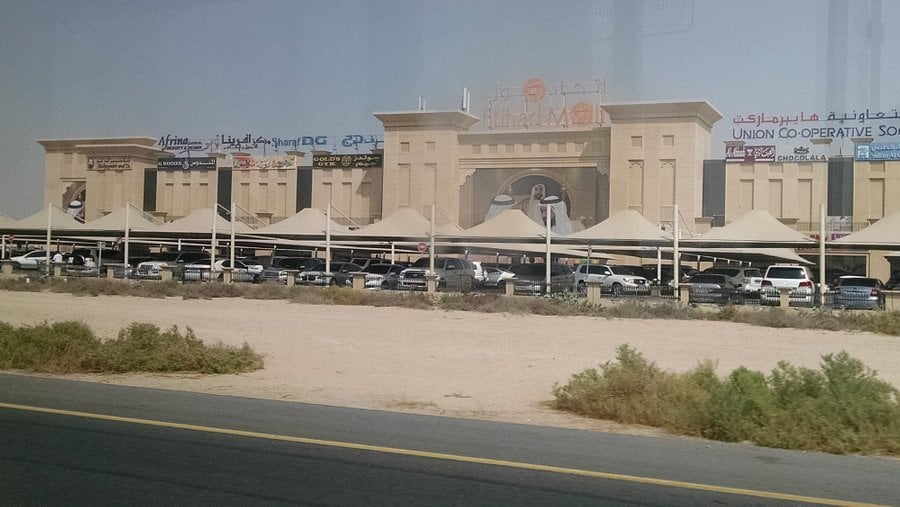
Etihad Mall is a community shopping center located in the Al Mizhar area of Dubai, along Al Khawaneej Road, serving the residential neighborhoods of Mirdif and Muhaisnah.
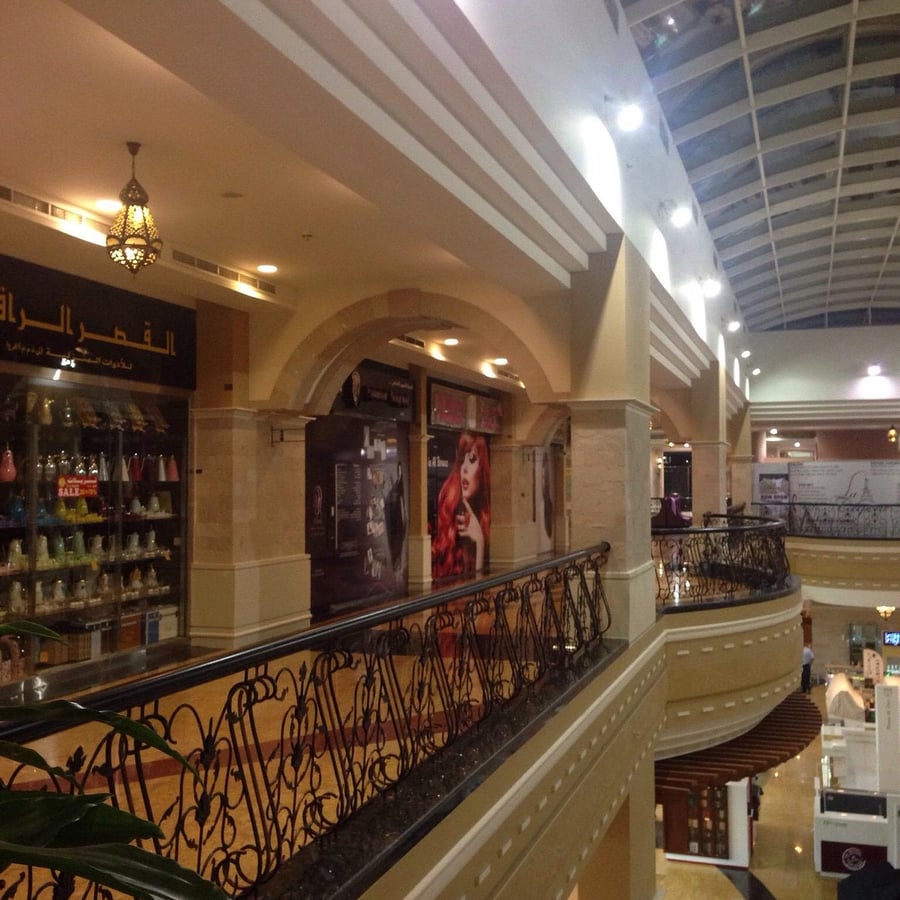
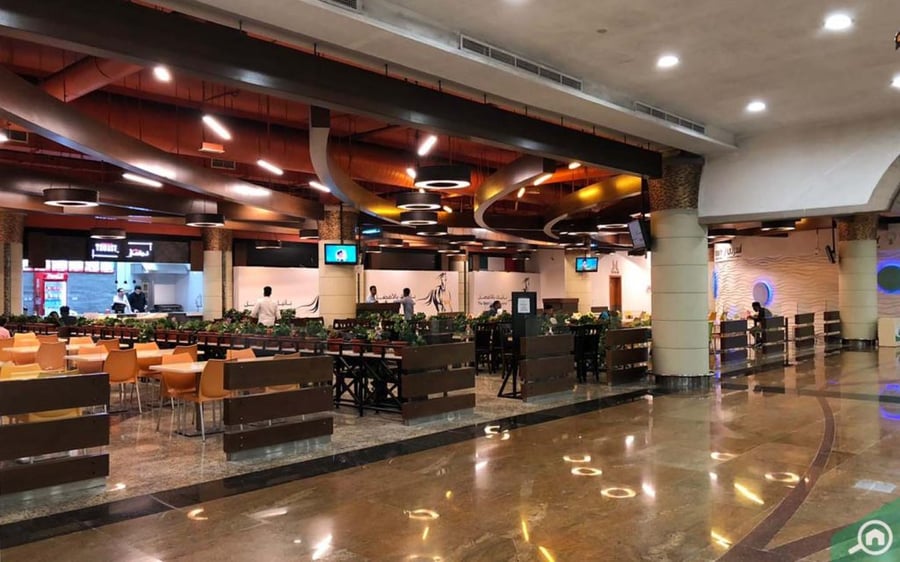
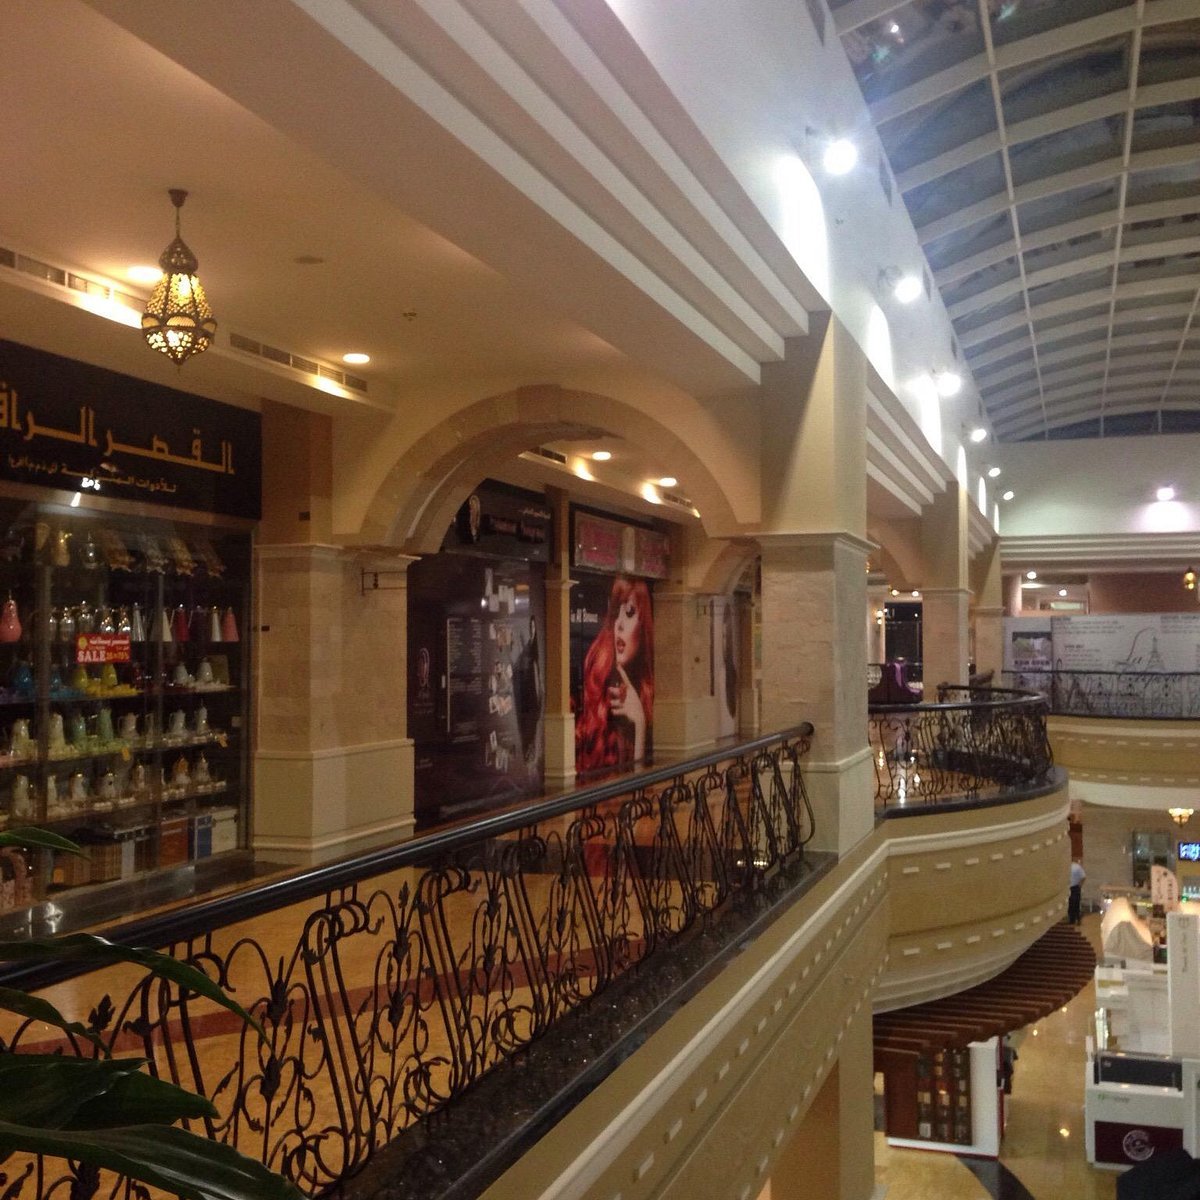
Spanning approximately 36,117 square meters of gross leasable area, it functions as a neighborhood retail hub anchored by the Union Coop hypermarket on the ground floor. The tenant mix comprises a balanced selection of essential and lifestyle retailers, including fashion outlets, electronics stores, grocery sections, wellness and beauty services such as salons and pharmacies, florists, and casual dining options like coffee shops.
This setup caters primarily to everyday shopping needs of local residents rather than tourist-driven luxury retail. In the broader Dubai retail market, which saw average mall occupancy rates of 95% in 2025 according to Cushman & Wakefield reports, Etihad Mall maintains a stable position with estimated occupancy around 90%, benefiting from the area's population growth driven by affordable housing developments.
The surrounding demographics feature middle-income expatriate families and UAE nationals, with a household income range of AED 10,000-25,000 monthly, contributing to consistent local footfall estimated at 5,000-8,000 visitors daily, lower than super-regional malls but reliable for non-discretionary spending categories.
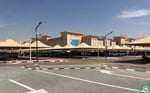
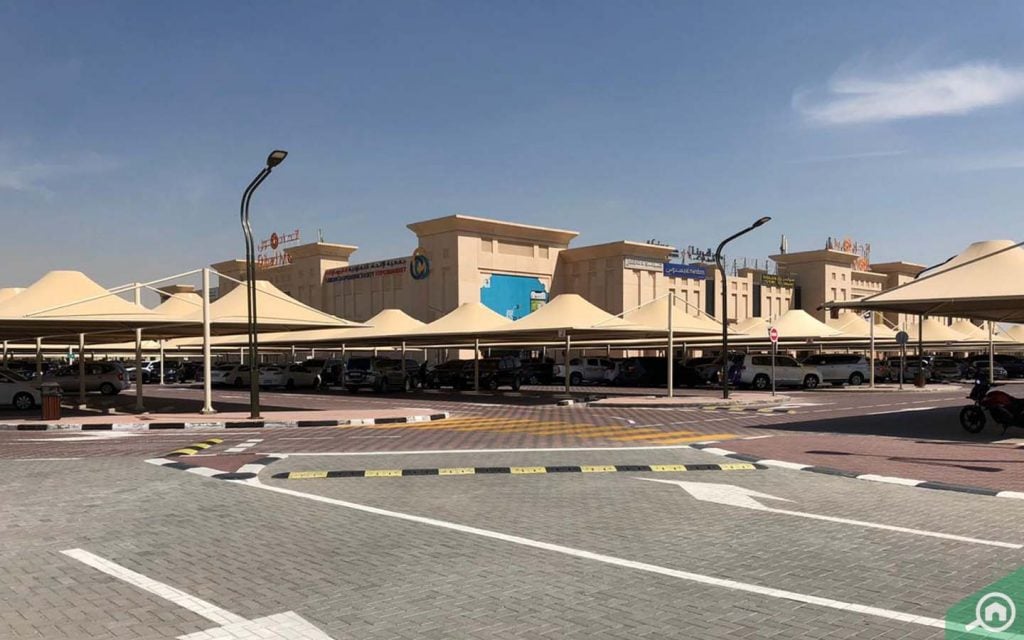
Accessibility is facilitated by proximity to major roads like Al Khawaneej and E311 Sheikh Mohammed Bin Zayed Road, with ample on-site parking for over 500 vehicles, reducing access barriers.
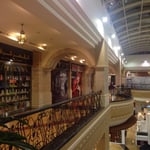
Leasing advantages include competitive base rents averaging AED 80-120 per square meter per month, significantly below prime mall rates of AED 300+, offering cost-effective entry for mid-tier retailers in groceries, health, and services. However, potential challenges arise from the mall's older infrastructure, built in the early 2000s, which may require tenant-funded fit-outs for modern standards, and competition from nearby larger venues like Dragon Mart or Deira City Centre, which draw higher footfall in apparel and entertainment.
Market saturation in community retail segments could pressure margins, though the area's expanding residential base, with over 100,000 residents within a 5km radius per Dubai Land Department data, supports sustained performance for resilient categories.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 12:00 AM |
| Friday | 10:00 AM — 12:00 AM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
The primary catchment area encompasses Mirdif, Muhaisnah, and Al Mizhar, with a diverse demographic of approximately 150,000 residents within 10km, including 70% expatriates from South Asia and Arab countries, and 30% UAE nationals, per 2025 Dubai Statistics Center reports. Family-oriented households dominate, with average ages 25-45 and focus on value-driven purchases in groceries and essentials. Daily footfall averages 6,000-7,500 visitors, peaking on weekends, supported by local traffic but limited by lack of public transport integration, unlike metro-connected malls. This steady, localized traffic favors stable sales in non-cyclical categories, though it lags behind regional averages of 20,000+ for comparable community centers, potentially impacting high-volume apparel tenants.
Tenant Mix and Occupancy
Occupancy stands at around 92%, aligned with Dubai's community mall average of 90-95% as per 2025 Cavendish Maxwell market insights, with low turnover due to long-term anchors like Union Coop occupying 40% of space. The mix is 35% groceries and essentials, 25% fashion and accessories, 20% services (pharmacy, salon), and 20% F&B and others, providing balanced synergy for cross-shopping. Strengths include essential retail resilience, but weaknesses in entertainment offerings may deter family dwell time compared to competitors. Recent leasing activity shows 5-10% vacancy in upper floors, offering opportunities for pop-ups, though aging fixtures could increase operational costs for new tenants.
Lease Terms and Market Risks
Base rents range from AED 80-120 per square meter monthly for ground floor spaces, with turnover rents at 8-12% of sales, lower than super malls' AED 200-400, per general commercial real estate data from Bayut 2025. Lease terms typically span 3-5 years for non-anchors, with renewal options, but include clauses for infrastructure upgrades amid Dubai's retail evolution toward sustainability. Risks involve regional competition from expanding formats like mixed-use developments, potential footfall dips from economic fluctuations affecting expat spending, and infrastructure challenges like limited expansion potential in a saturated neighborhood market, necessitating careful category selection to avoid overlap with hypermarket dominance.
Building Details
Detailed Market Analytics
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Dubai
Discover more shopping centers in Dubai.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city