




















Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
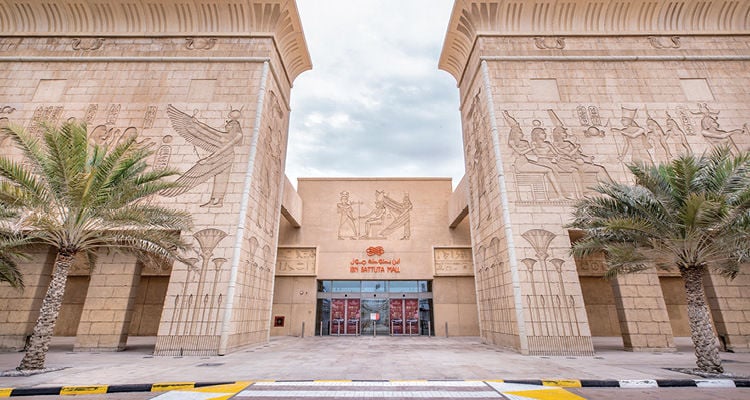
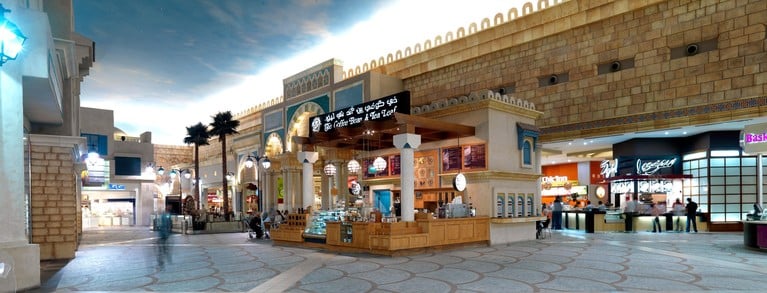
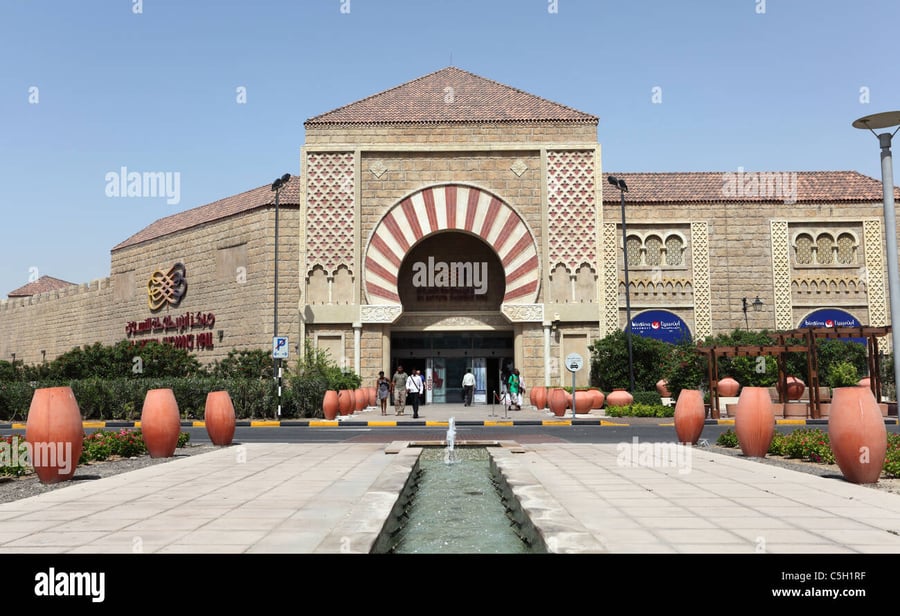
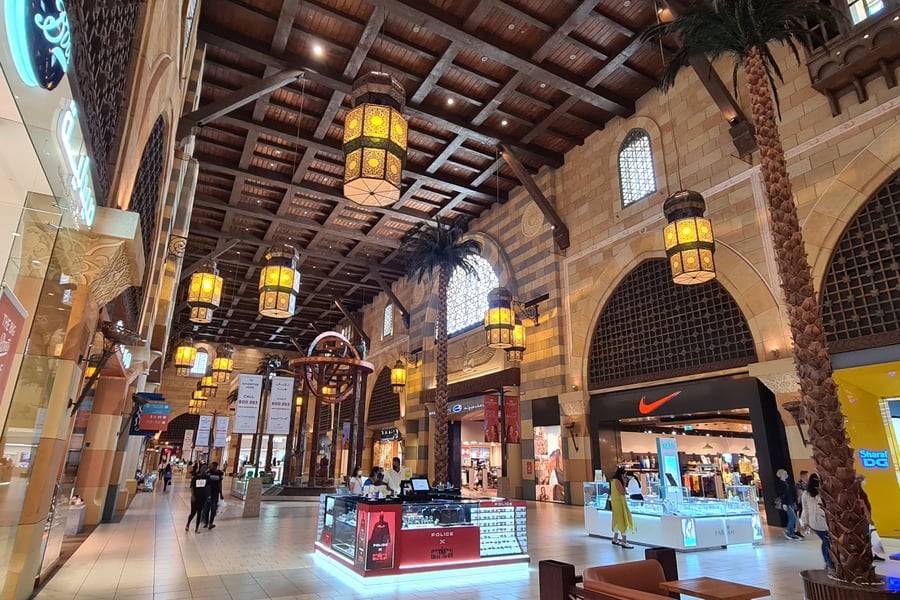
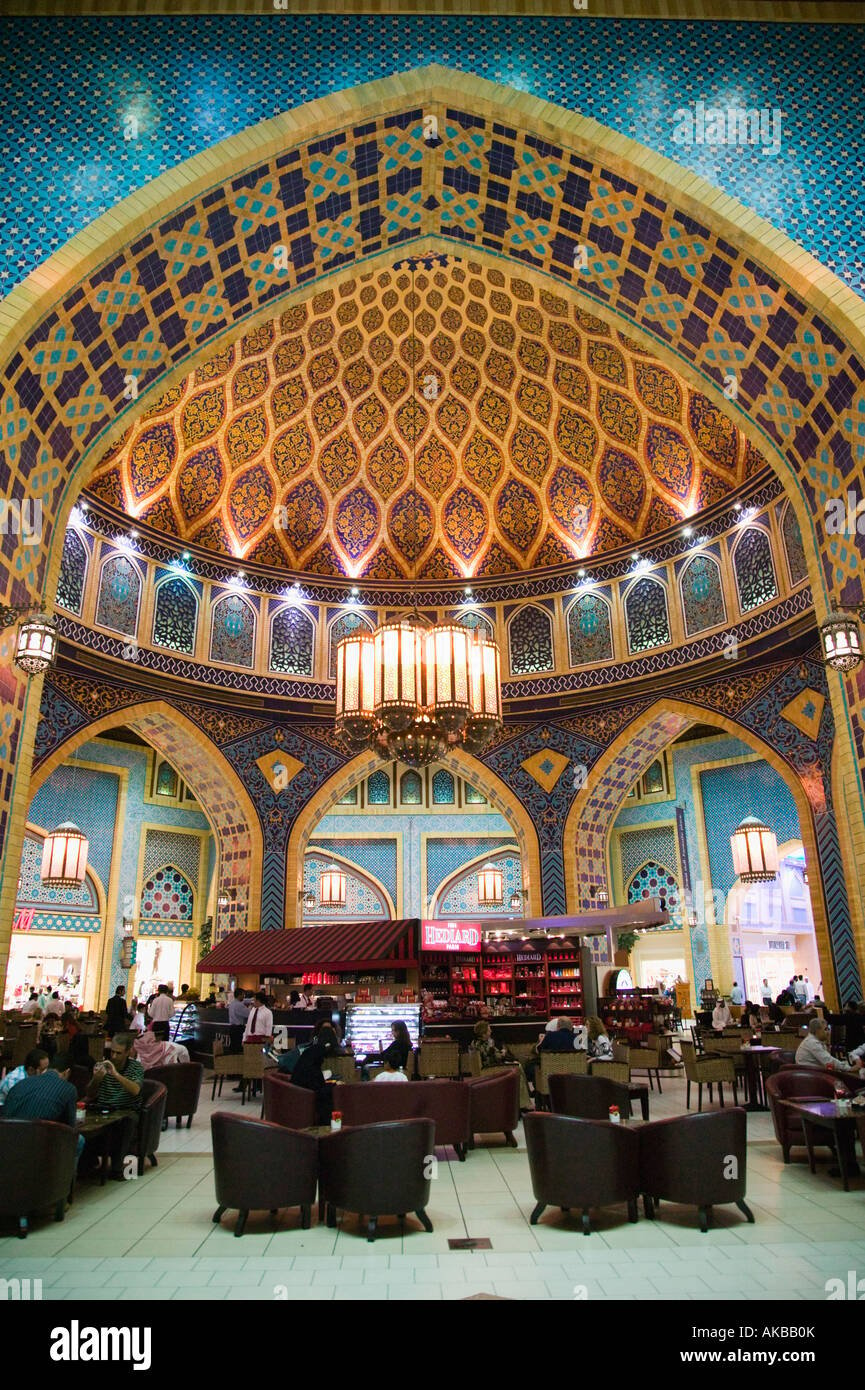
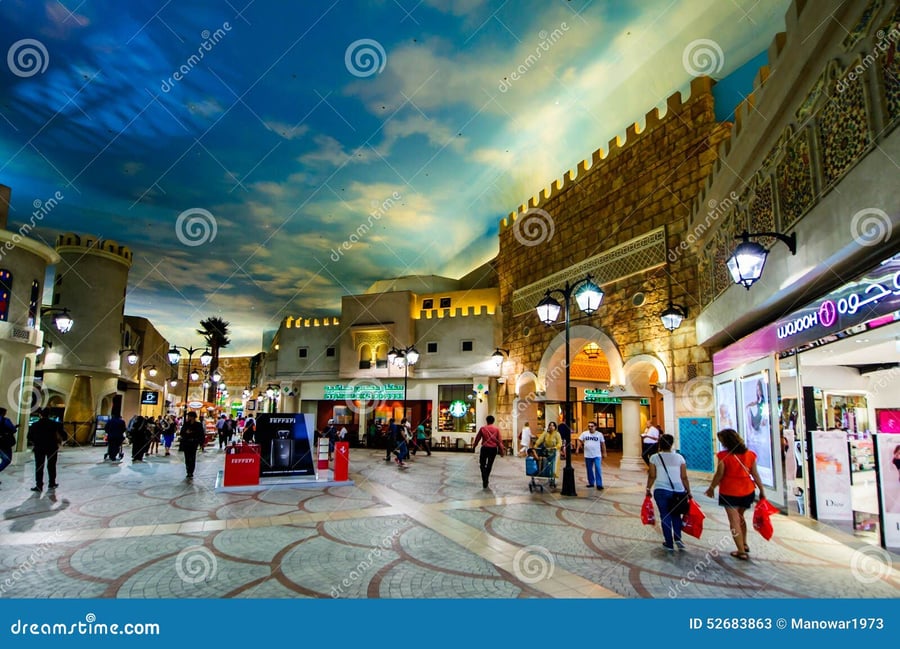
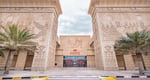
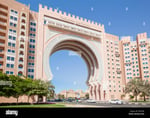
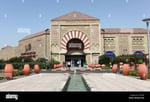
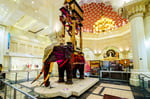
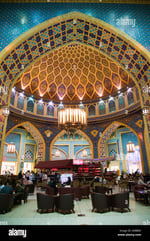
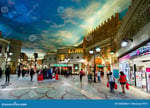
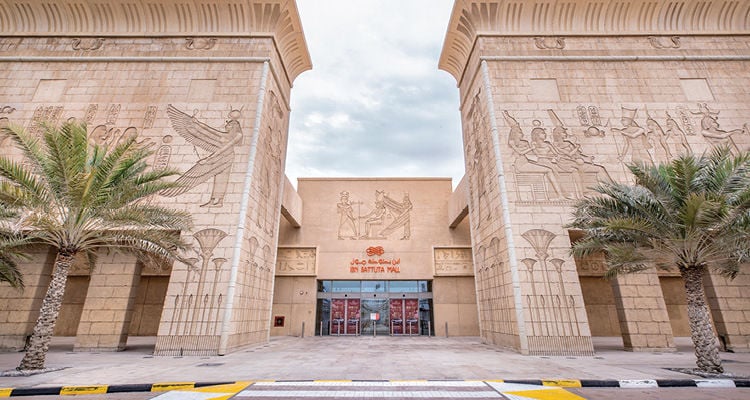
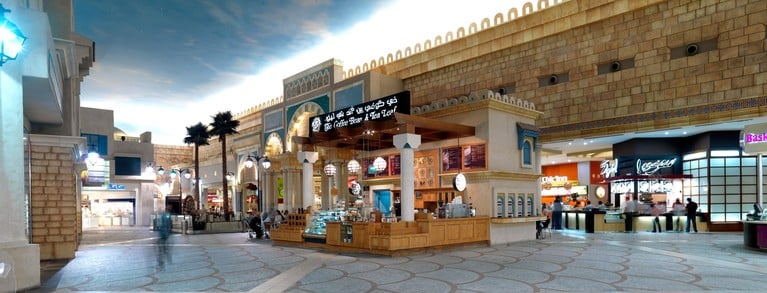
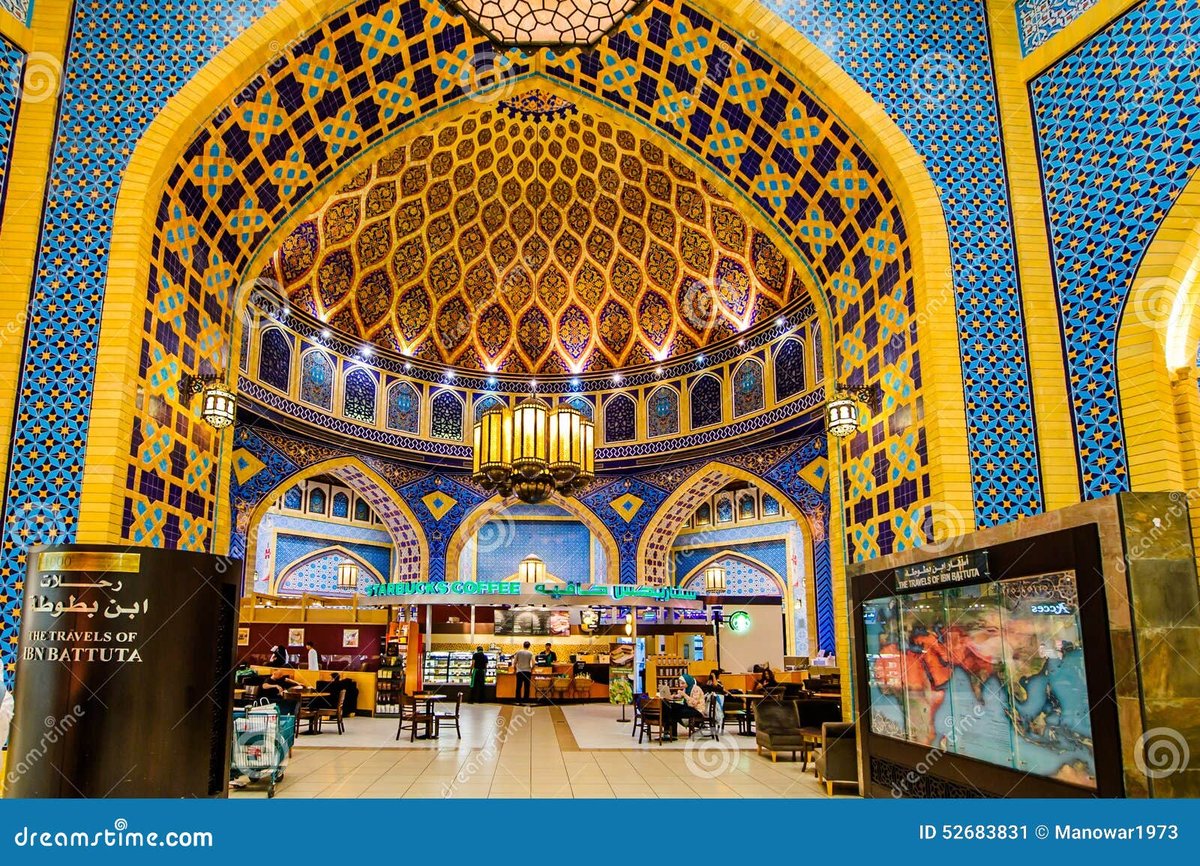
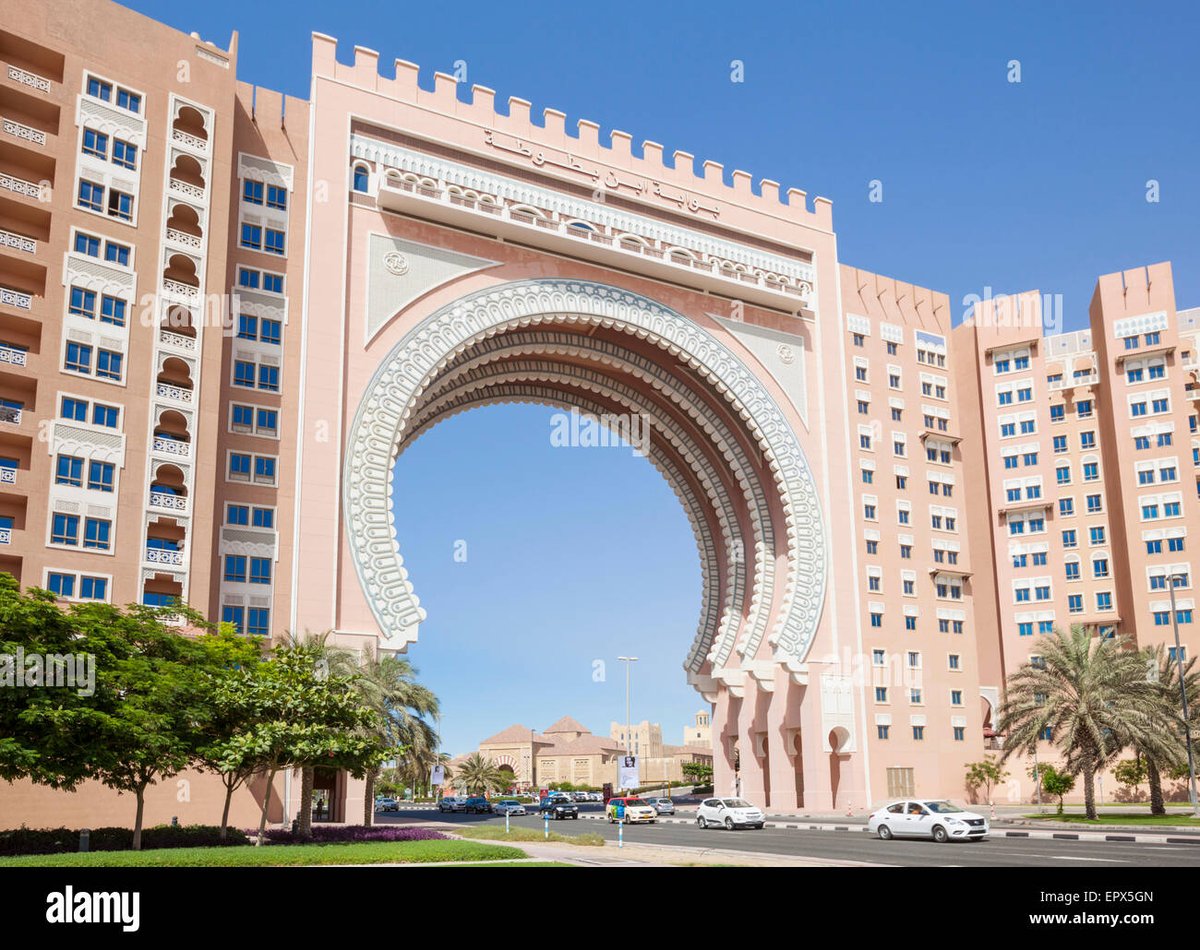
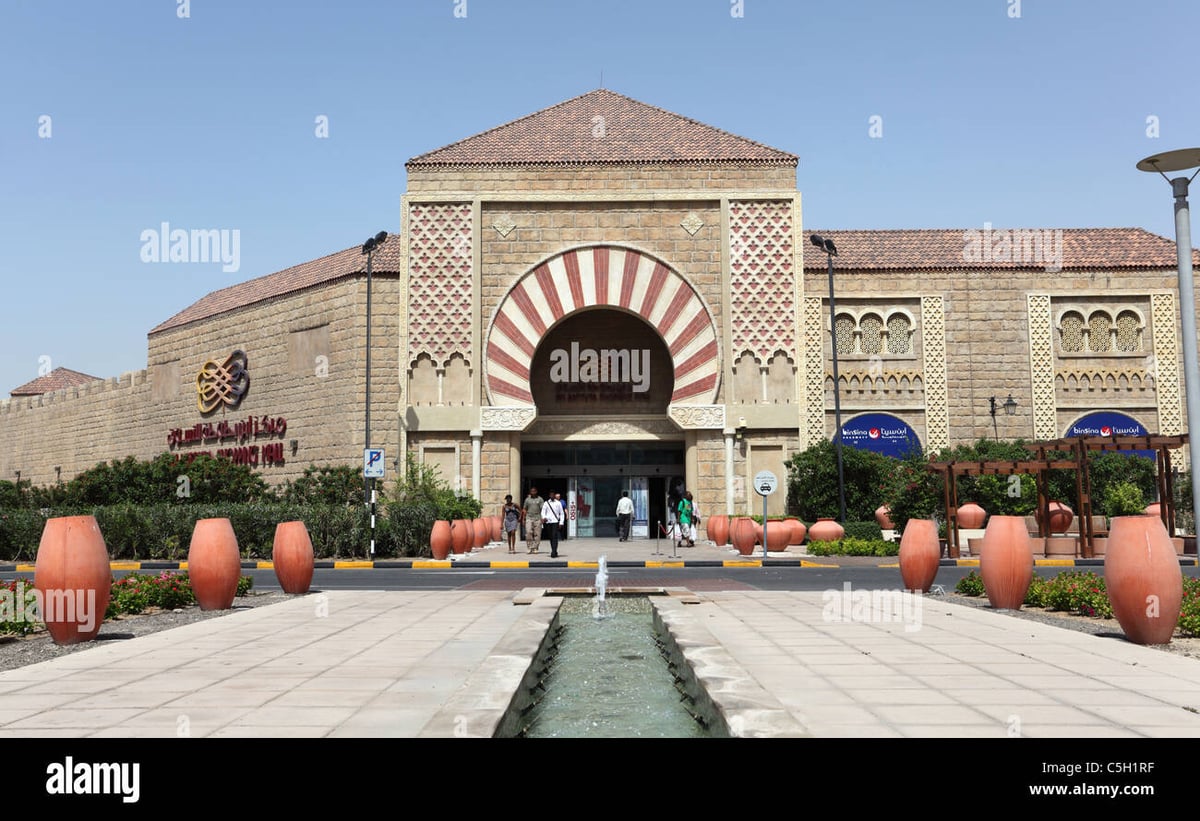
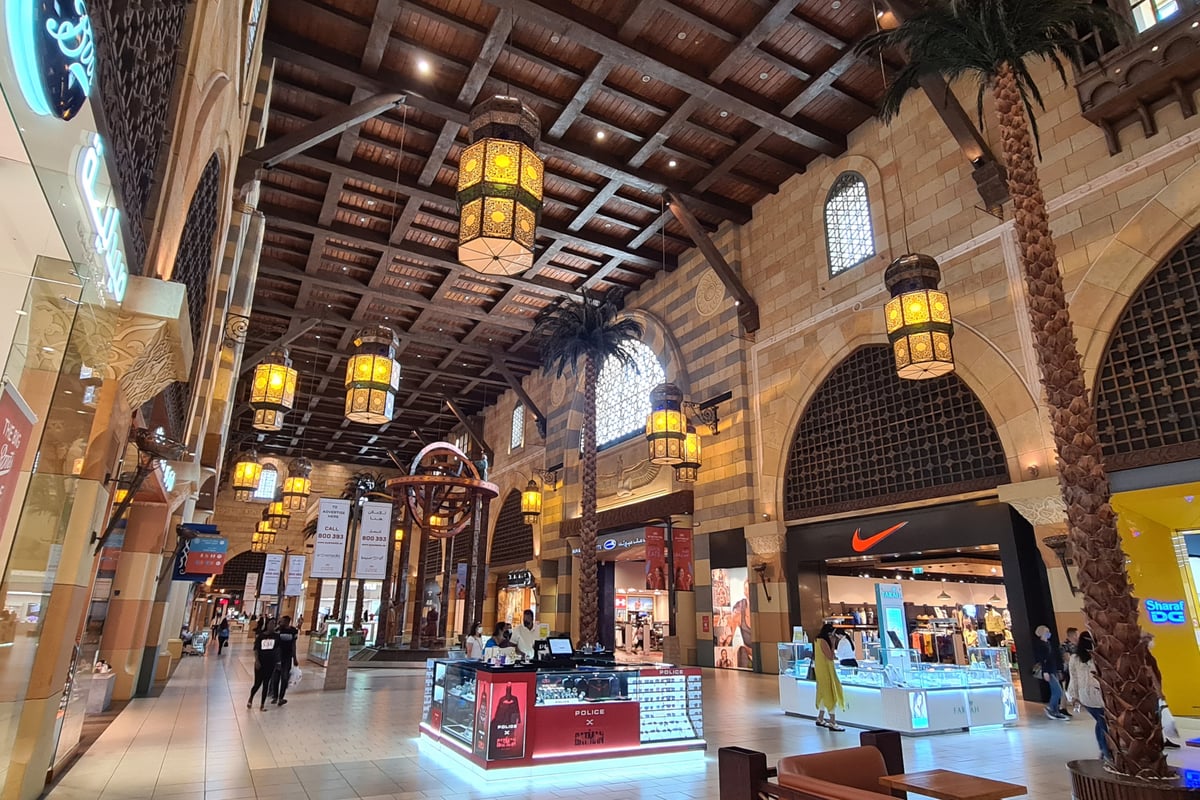
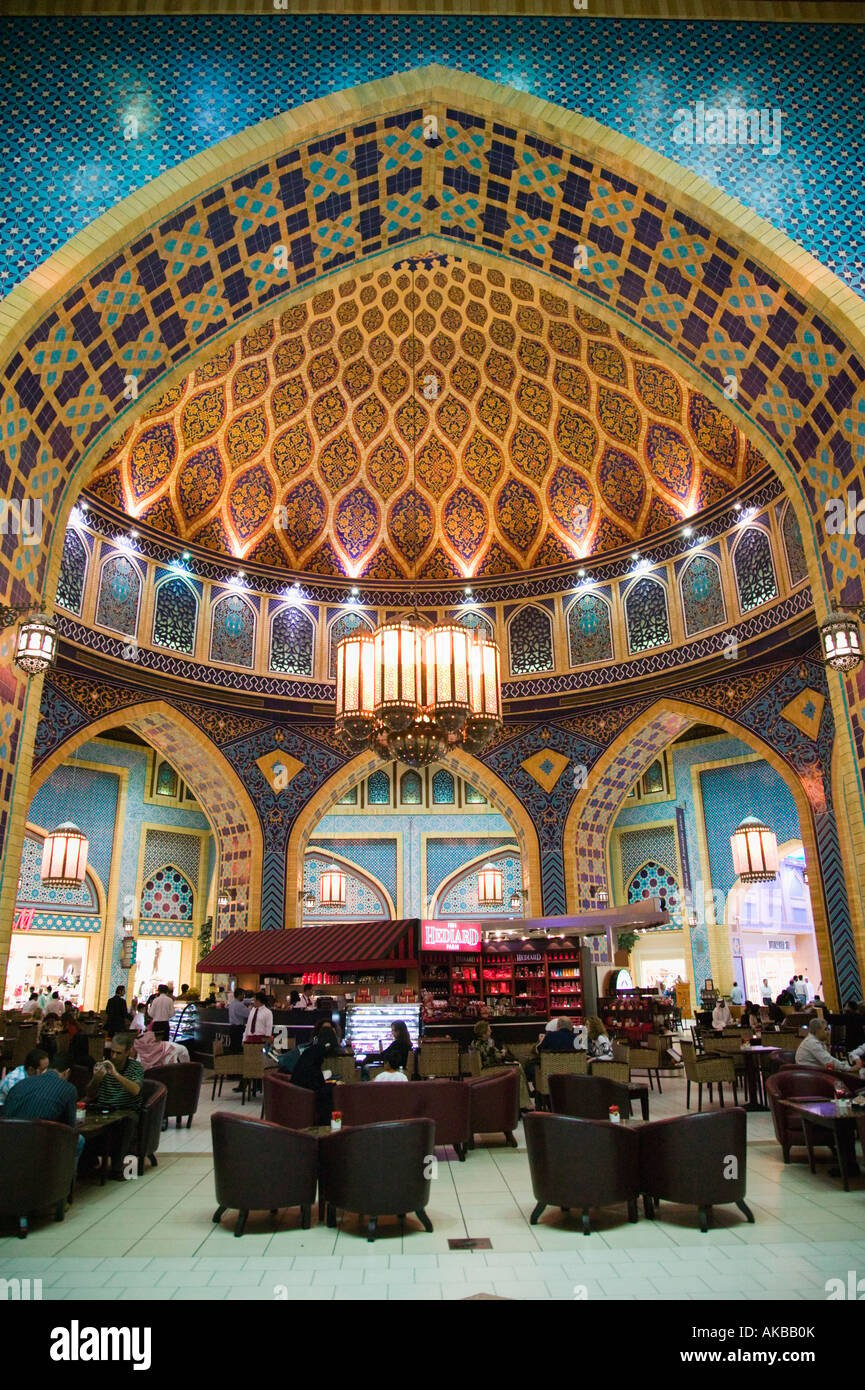
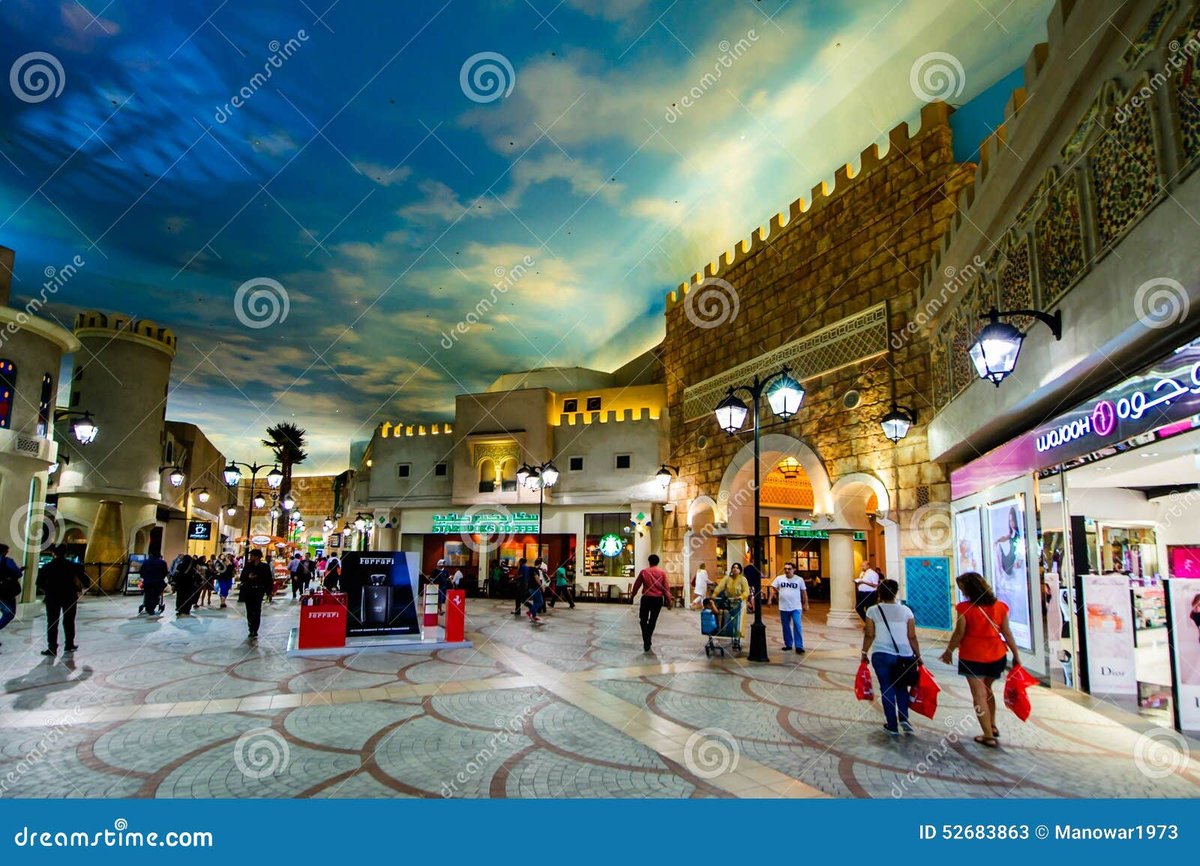
Ibn Battuta Mall, situated in Jebel Ali, southwest Dubai, UAE, is a super regional shopping center developed by Nakheel Malls LLC and opened in 2005. It encompasses 135,497 sqm of gross leasable area over two levels, uniquely themed around explorer Ibn Battuta's travels with distinct courts representing China, India, Persia, Egypt, and Andalusia. The property hosts over 400 stores, featuring a tenant mix of 40% fashion and accessories (e.g., H&M, Marks & Spencer, Centrepoint), 20% food and beverage, 15% leisure and entertainment (Cinepolis cinemas), 10% electronics, and anchors like Carrefour hypermarket, Union Coop, Spinneys supermarkets, Decathlon, and MediClinic.
Occupancy stands at 90-95%, with 92% reported in 2024 per Cushman & Wakefield data, bolstered by annual footfall of 15-18 million visitors and daily averages of 40,000-50,000. In Dubai's competitive retail landscape, marked by market saturation and 9% prime rent growth in 2025, the mall positions as value-oriented, appealing to mid-tier consumers with base rents of AED 150-250 per sq ft annually and flexible leasing terms.
Advantages include proximity to residential areas like Discovery Gardens, direct metro access via Ibn Battuta station, and 4,348 parking spaces, fostering family-oriented traffic. However, challenges encompass intense competition from premium venues like Mall of the Emirates, traffic congestion on Sheikh Zayed Road, aging infrastructure requiring potential capex, and reliance on expatriate demographics vulnerable to economic shifts.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 12:00 AM |
| Tuesday | 10:00 AM — 12:00 AM |
| Wednesday | 10:00 AM — 12:00 AM |
| Thursday | 10:00 AM — 12:00 AM |
| Friday | 10:00 AM — 12:00 AM |
| Saturday | 10:00 AM — 12:00 AM |
| Sunday | 10:00 AM — 12:00 AM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile and Catchment
The mall's primary catchment area covers 500,000 residents in southwest Dubai communities such as Discovery Gardens and Jebel Ali Village, expanding to 1.2 million within a 5-10 km radius. Visitor demographics are 70% expatriates from South Asia, the Middle East, and Europe, with 60% comprising families and young professionals aged 25-45 (average age 34), household size of 4.2, and average monthly income of AED 18,000. This profile supports mid-tier spending on fashion, groceries, and leisure, aided by 4.5% annual population growth. Risks include exposure to visa policy changes and economic downturns impacting expatriate stability, potentially affecting footfall in non-essential categories.
Tenant Mix and Occupancy
With over 400 outlets, the tenant mix emphasizes value-oriented retail: 40% fashion/accessories, 20% F&B, 15% leisure/entertainment, and 10% electronics, anchored by Carrefour, supermarkets, and Decathlon. This diversity promotes cross-shopping and 90-minute average dwell times. Occupancy remains stable at 90-95% (92% in 2024), reflecting Dubai's robust retail recovery with low vacancy below 5% in prime areas. Leasing benefits from flexible terms and 10% percentage rents over thresholds, though saturation in fashion segments pressures smaller tenants. Operational quality is enhanced by themed courts boosting engagement, but high upkeep for entertainment areas increases costs.
Competition, Accessibility, and Risks
Dubai's retail market features high saturation with 5 malls per sq km; key competitors include the premium Mall of the Emirates (5 km away) and Dubai Festival City, diverting high-end traffic and challenging value segments. Accessibility via Sheikh Zayed Road and adjacent Ibn Battuta Metro station is offset by congestion issues, with 4,348 parking spaces available. Footfall peaks at 70,000 on weekends but dips 25% in summer. Strengths lie in family proximity and events; drawbacks include peripheral location limiting tourists, 20-year-old infrastructure needing upgrades, and expat-dependent spending vulnerable to market fluctuations, alongside 9% rent growth in 2025 pressuring margins.
Building Details
Detailed Market Analytics
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Dubai
Discover more shopping centers in Dubai.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city