Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
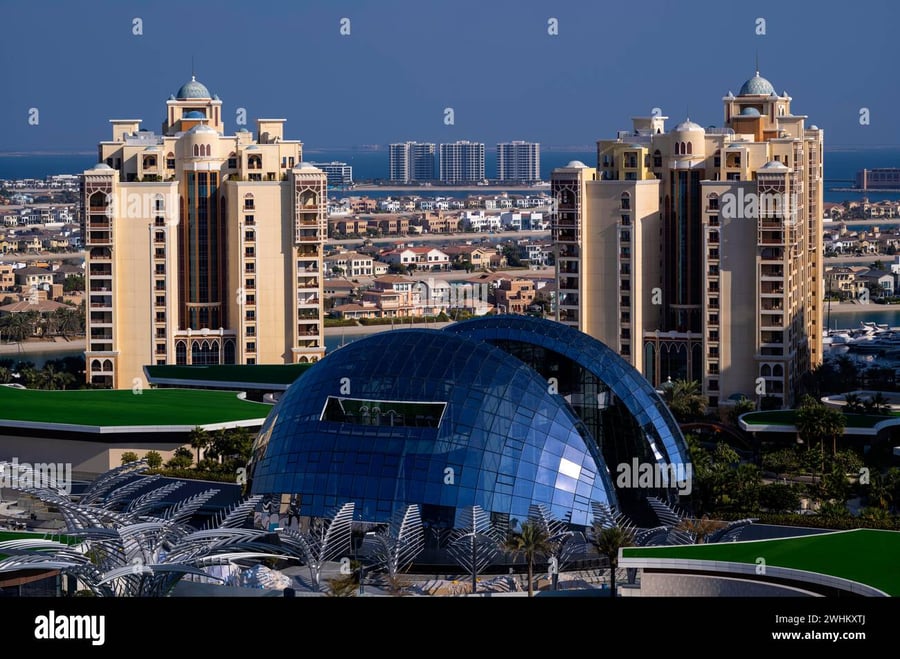
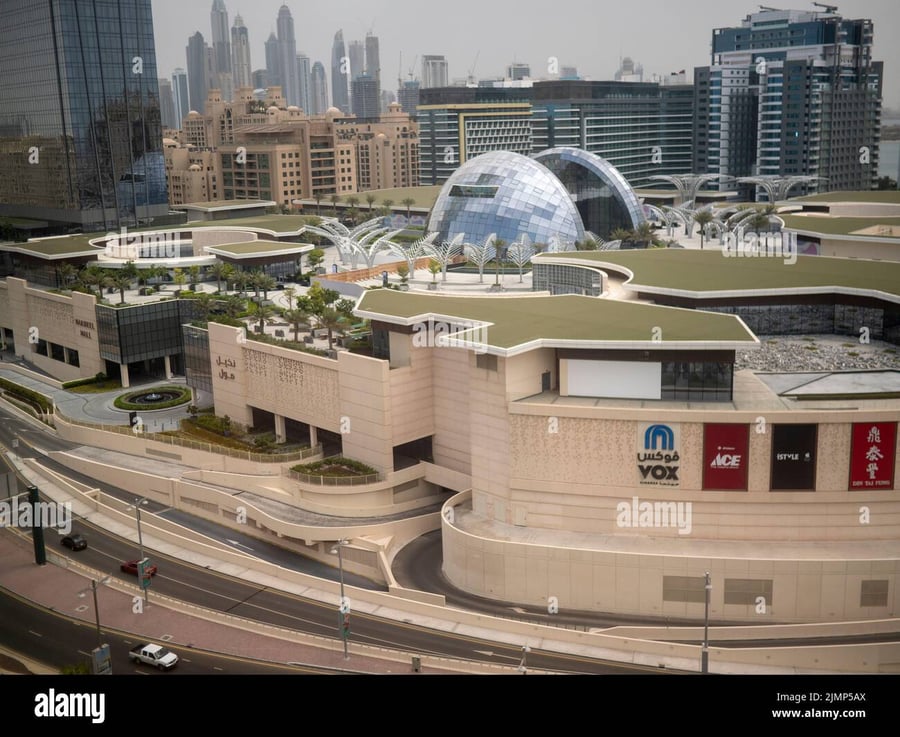
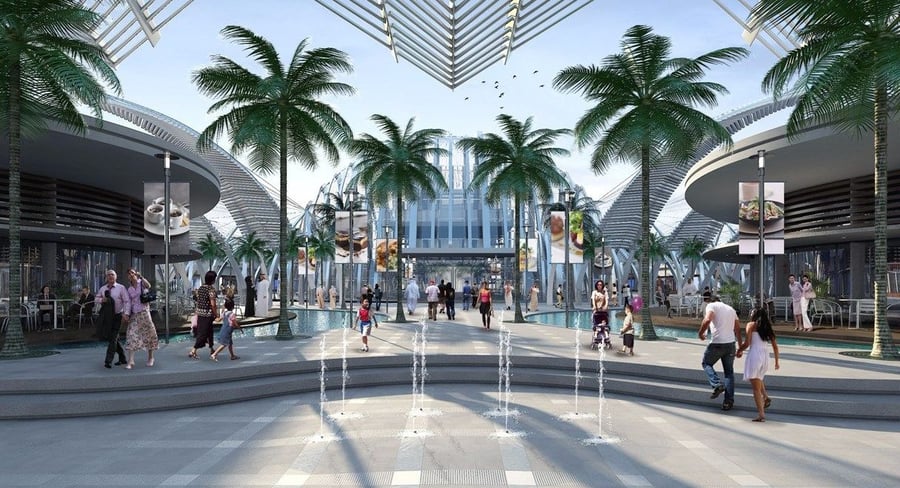
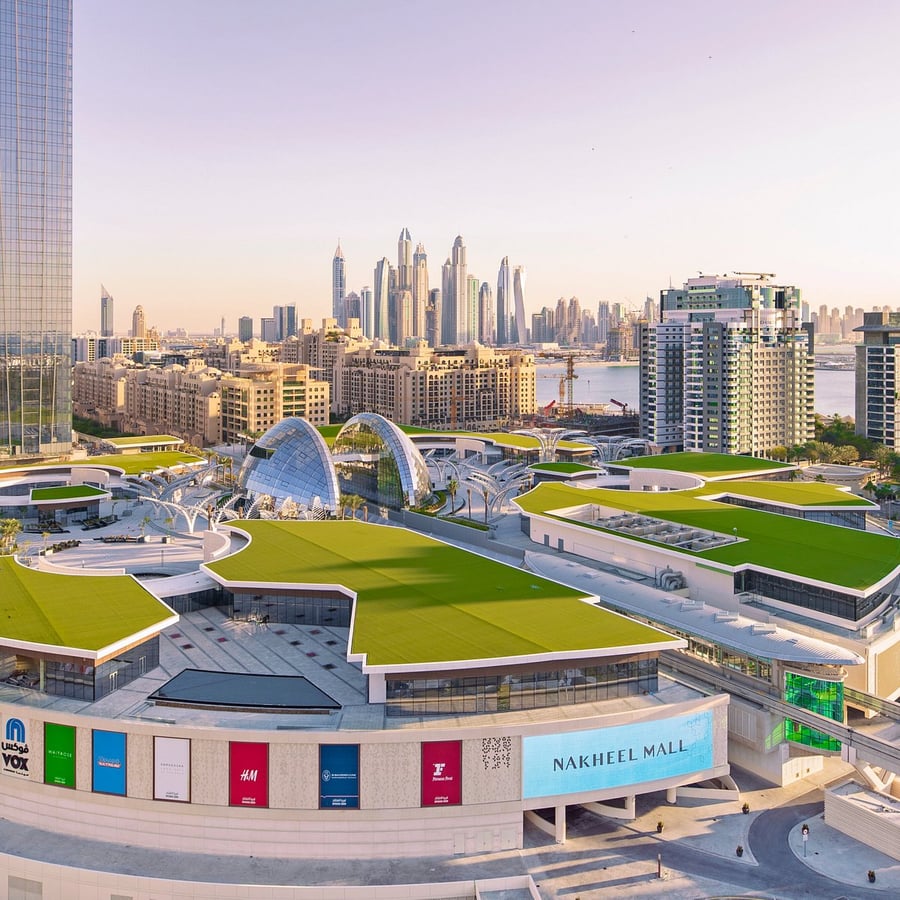
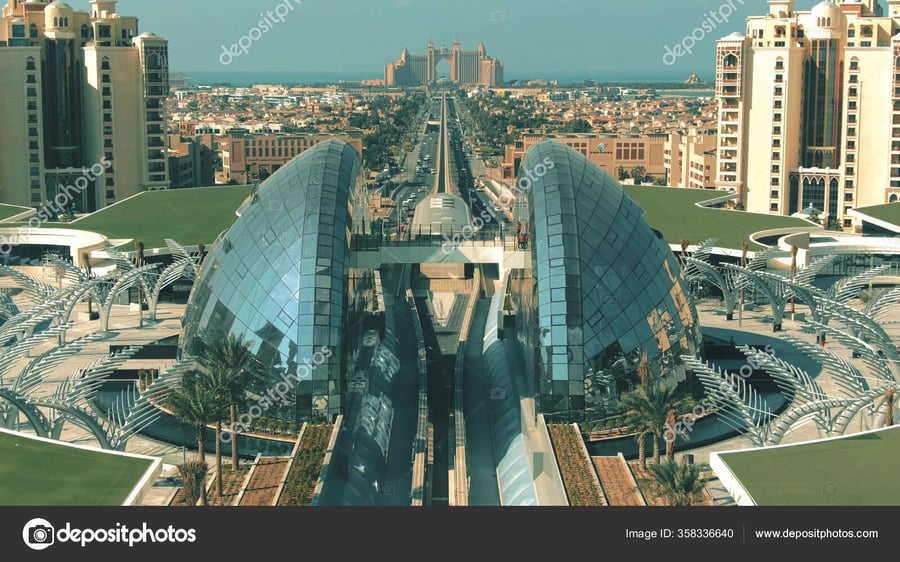
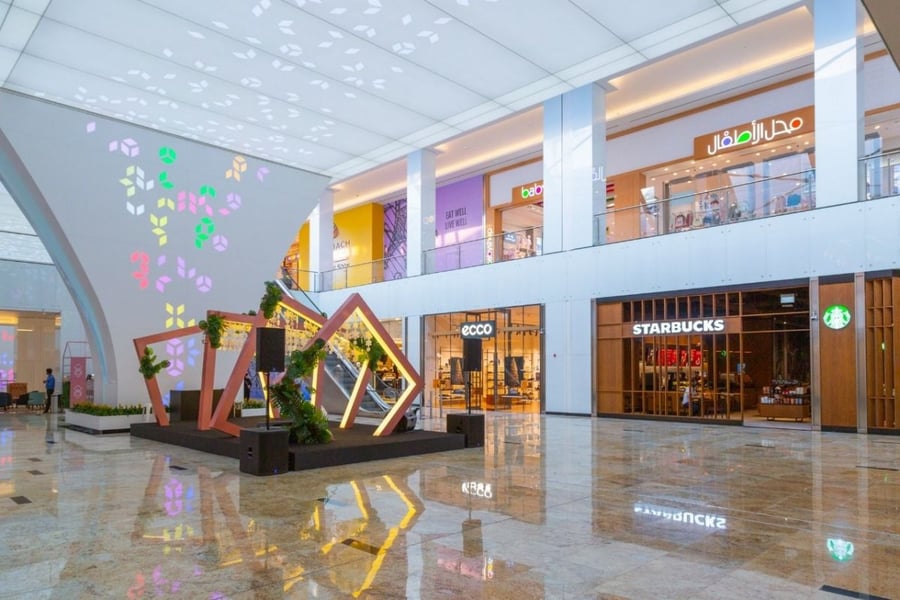
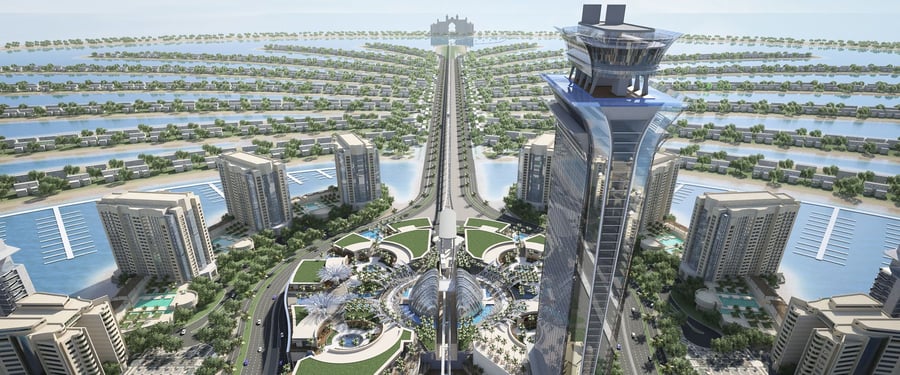
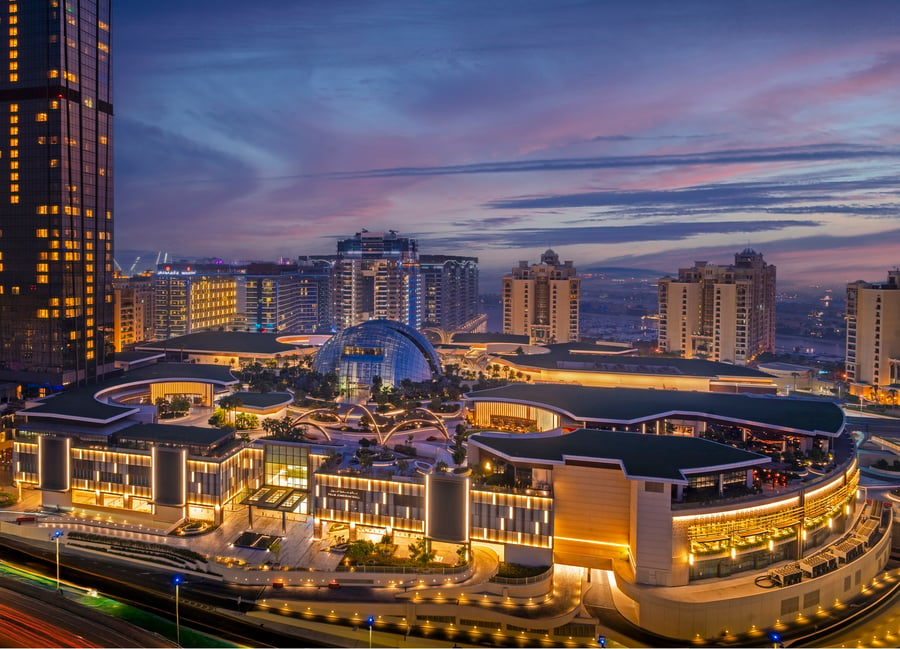
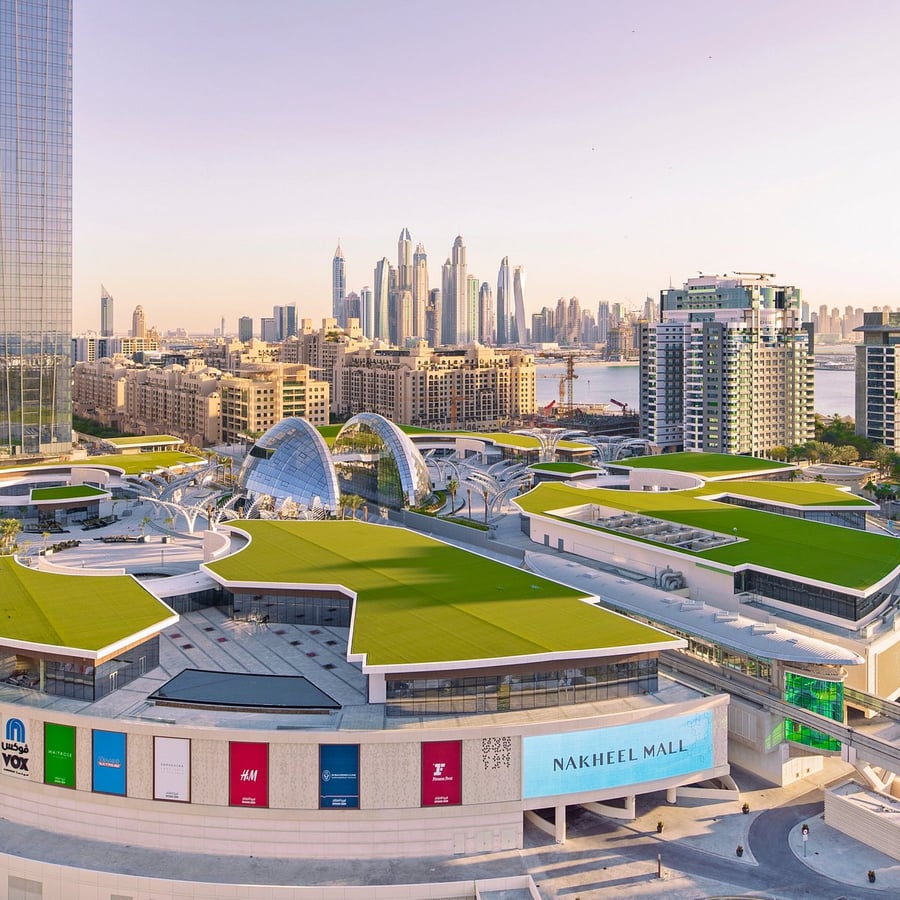
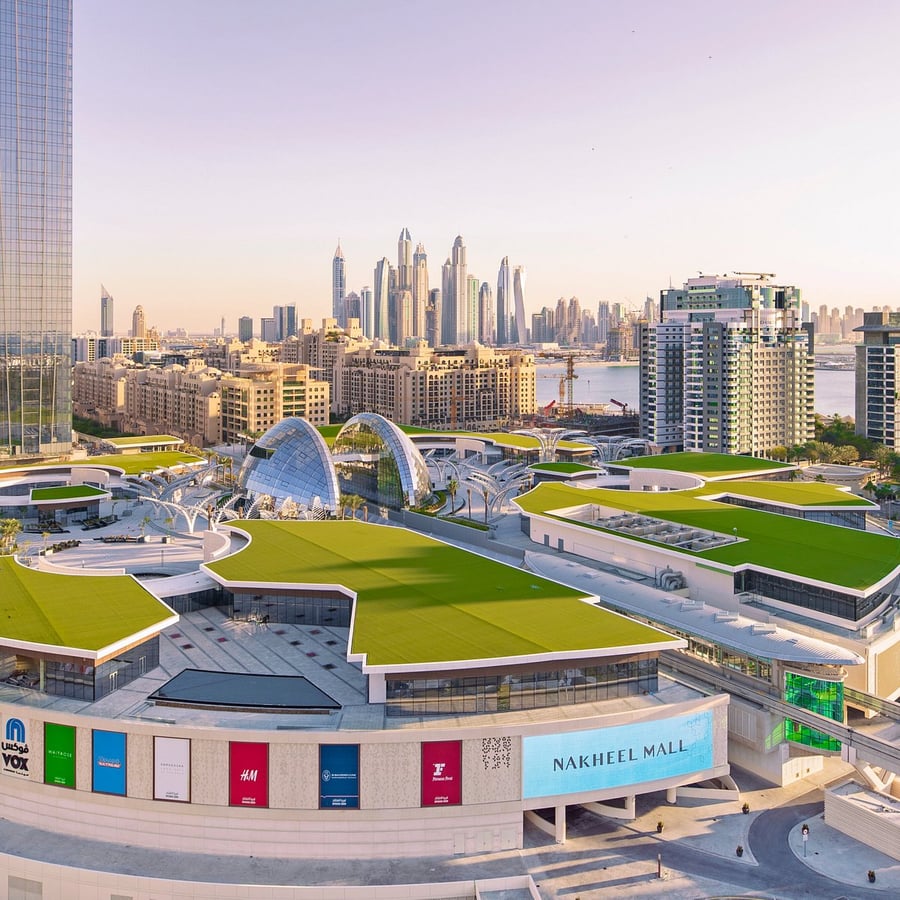
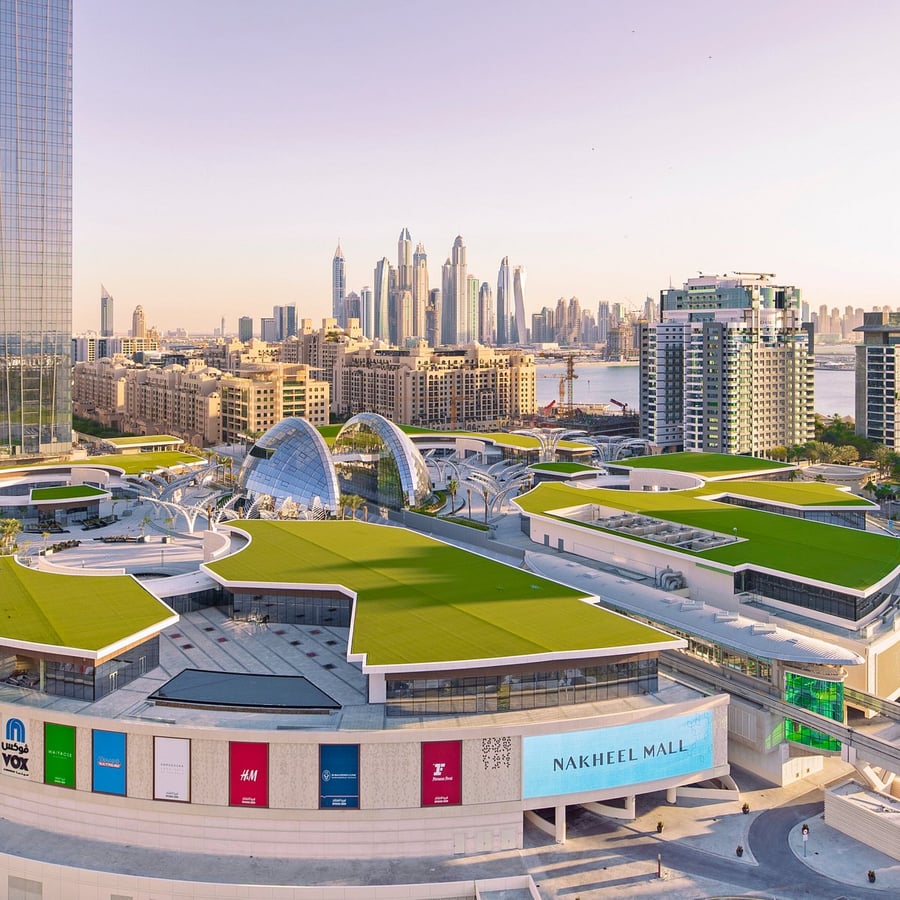
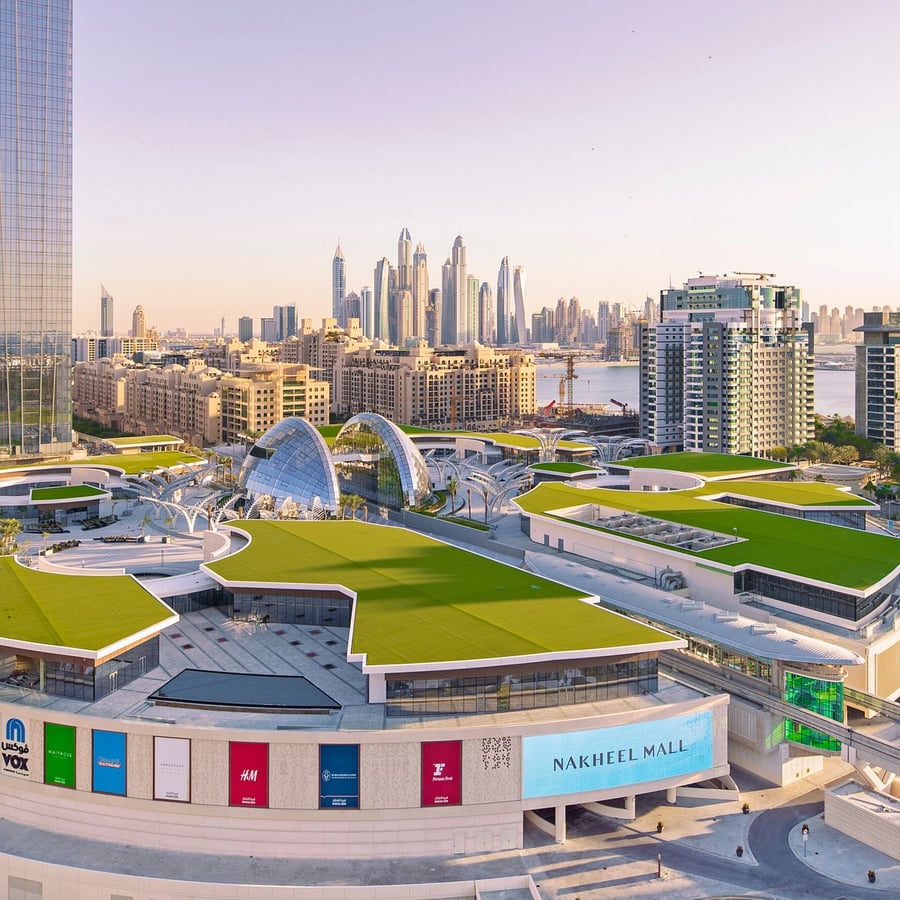
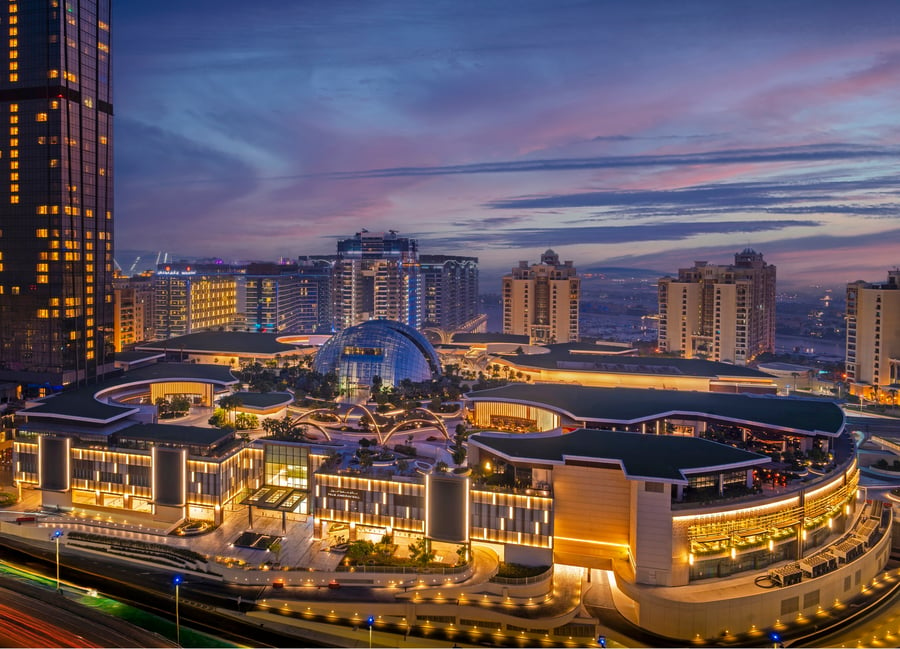
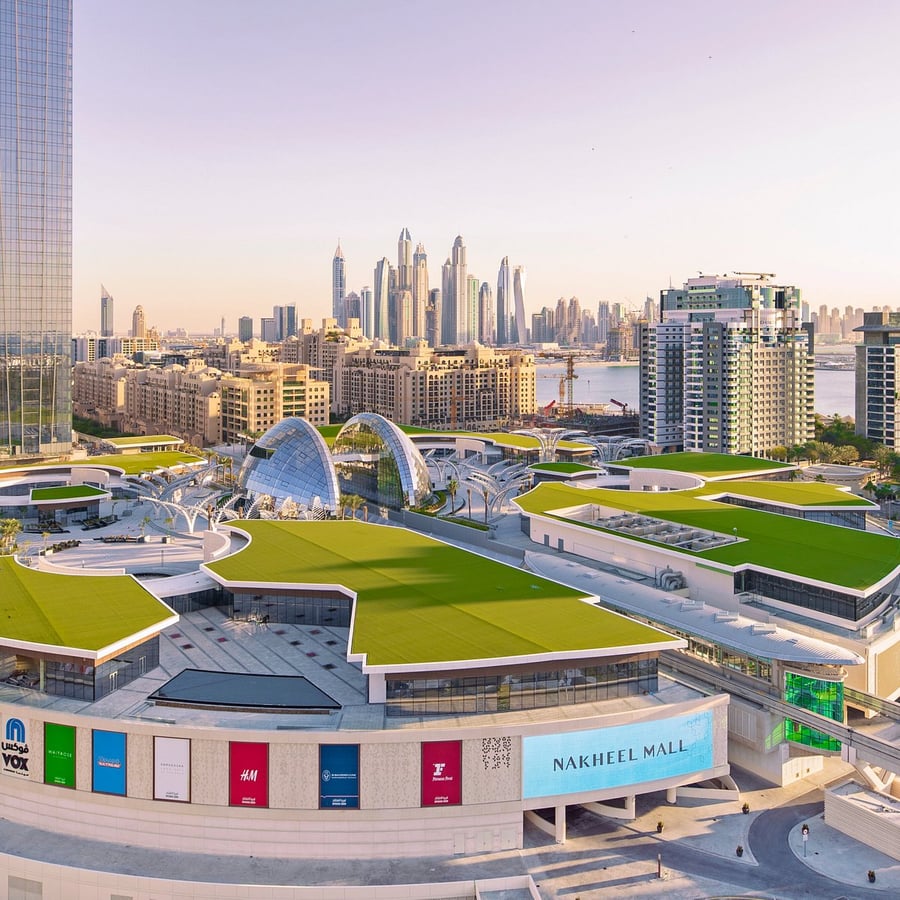
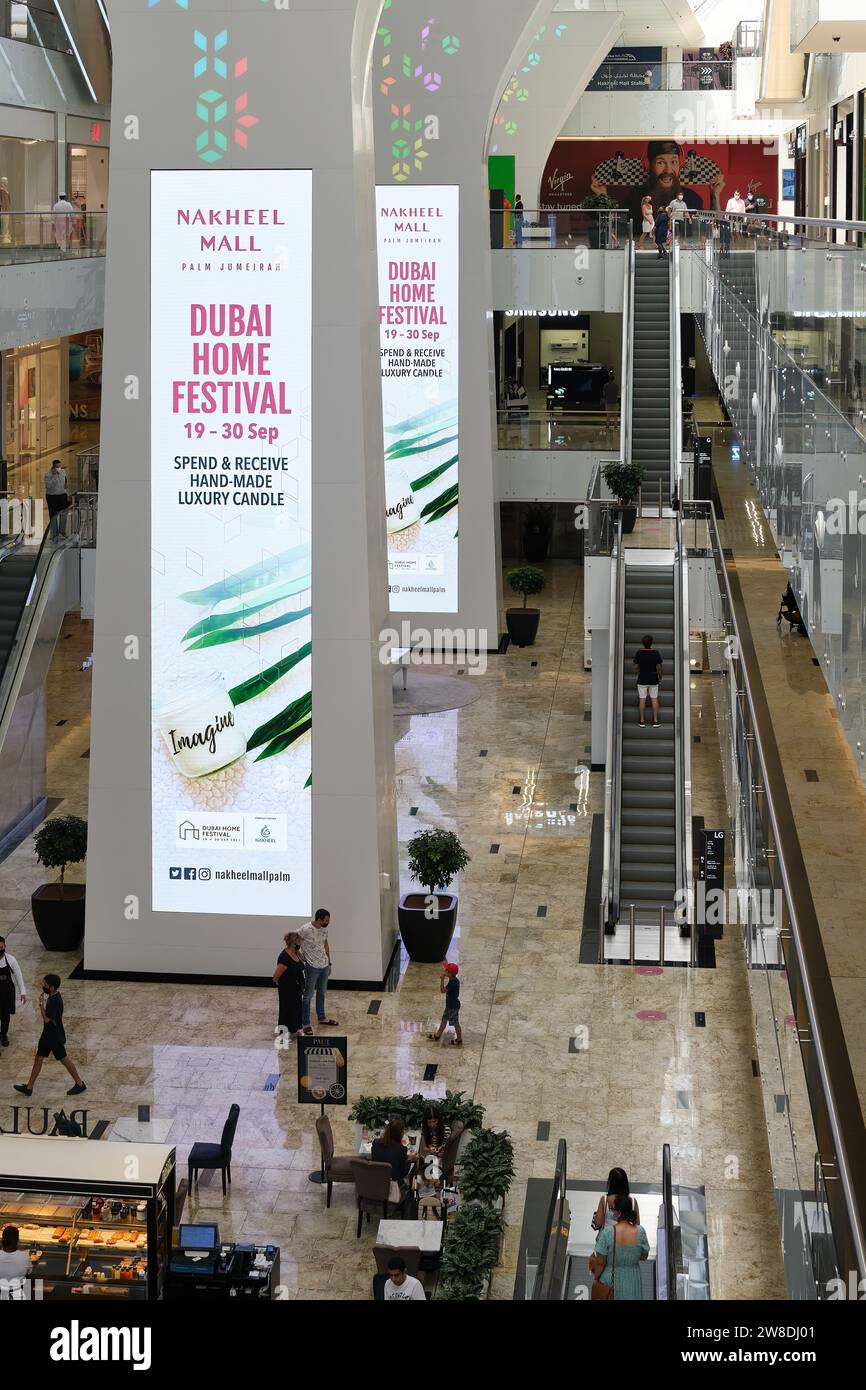
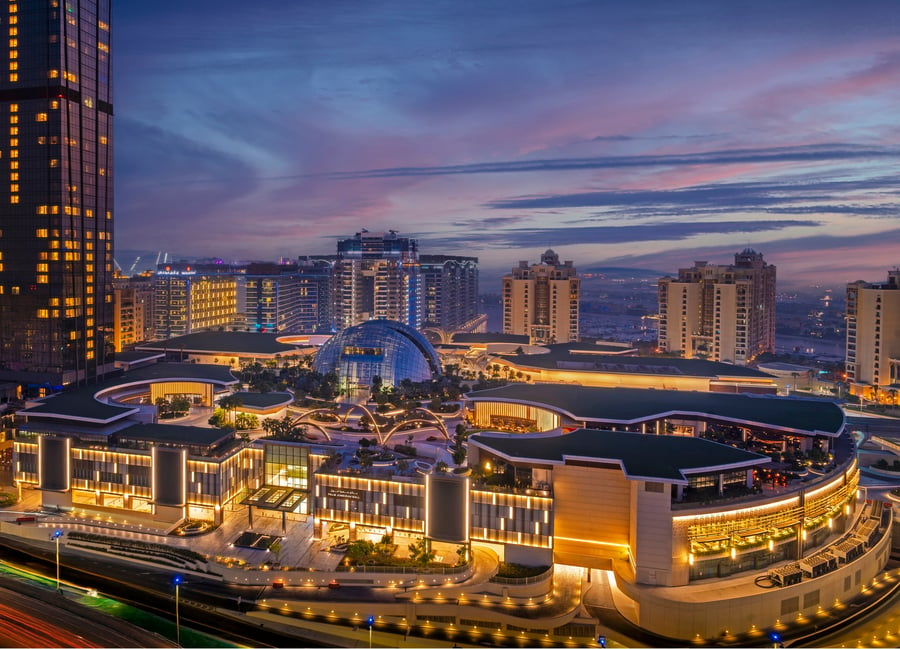
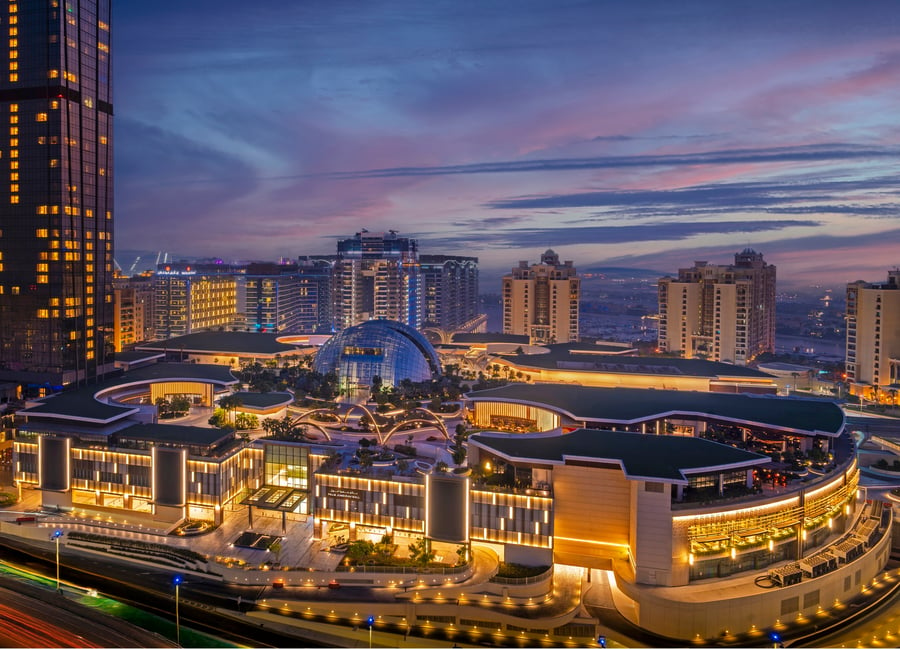
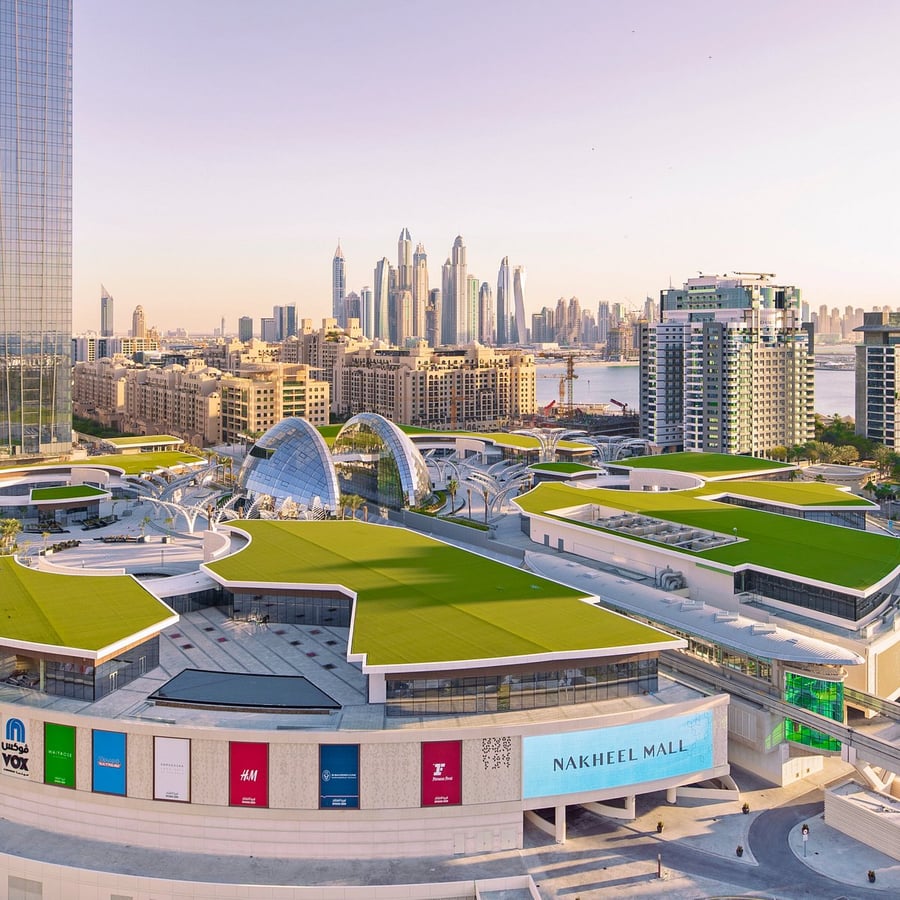
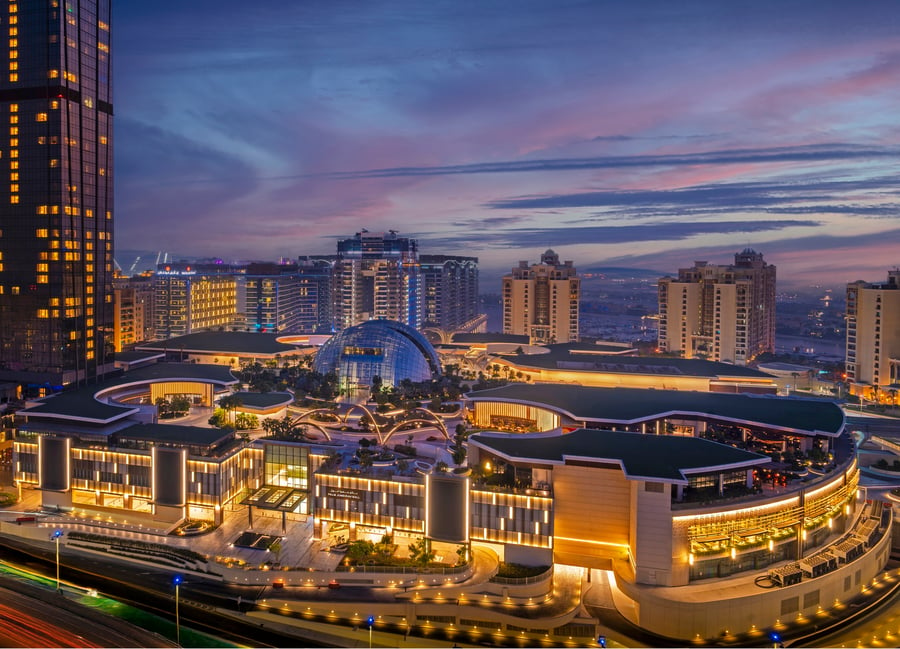
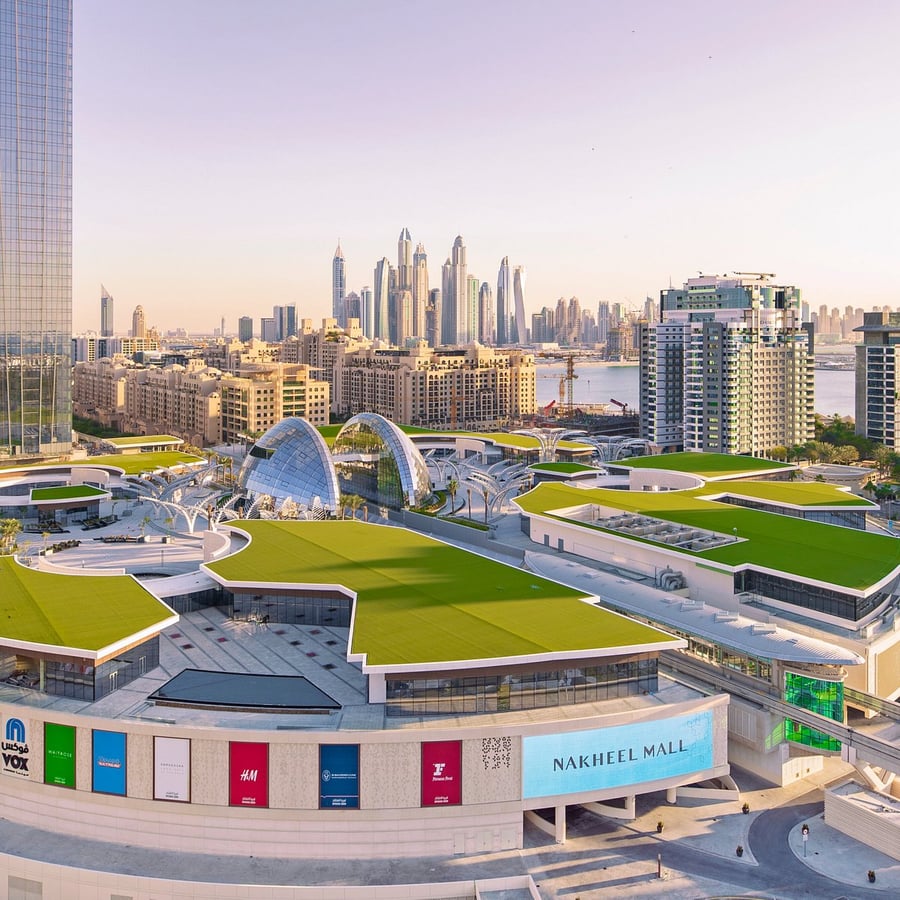
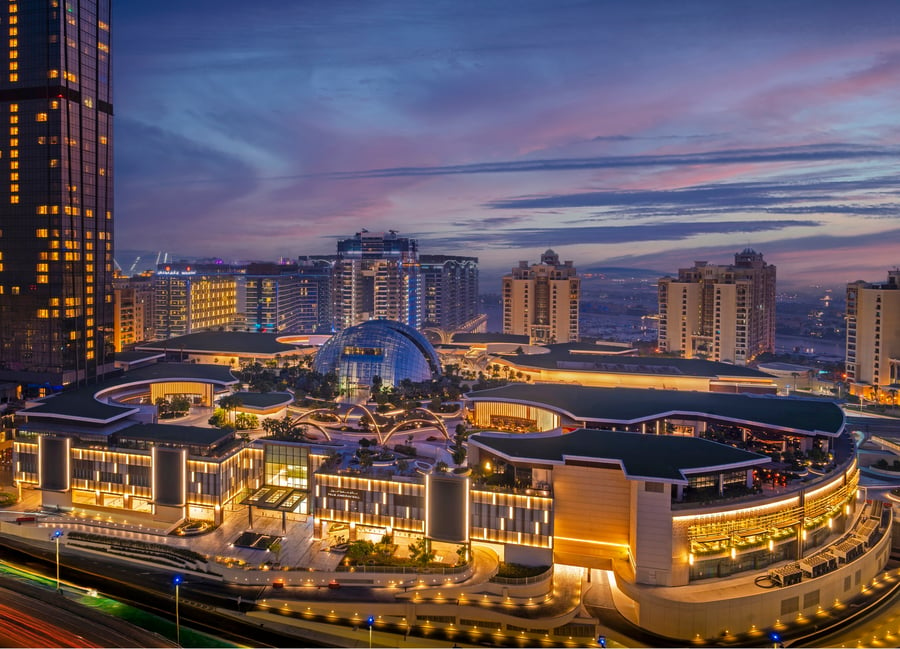
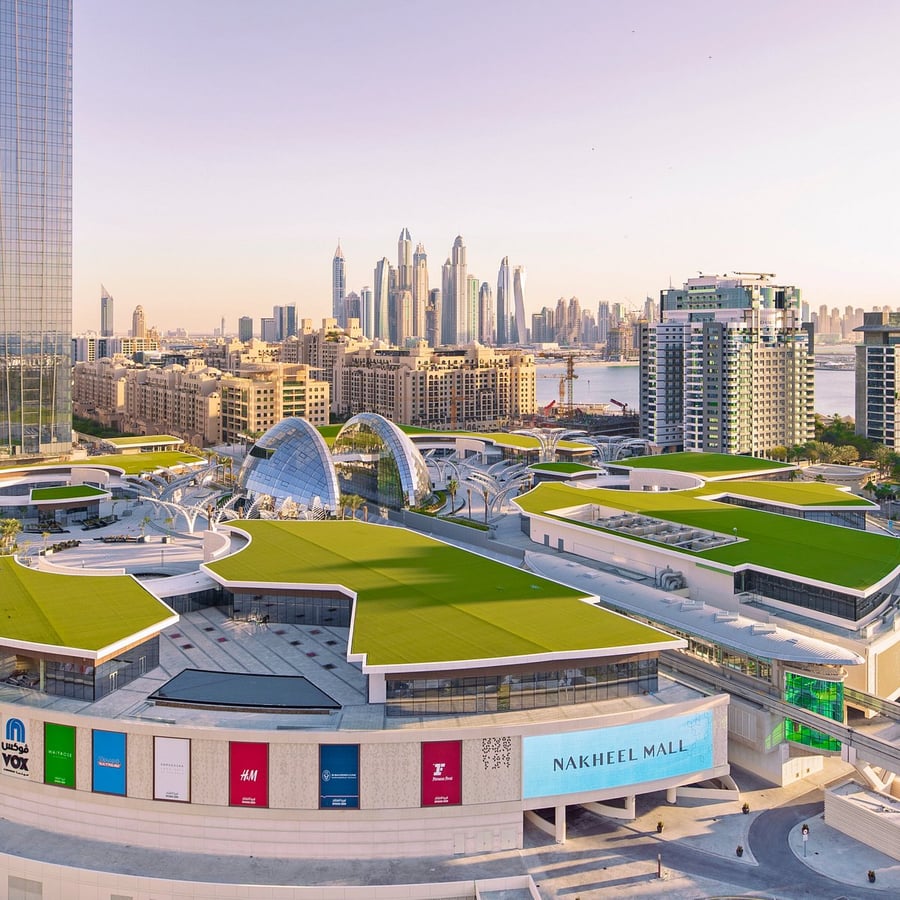
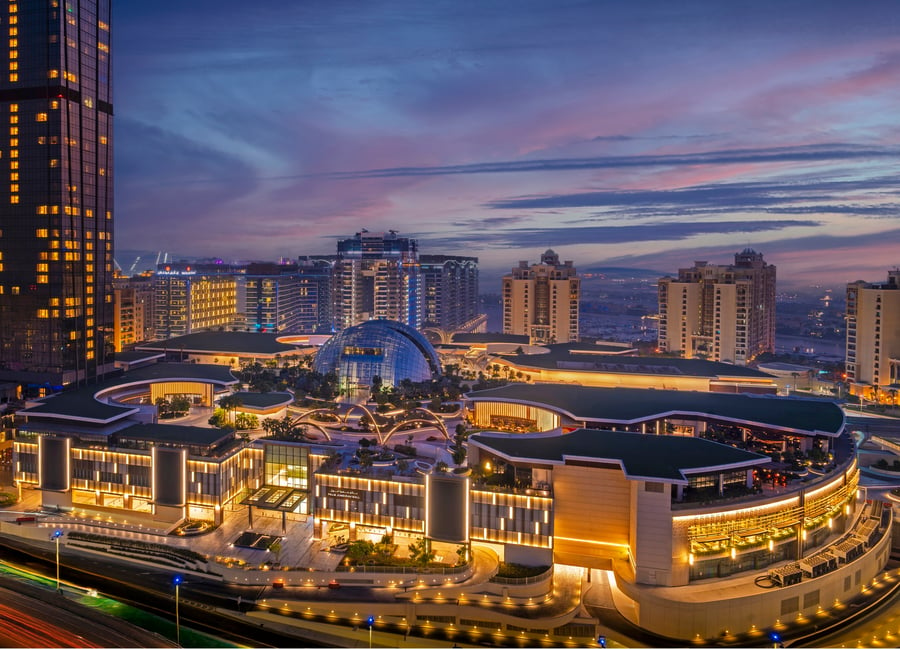
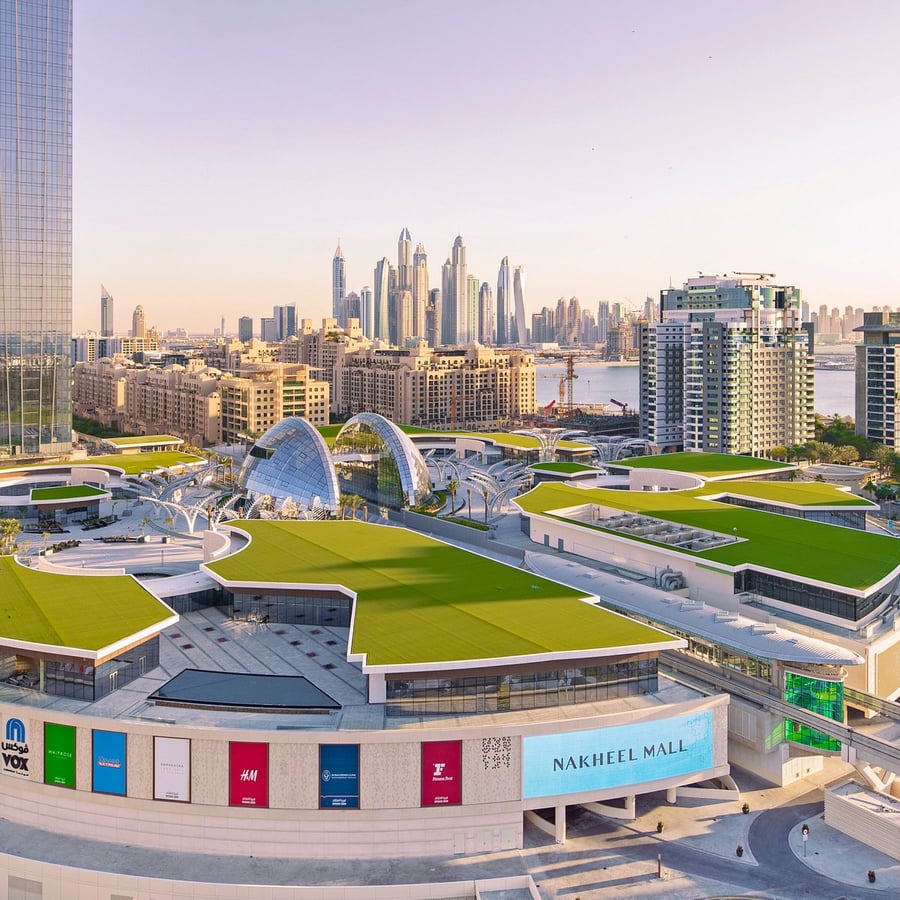
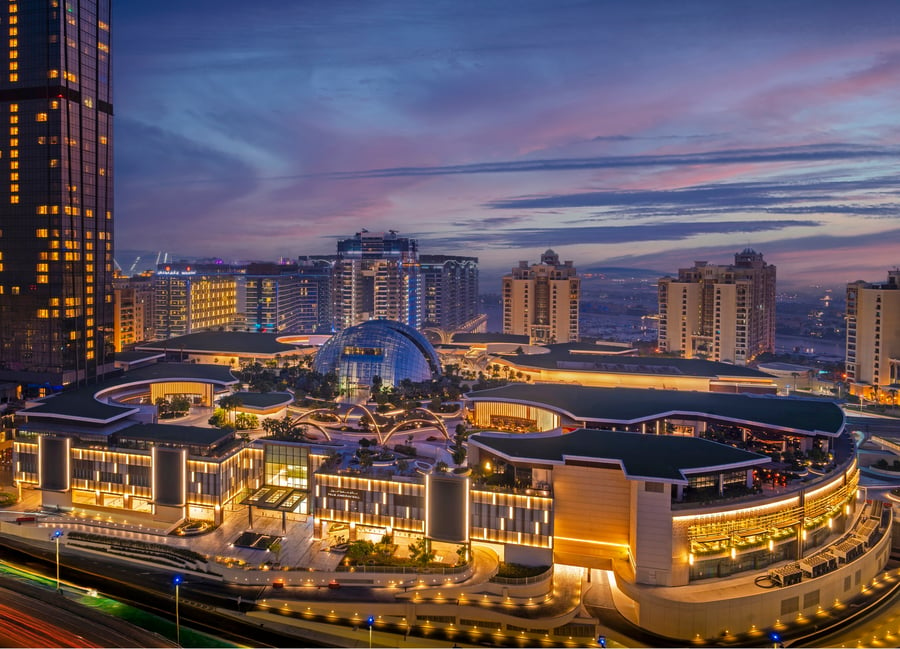
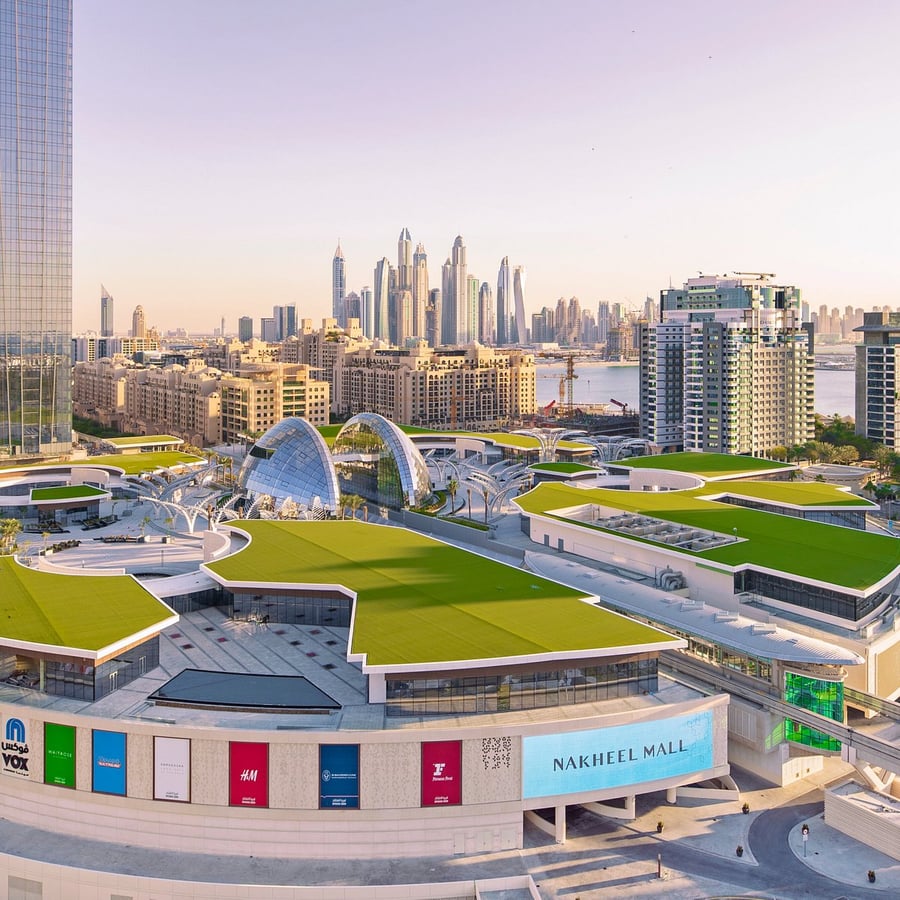
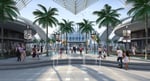
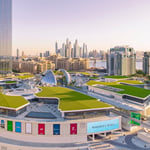
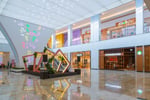
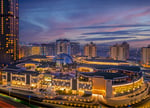
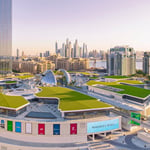
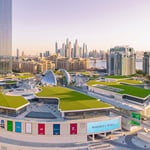
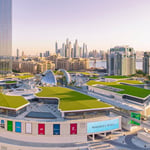
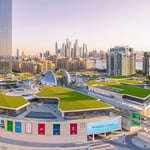
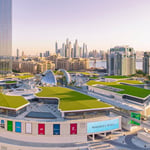
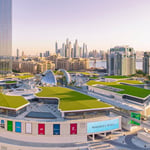
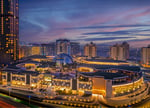
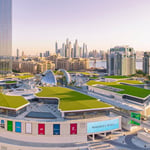
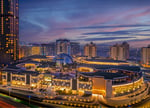
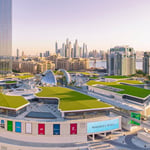
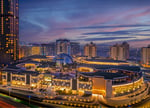
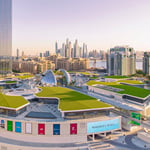
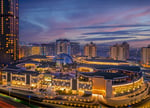
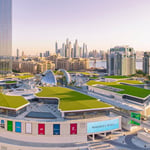
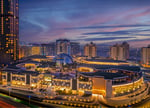
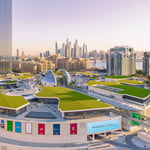
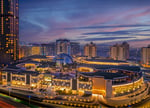
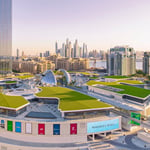
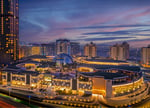
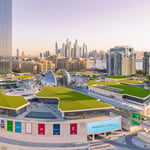
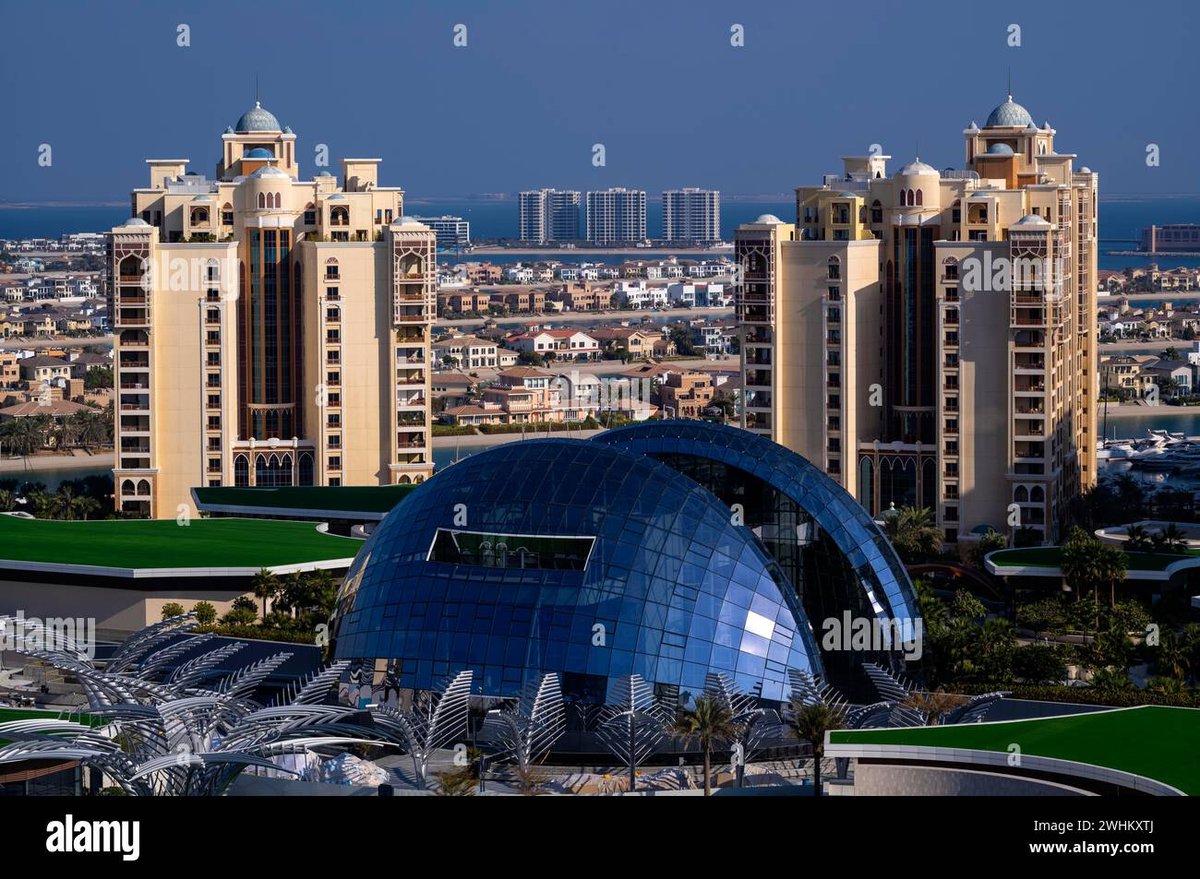
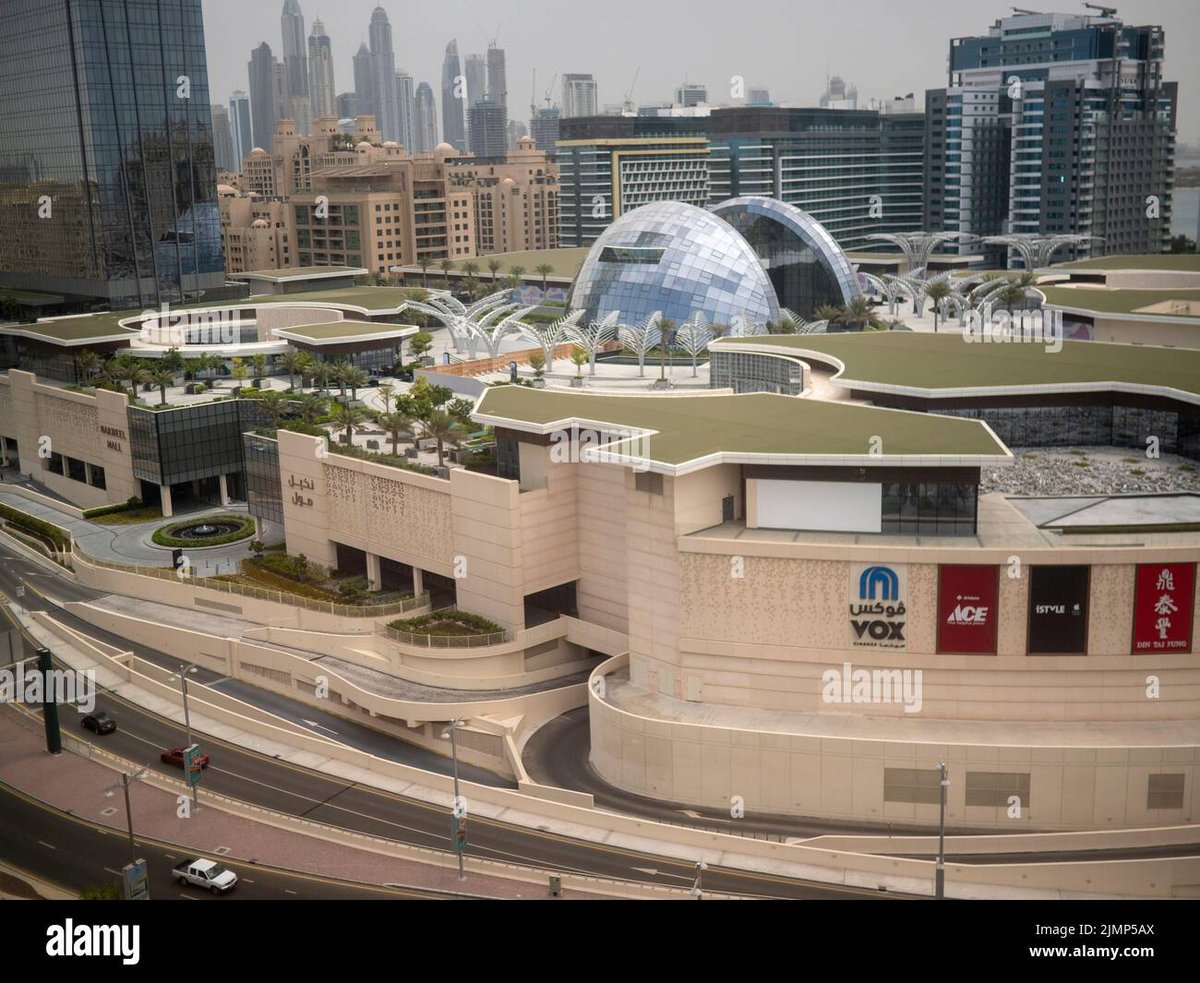
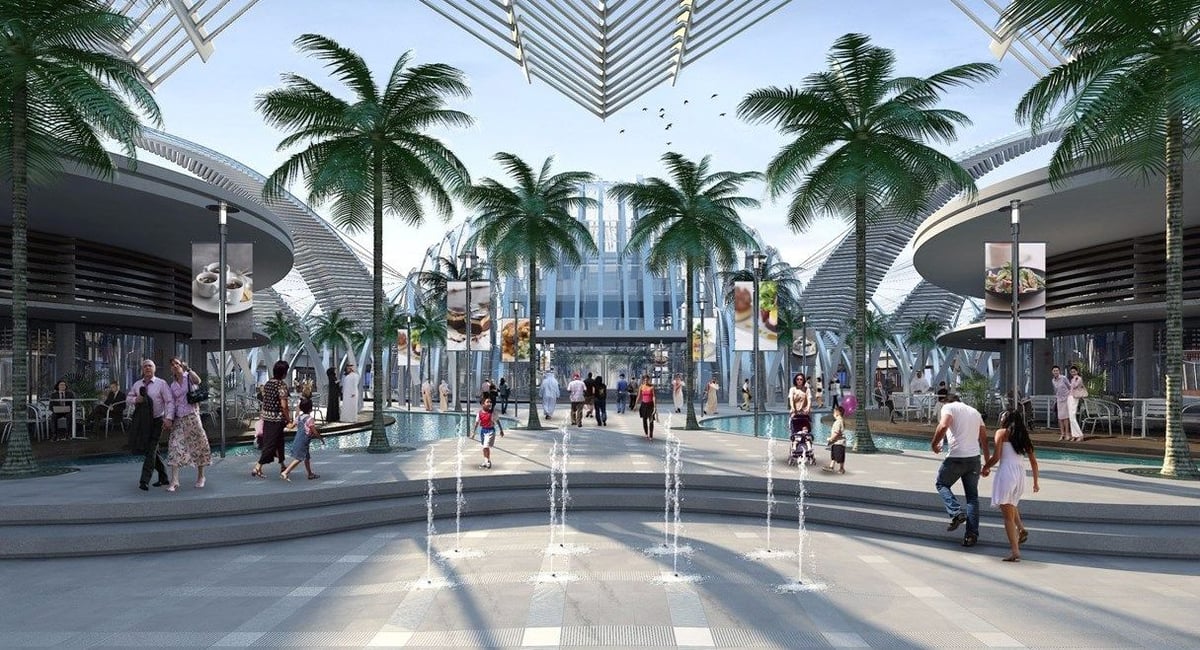
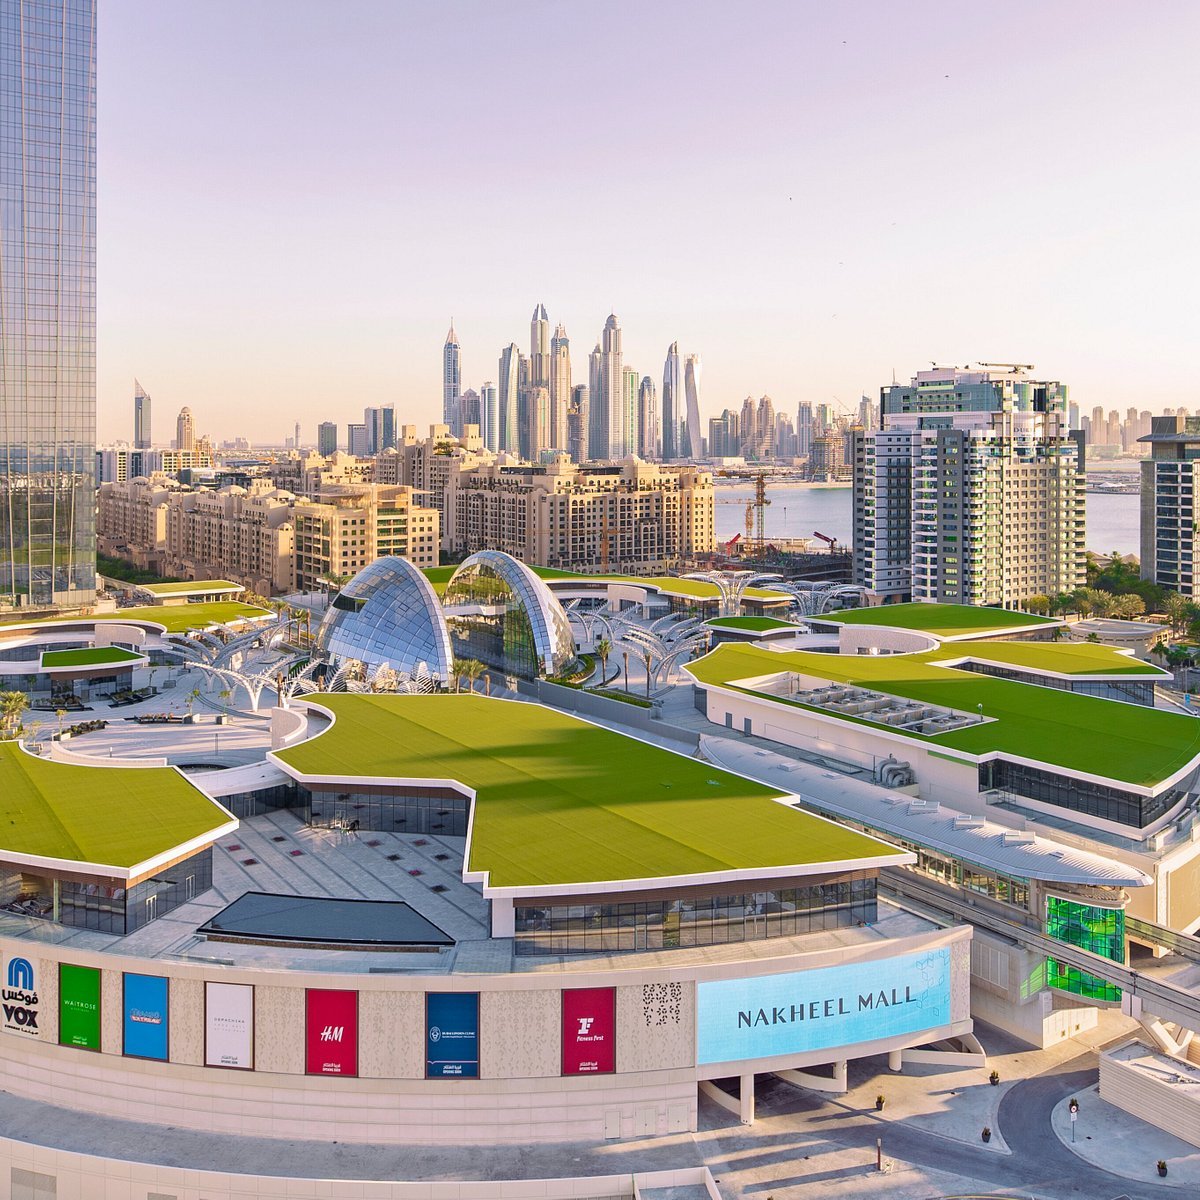
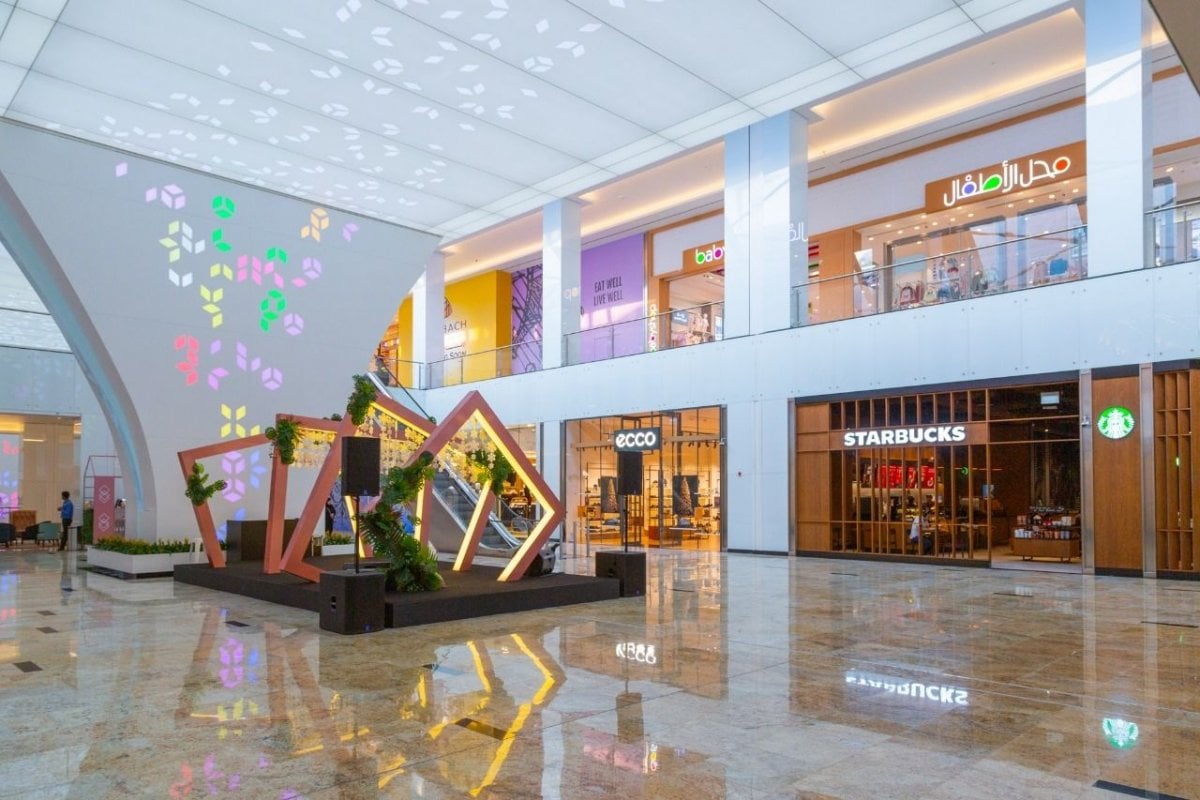
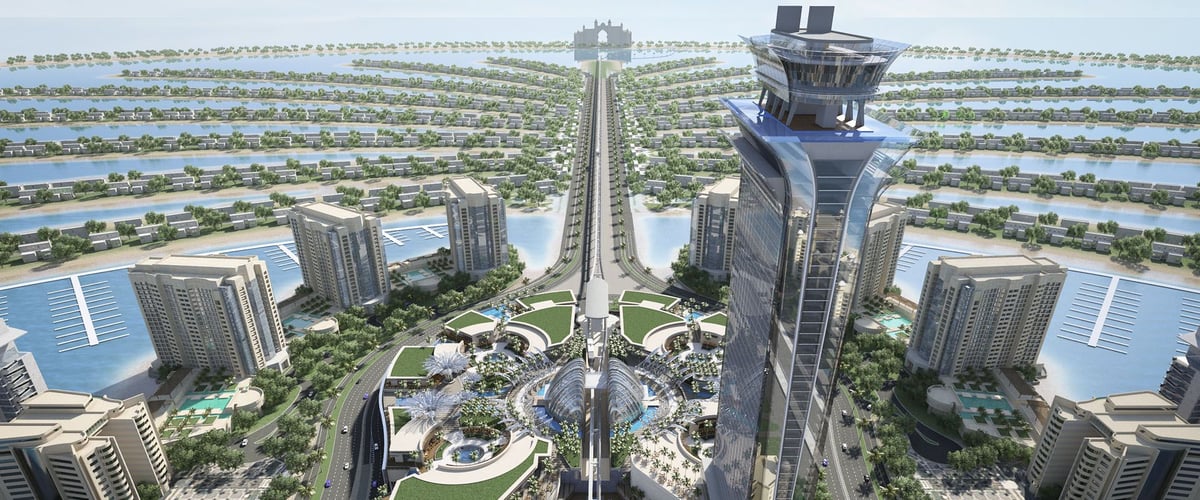
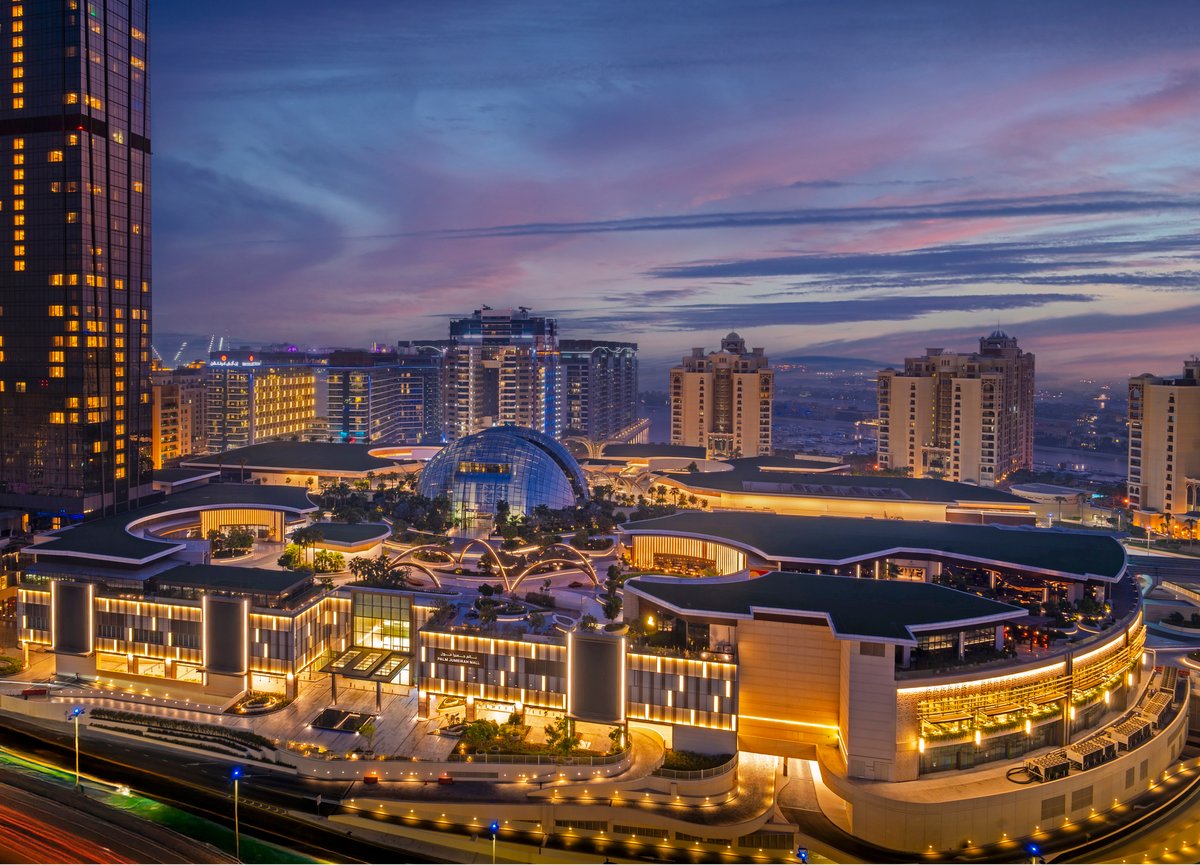
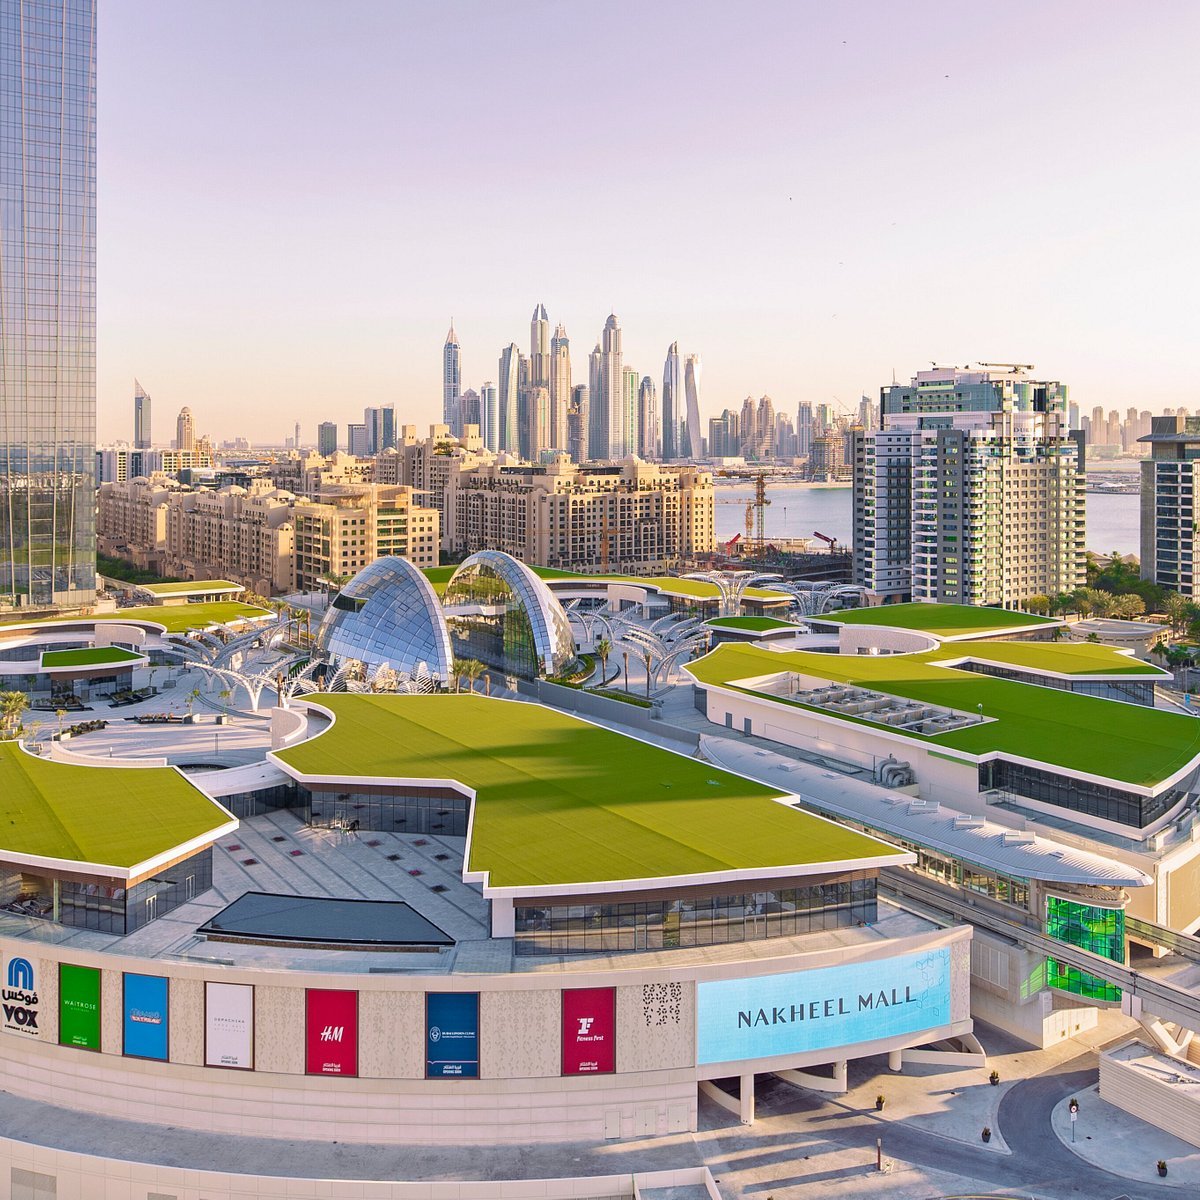
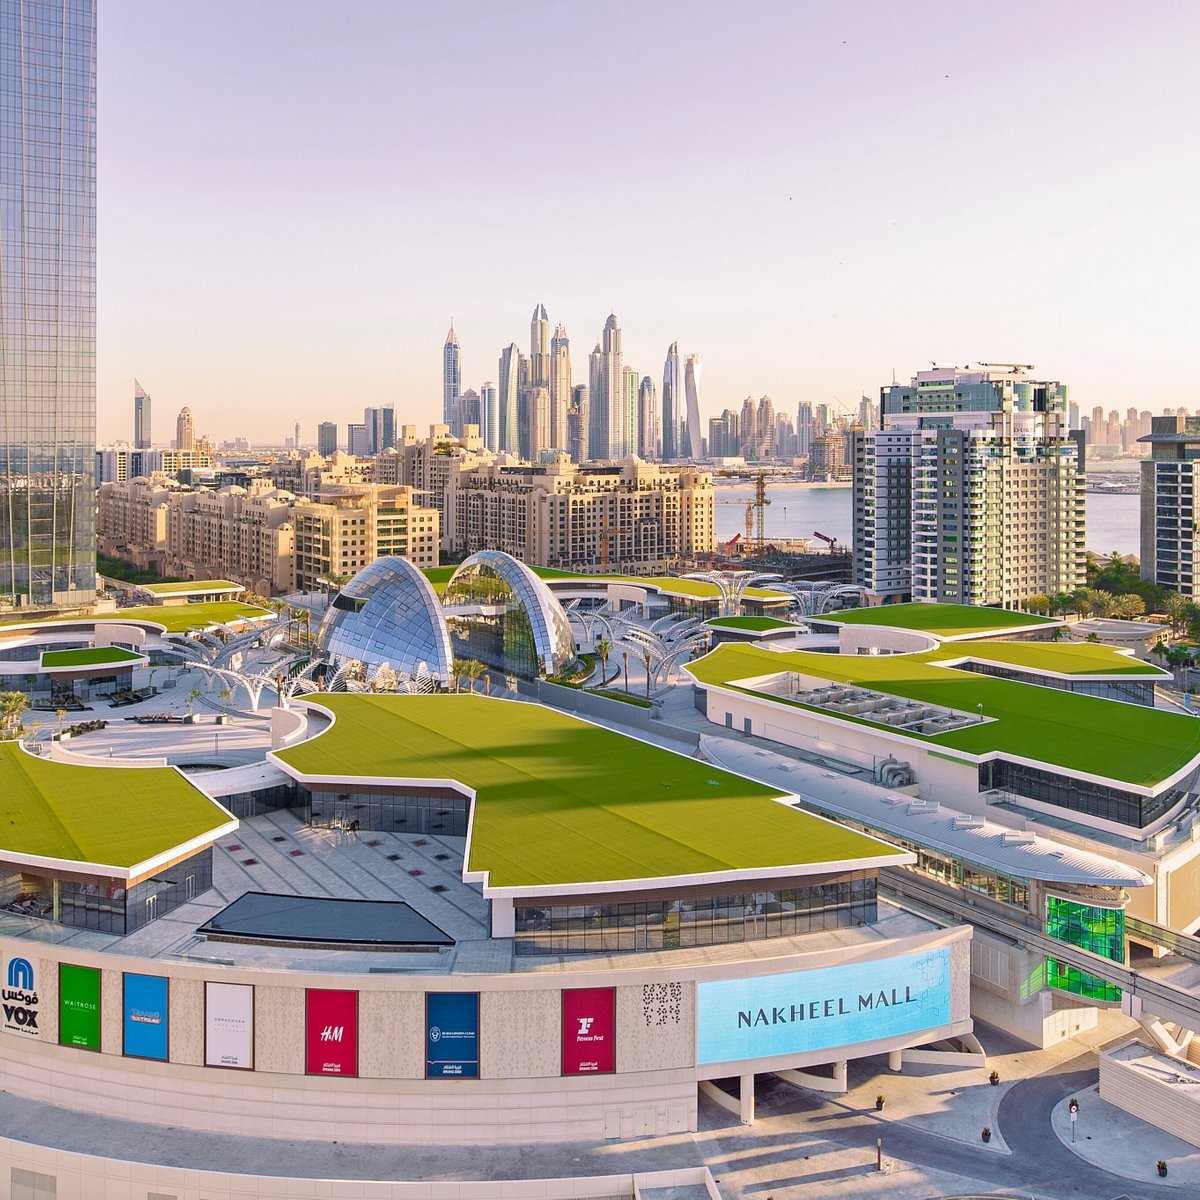
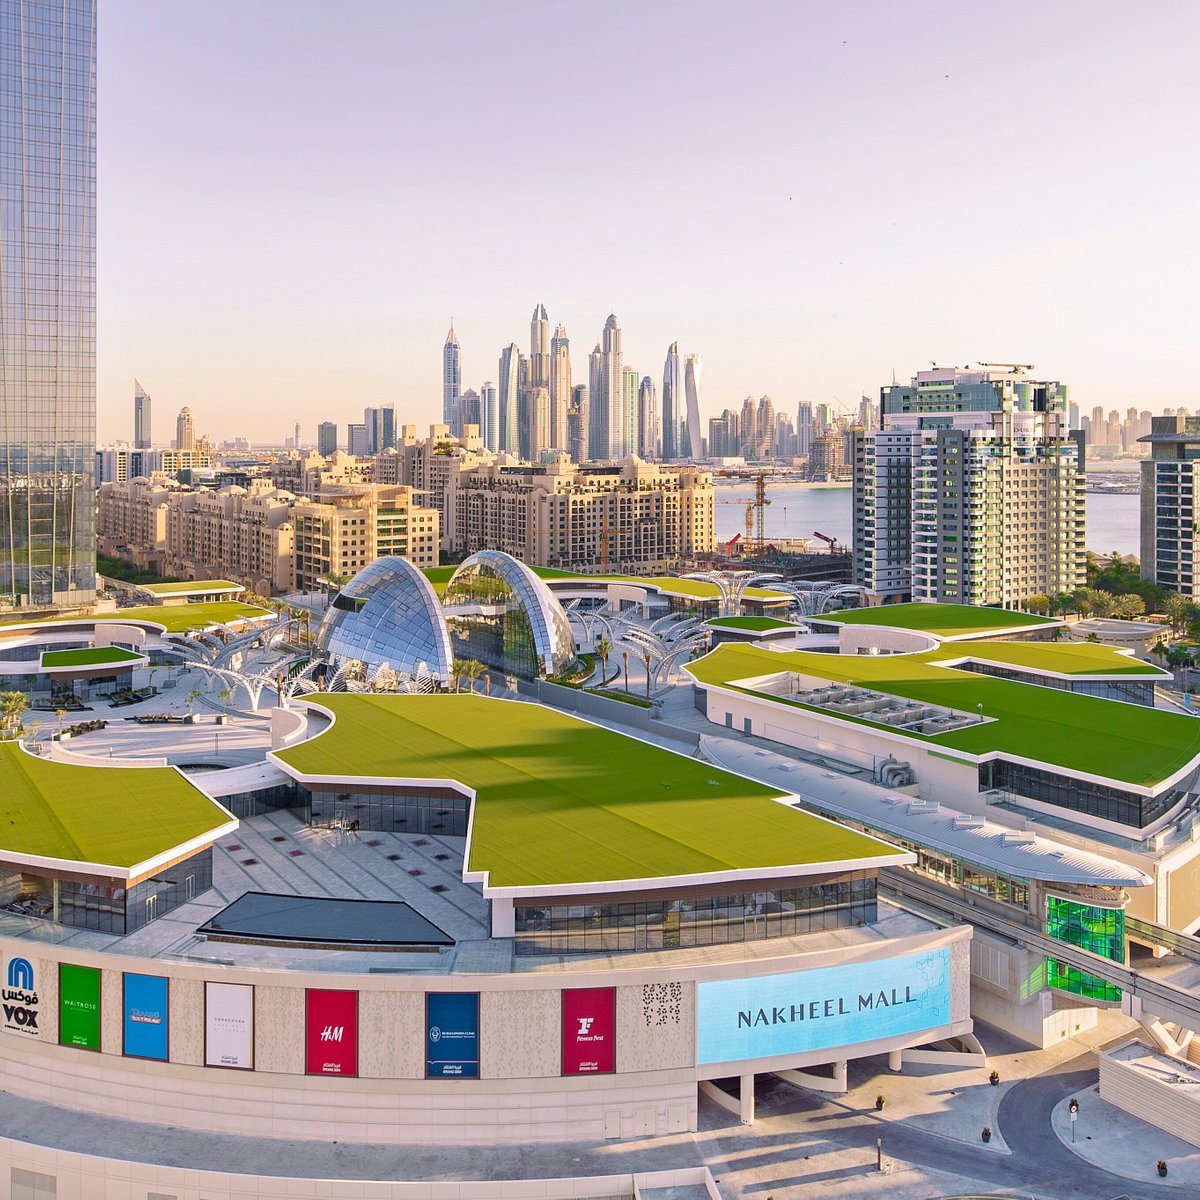
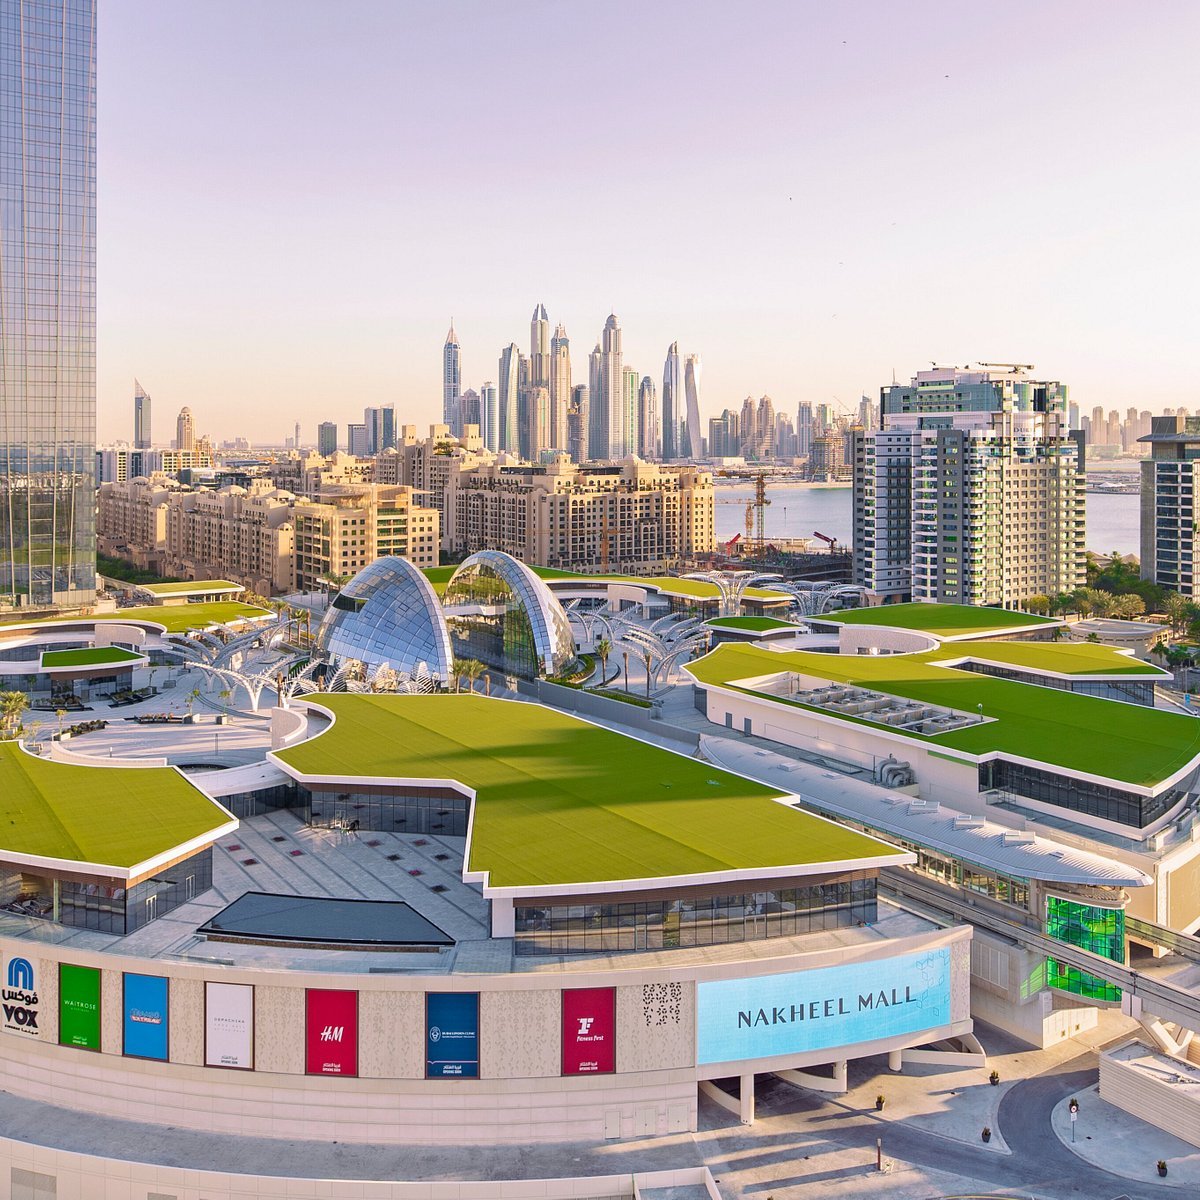
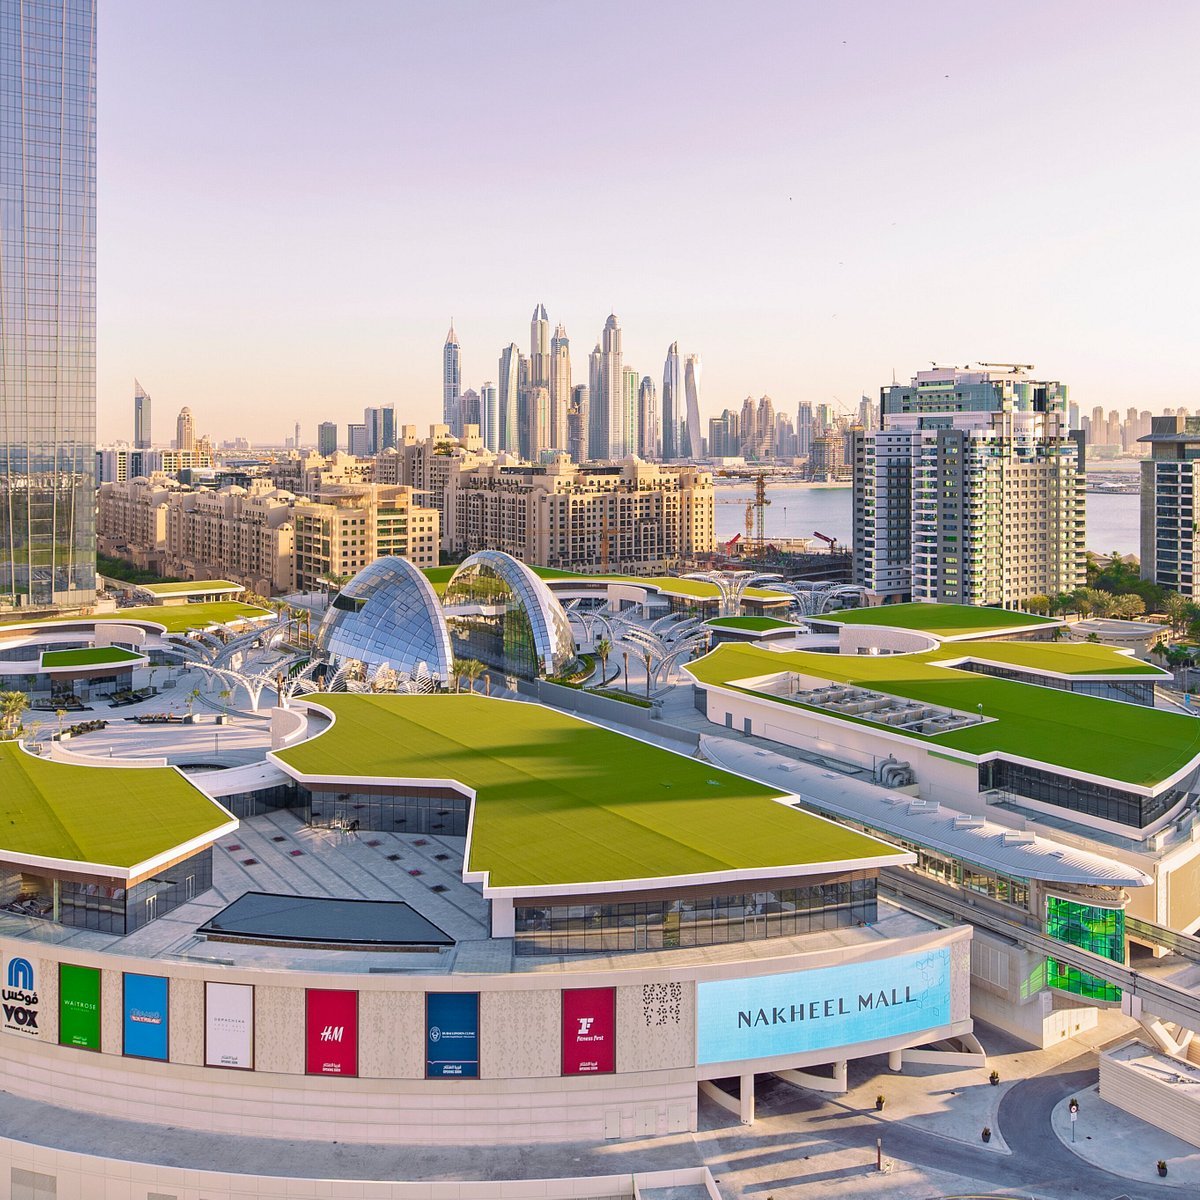
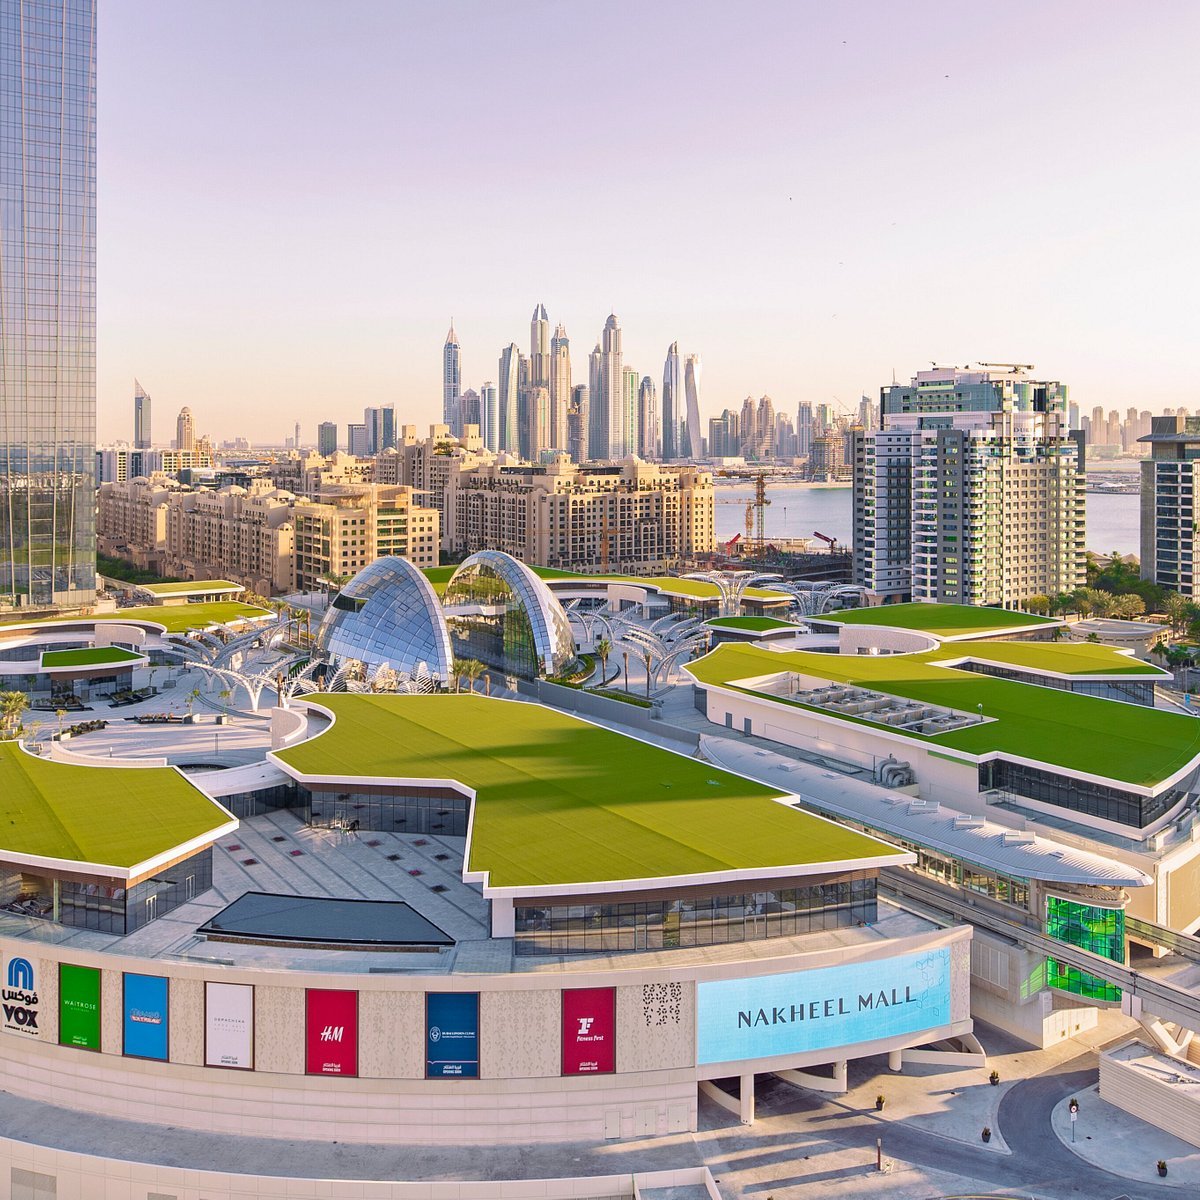
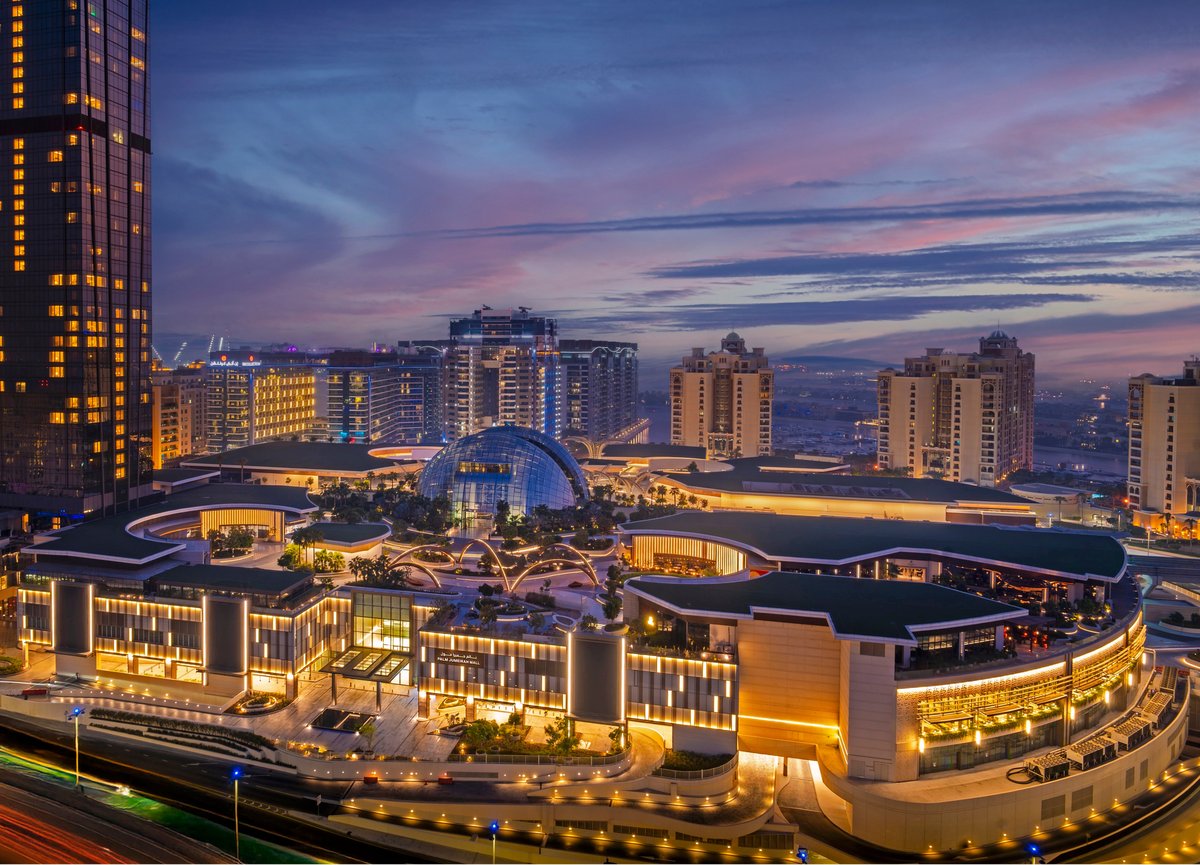
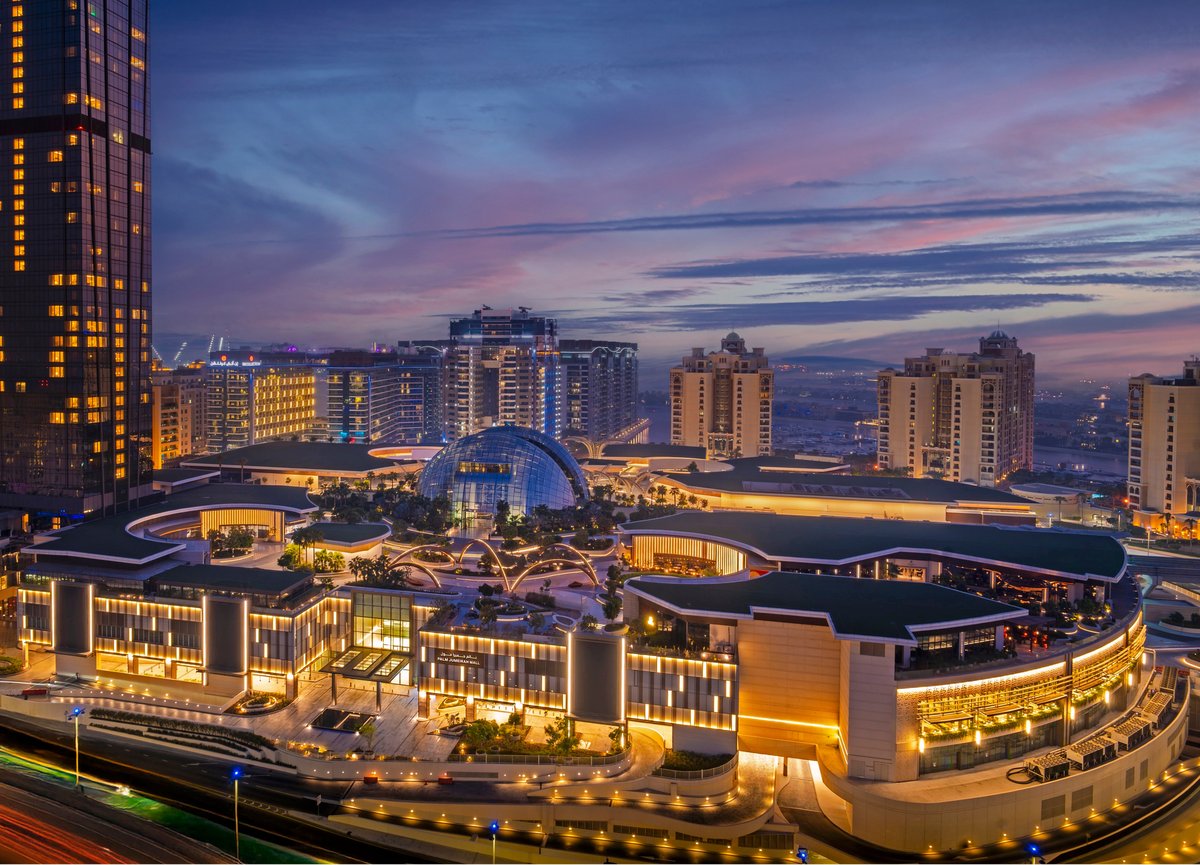
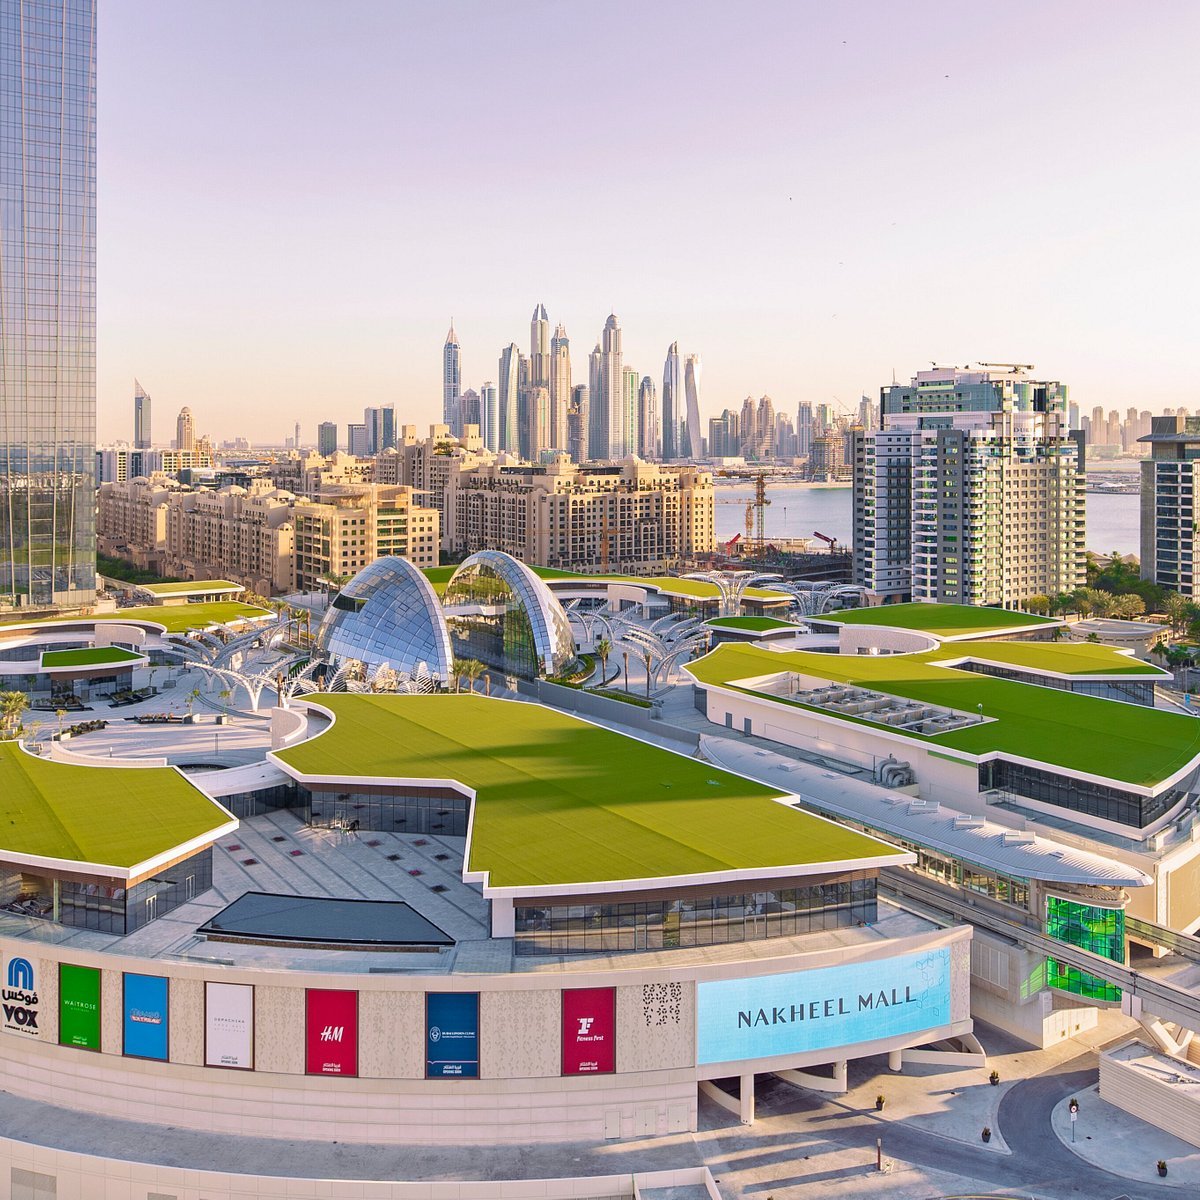
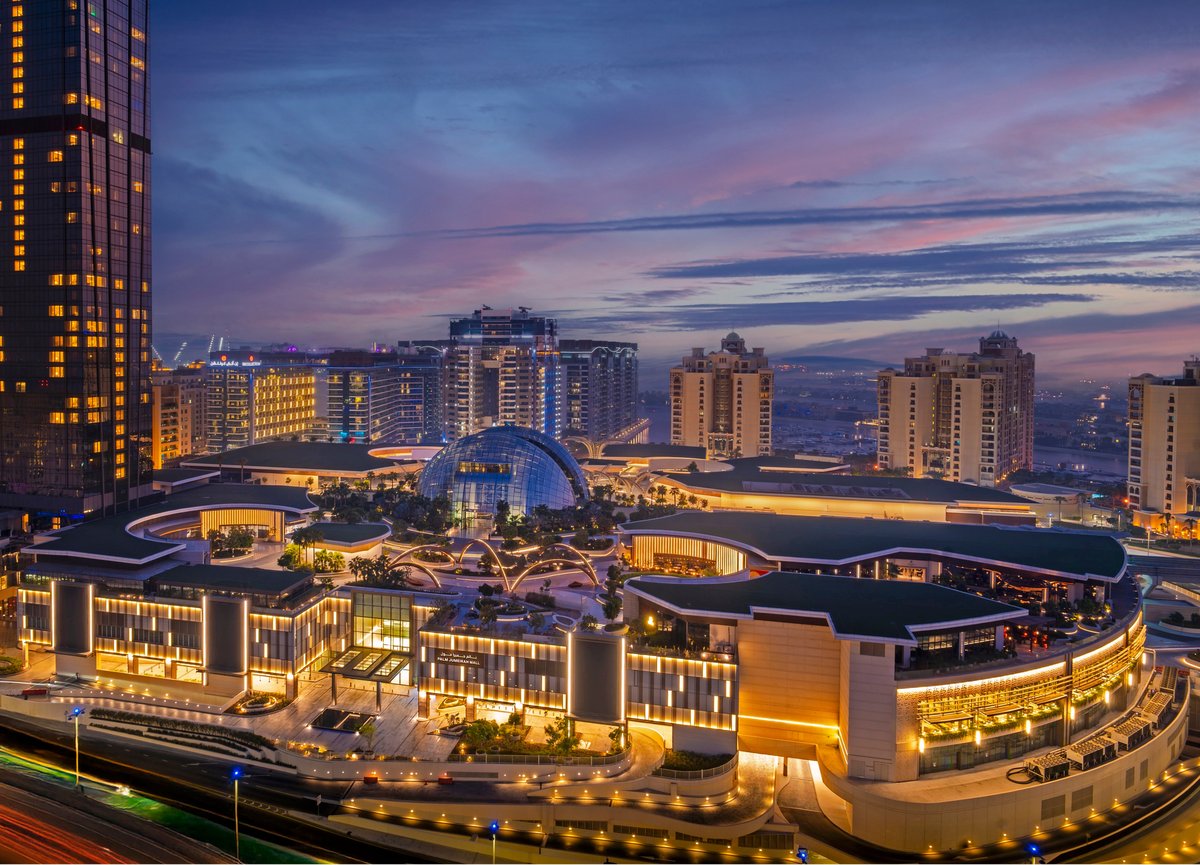
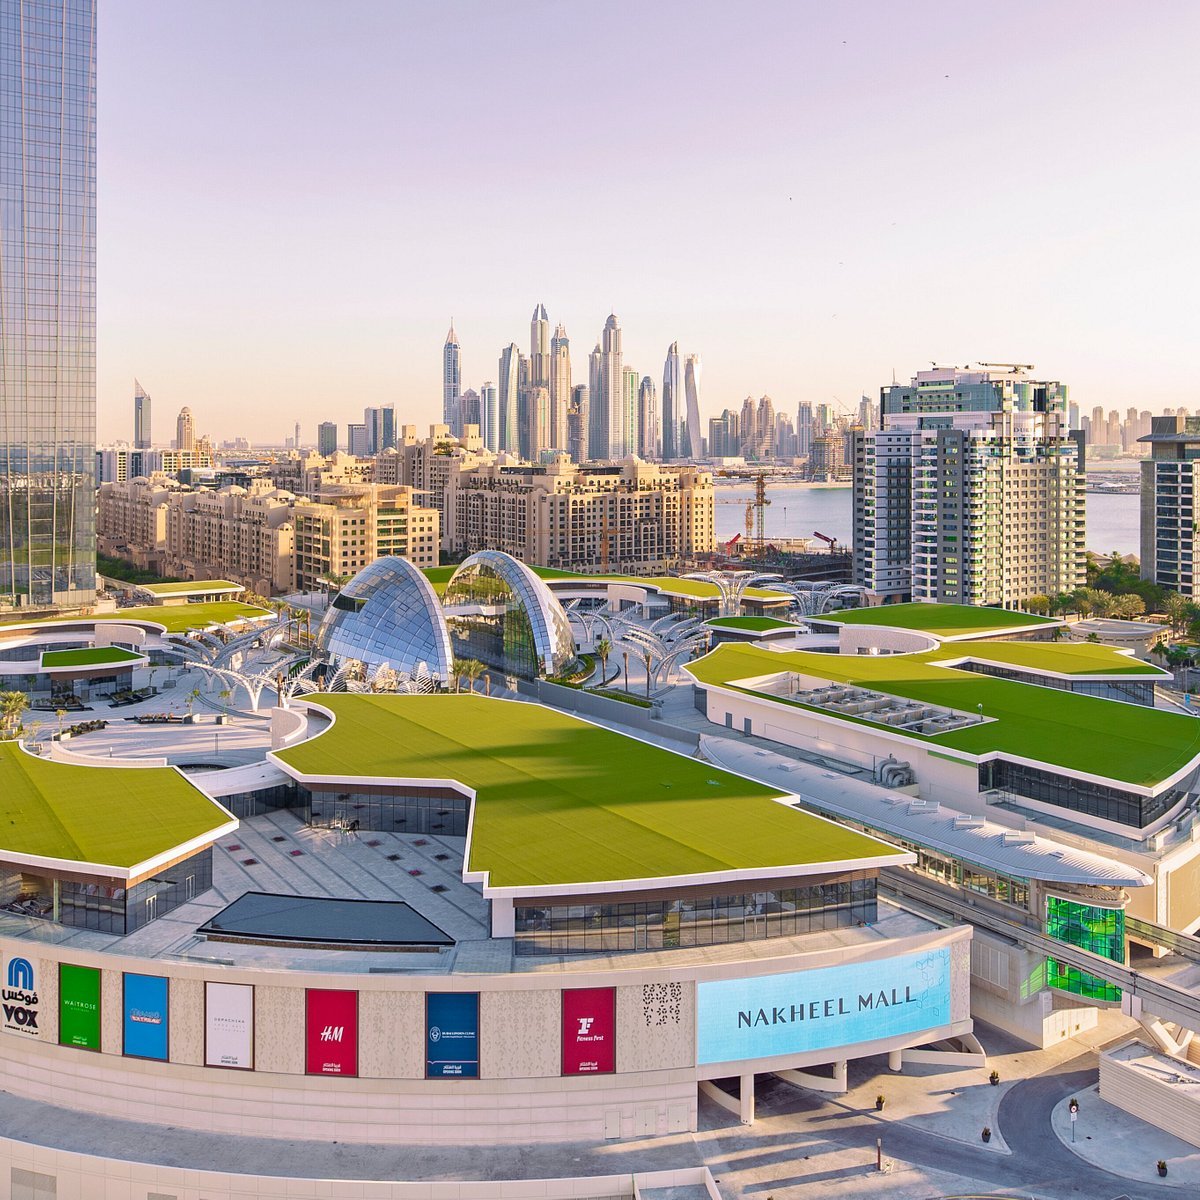
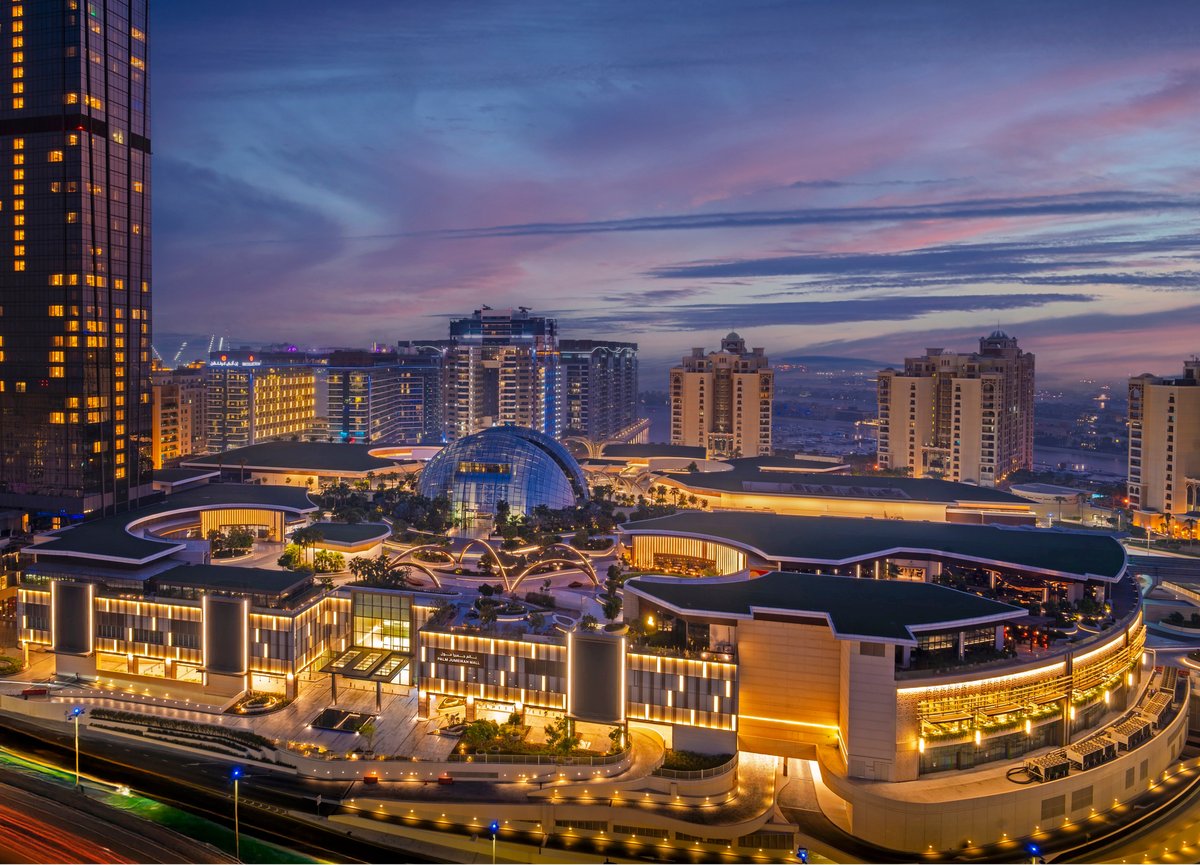
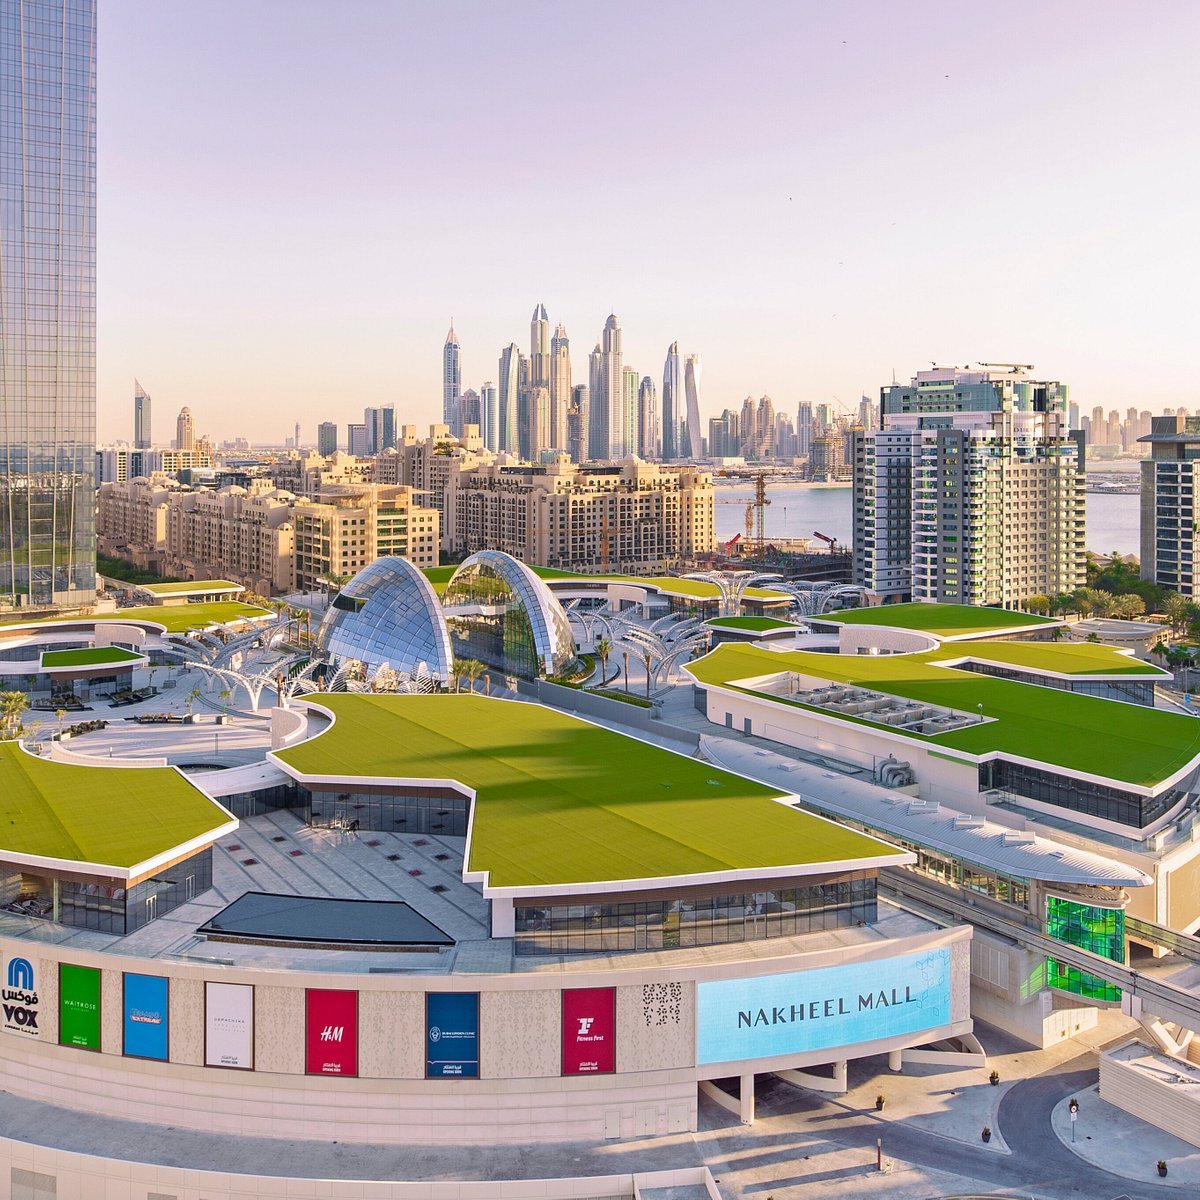
Nakheel Mall, located at the heart of Palm Jumeirah in Dubai, spans 418,000 square meters and serves as a premier retail, dining, and entertainment destination. Opened in 2019 and rebranded as Palm Jumeirah Mall in September 2025, it features over 300 stores across five levels, including anchor tenant Waitrose occupying 4,200 square meters, luxury fashion outlets, and diverse dining options in St. Regis Gardens with Michelin-starred and celebrity chef restaurants.
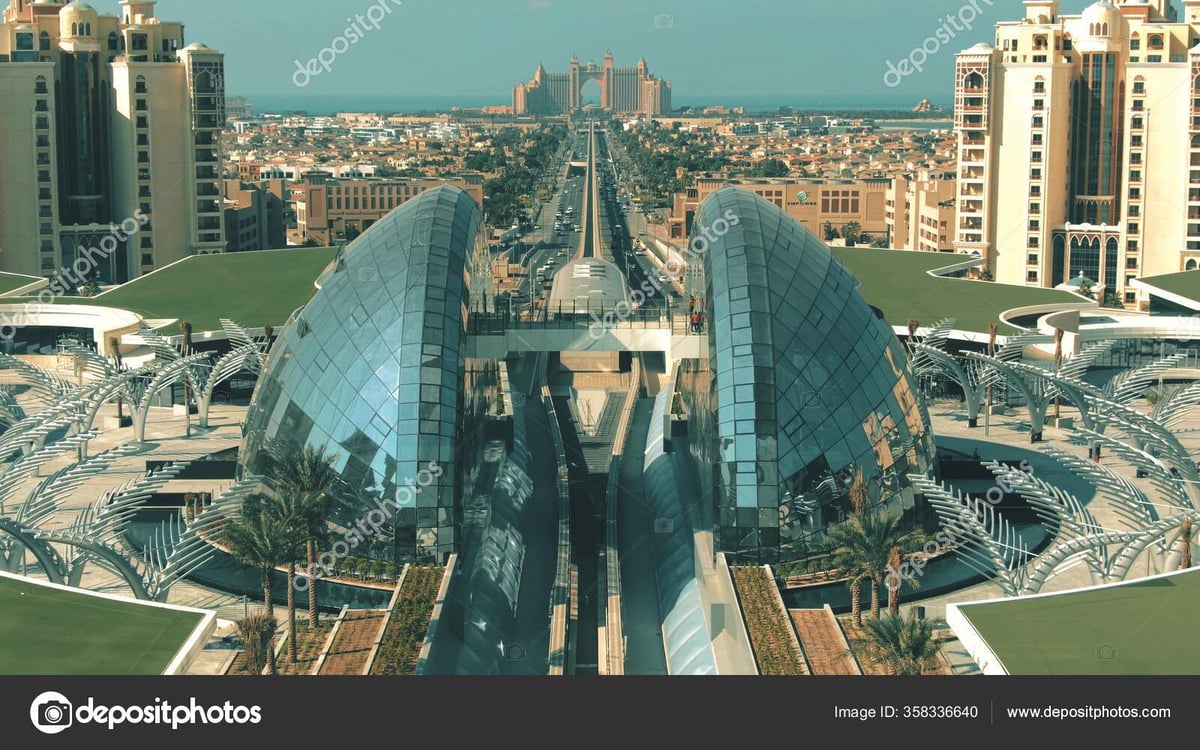
Entertainment includes VOX Cinemas, Trampo Extreme adventure park, and access to The View at The Palm observation deck on the rooftop. The mall benefits from direct Palm Monorail connectivity, extensive parking for 3,000 vehicles, and proximity to high-end residences and hotels like The St. Regis.
Occupancy rates align with Dubai's strong retail market, exceeding 95% as of H1 2025, supported by major operators maintaining 98% averages. Footfall is robust, drawing millions annually from affluent locals and tourists, with sales performance enhanced by experiential offerings.
Rent levels in prime Dubai malls range from AED 2,500 to 4,000 per square meter annually, reflecting stable increases of 7-8% year-over-year amid market growth. The tenant mix emphasizes luxury and lifestyle, with 80% diversity across categories, including 15 unique concepts to attract high-net-worth visitors.
Market position strengthens as it fills a previous retail gap in Palm Jumeirah, an area with over 24,000 luxury homes and high expatriate density.
Accessibility is excellent via road and rail, though traffic congestion during peak tourist seasons poses challenges.
Demographic profile targets high-income expats (average household income AED 500,000+), families, and international tourists, contributing to above-average spending per visit.
Operational quality is high, with modern infrastructure and integrated leisure zones boosting dwell time. However, competition from super-regional malls like Dubai Mall (20-minute drive) pressures mid-tier tenants, and market saturation in Dubai's 70+ malls risks footfall dilution. Potential risks include economic sensitivity in luxury segments and aging monorail infrastructure.
Leasing advantages include flexible terms for pop-ups and long-term anchors, with turnover rents tied to strong sales metrics averaging AED 10,000+ per square meter yearly in similar venues.
Overall, it offers solid performance for premium retailers but requires differentiation in a competitive landscape.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
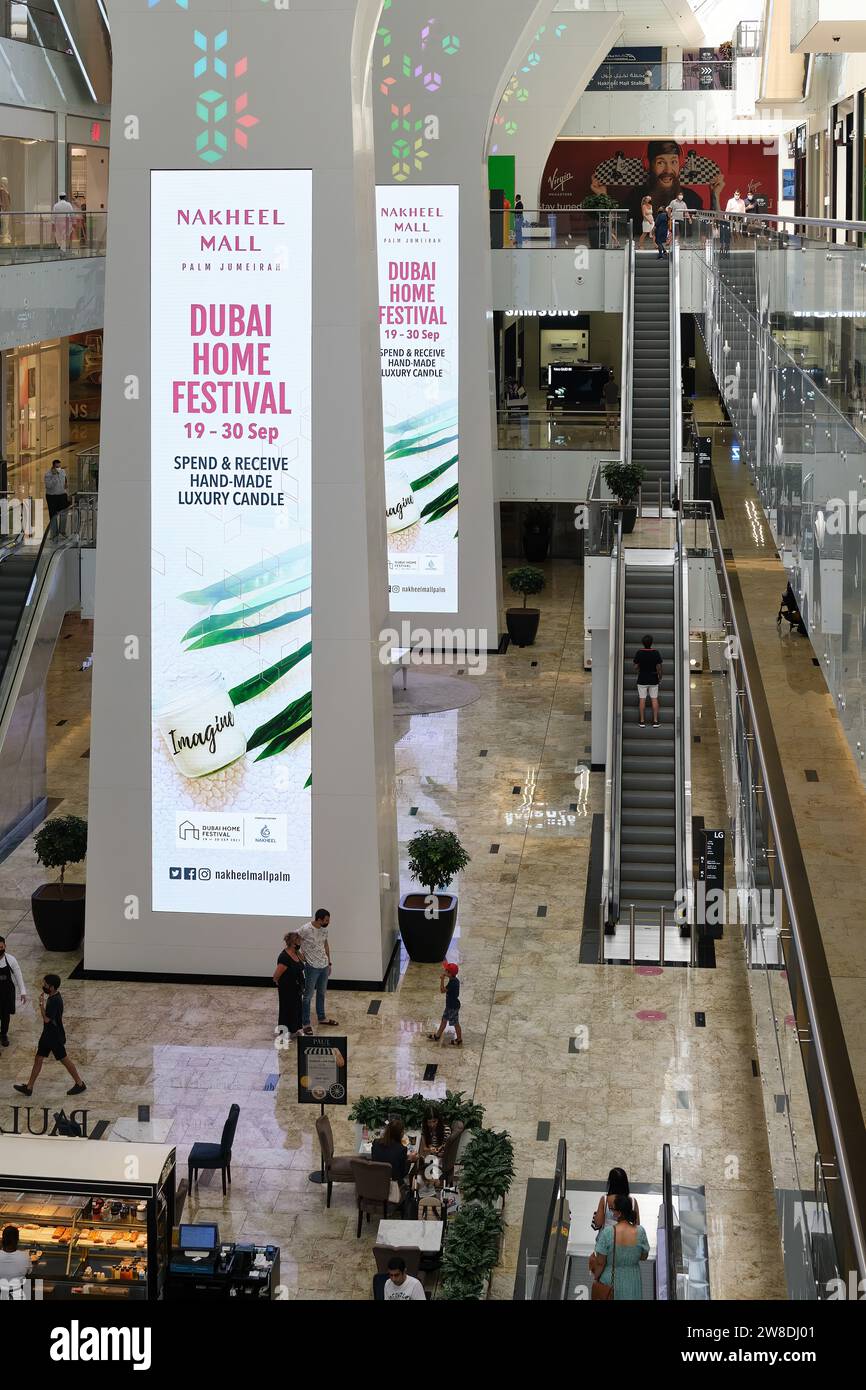
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 12:00 AM |
| Saturday | 10:00 AM — 12:00 AM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
Palm Jumeirah's demographic is predominantly affluent expatriates and high-net-worth individuals, with over 70% foreign residents in households earning above AED 500,000 annually, alongside tourists from Europe, Russia, and the Middle East. Family-oriented with young professionals, the area supports high spending on luxury goods and dining, estimated at AED 1,500 per visitor. Footfall exceeds 5 million annually, driven by monorail access and events, though seasonal peaks strain capacity. Weakness lies in limited local population (24,000 homes) relying on tourism, vulnerable to global travel fluctuations; data from Dubai Tourism reports 82% hotel occupancy in 2025 boosting visits but exposing to economic downturns.
Competition and Market Factors
Faces stiff competition from Dubai Mall (1.2 million sqm, 100 million footfall) and Mall of the Emirates, both 20-30 minutes away, dominating 66% of Dubai's mall space and tourist spend. Nakheel Mall differentiates via localized luxury and Palm views, capturing 20-25% of Jumeirah retail spend per Cushman & Wakefield reports. Market saturation with 70+ malls in Dubai leads to 10% vacancy in secondary venues; strengths include underserved Palm area pre-2019, now with 98% occupancy. Risks involve e-commerce growth eroding 15% of physical sales and regional geopolitical tensions impacting tourism.
Lease Terms and Operational Quality
Rents average AED 3,000 per sqm/year for prime spaces, with escalations of 5-7% annually and turnover components up to 10% of sales, per JLL 2025 retail outlook. Flexible leasing for 3-10 year terms suits anchors like Waitrose; incentives include fit-out contributions up to 30% for select tenants. Operational strengths: Modern HVAC, 24/7 security, and digital integration for 95% uptime. Challenges: High utility costs (AED 50/sqm/month) and aging monorail (built 2009) causing occasional disruptions; infrastructure upgrades needed to maintain appeal amid Dubai's AED 855 billion shopping center market value.
Building Details
Detailed Market Analytics
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Dubai
Discover more shopping centers in Dubai.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city