
Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
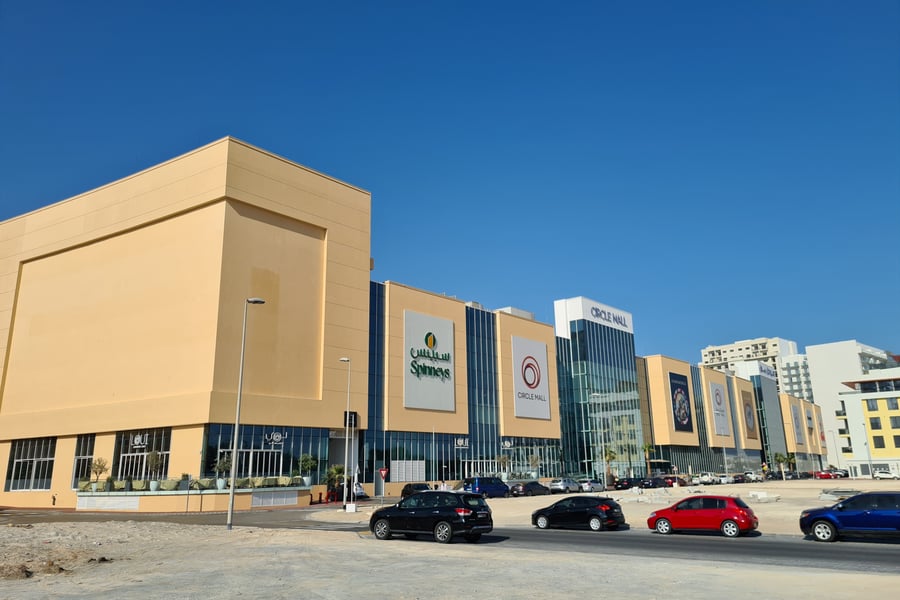
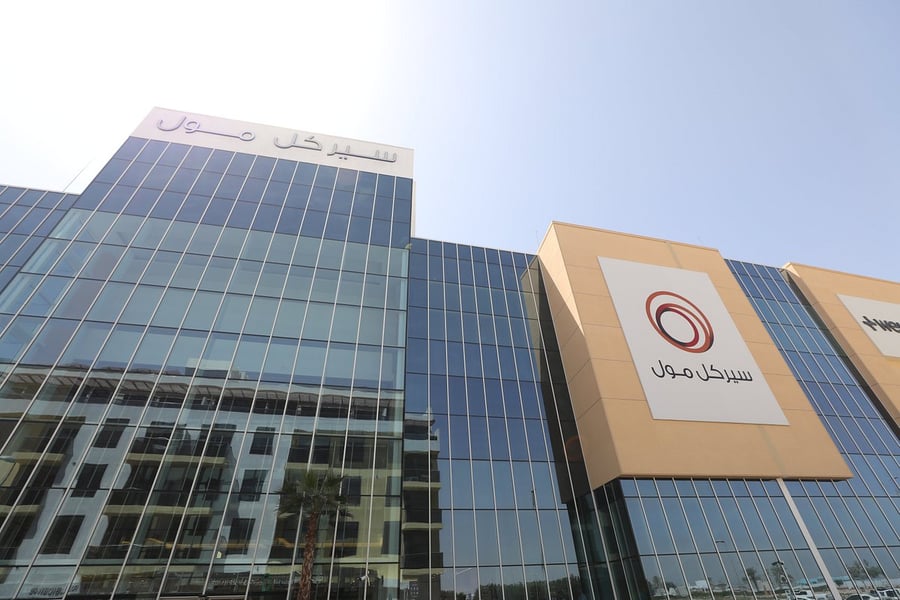
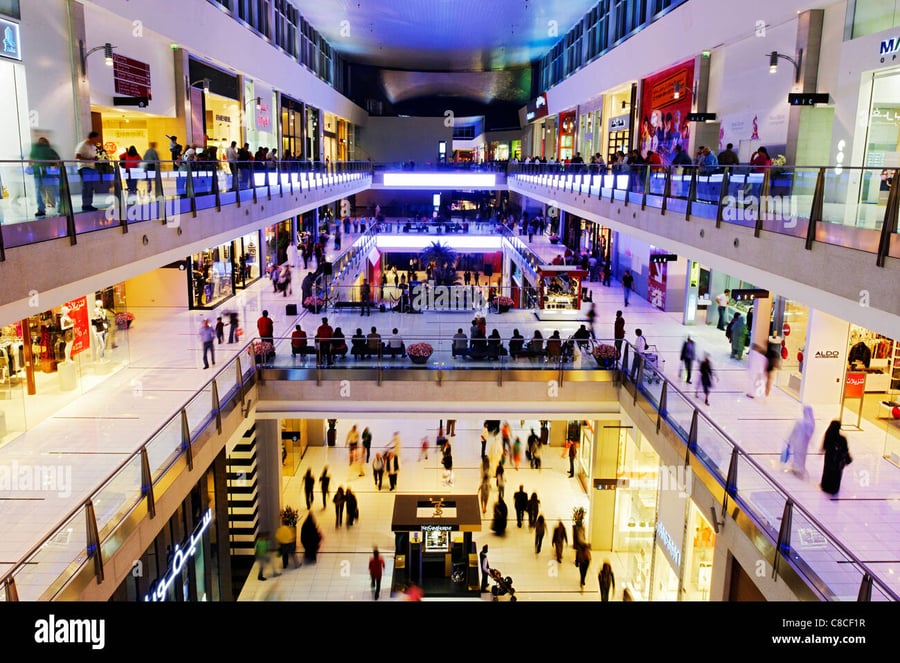
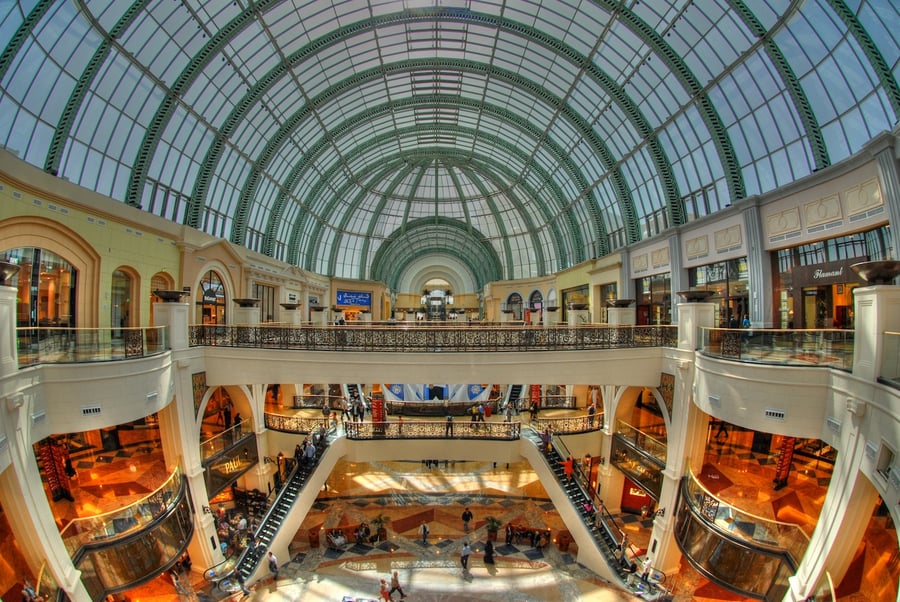
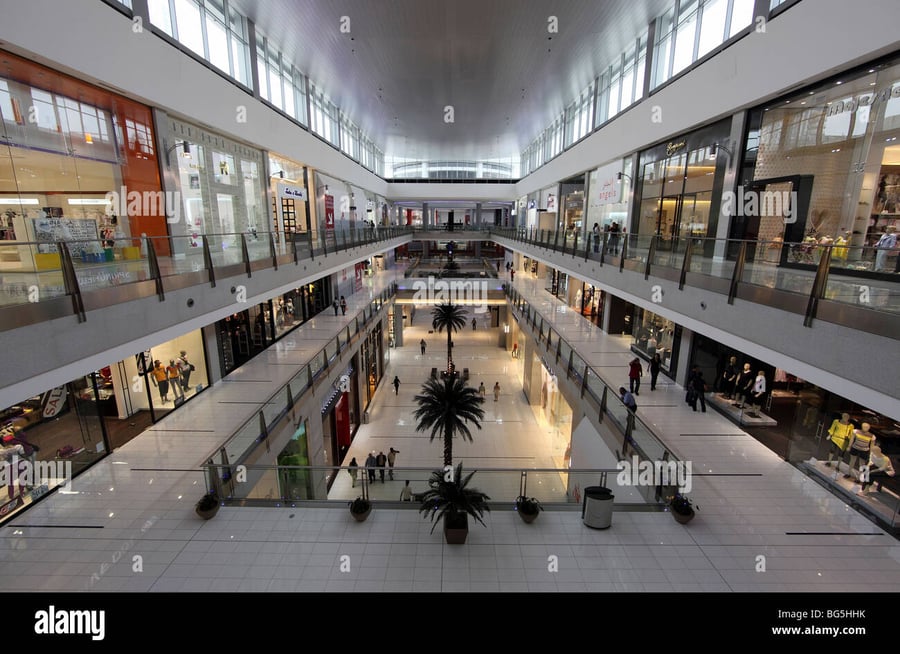
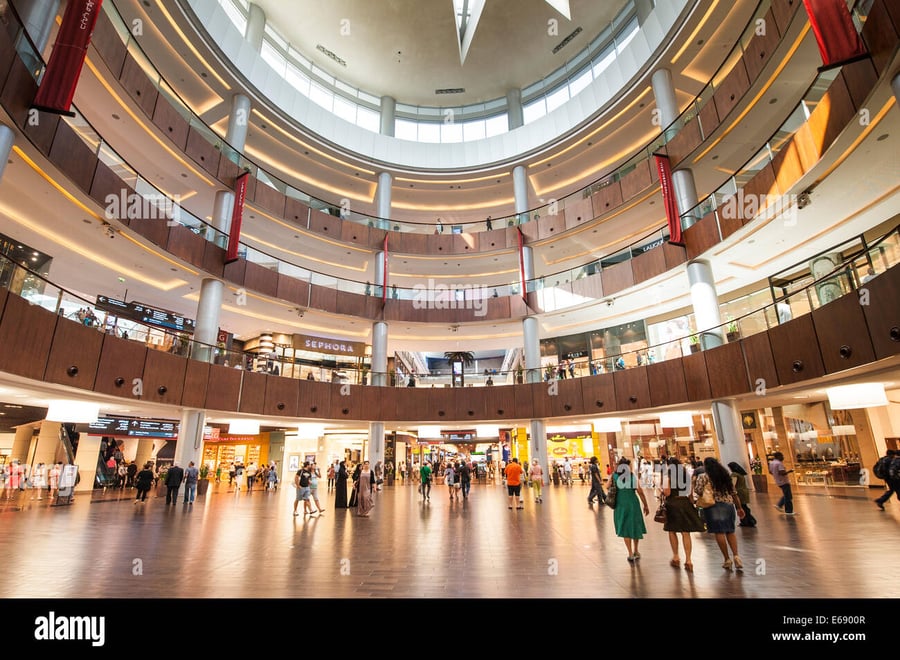
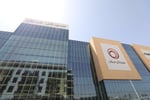
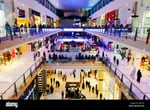
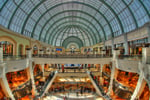
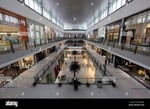
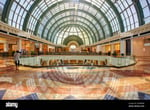
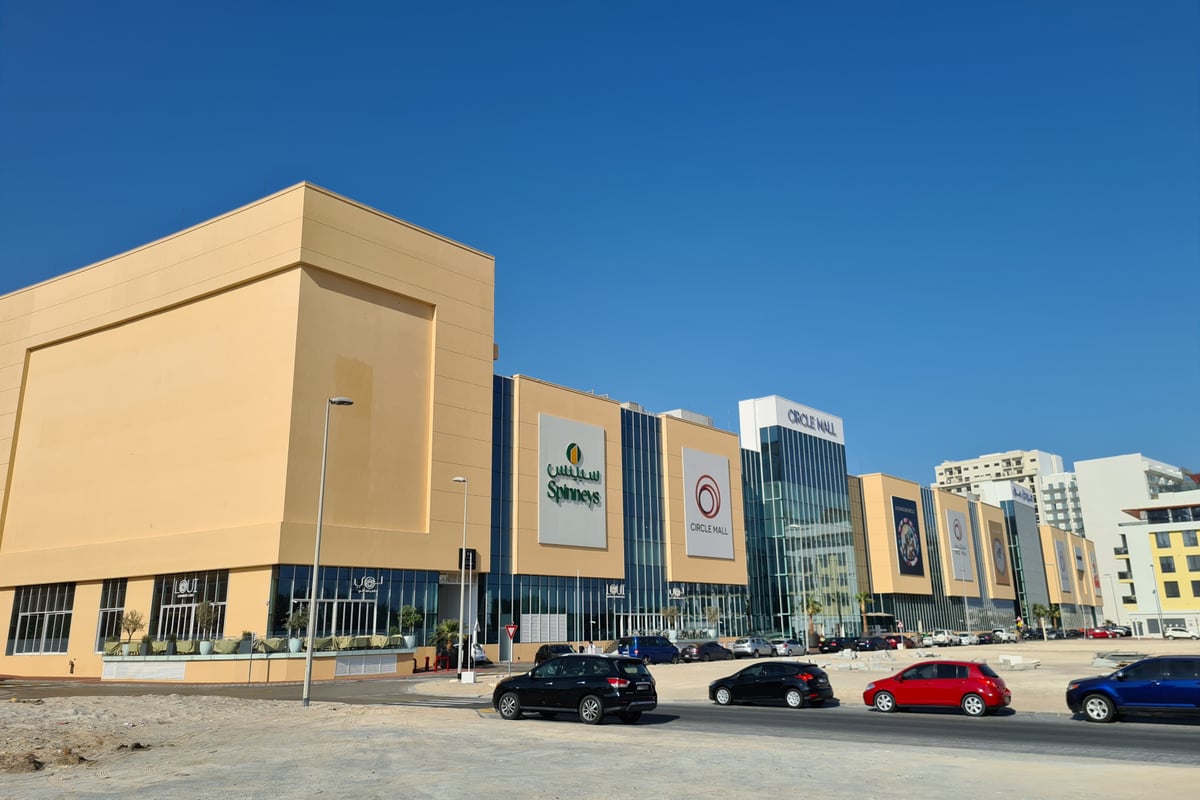
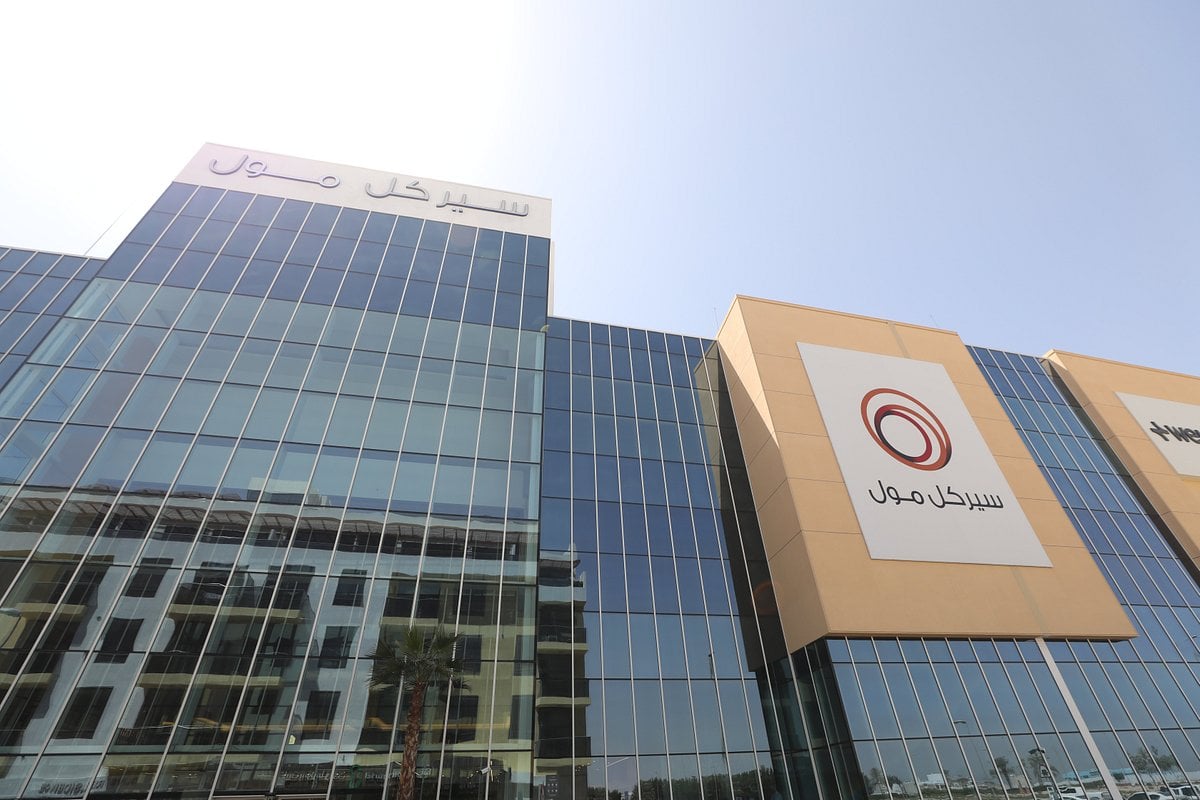
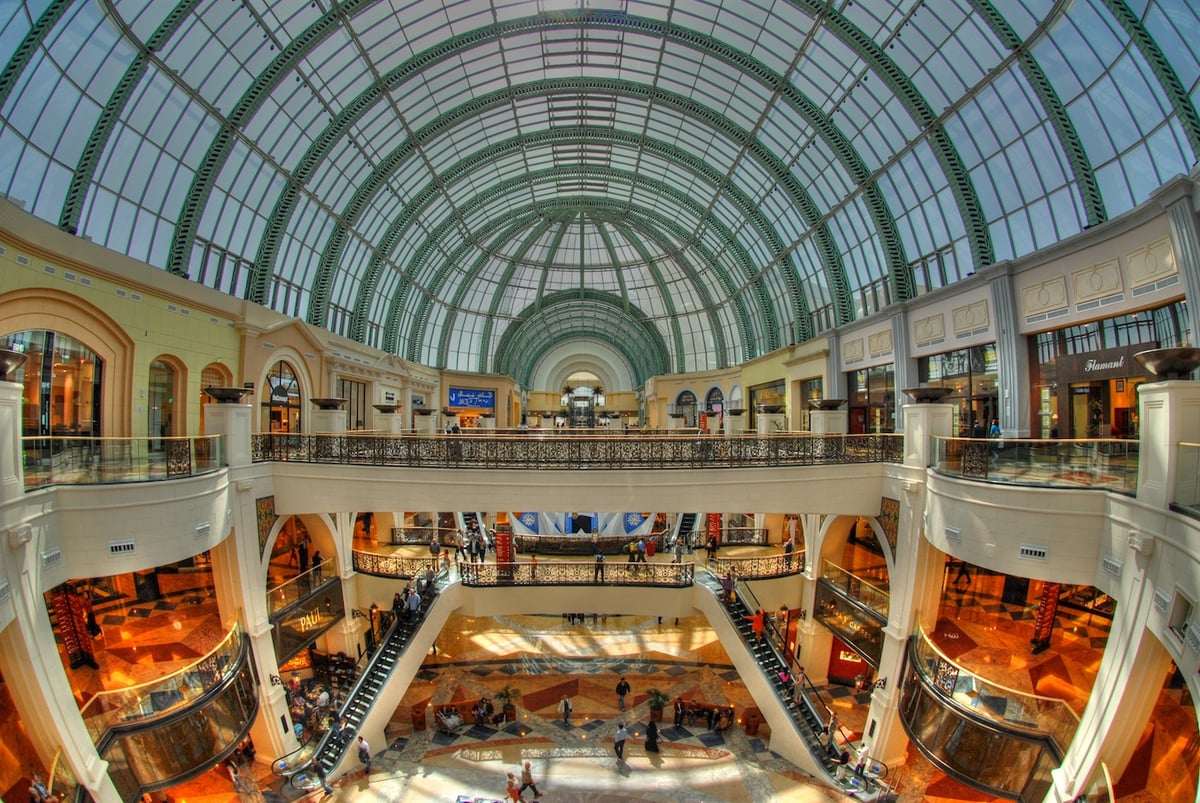
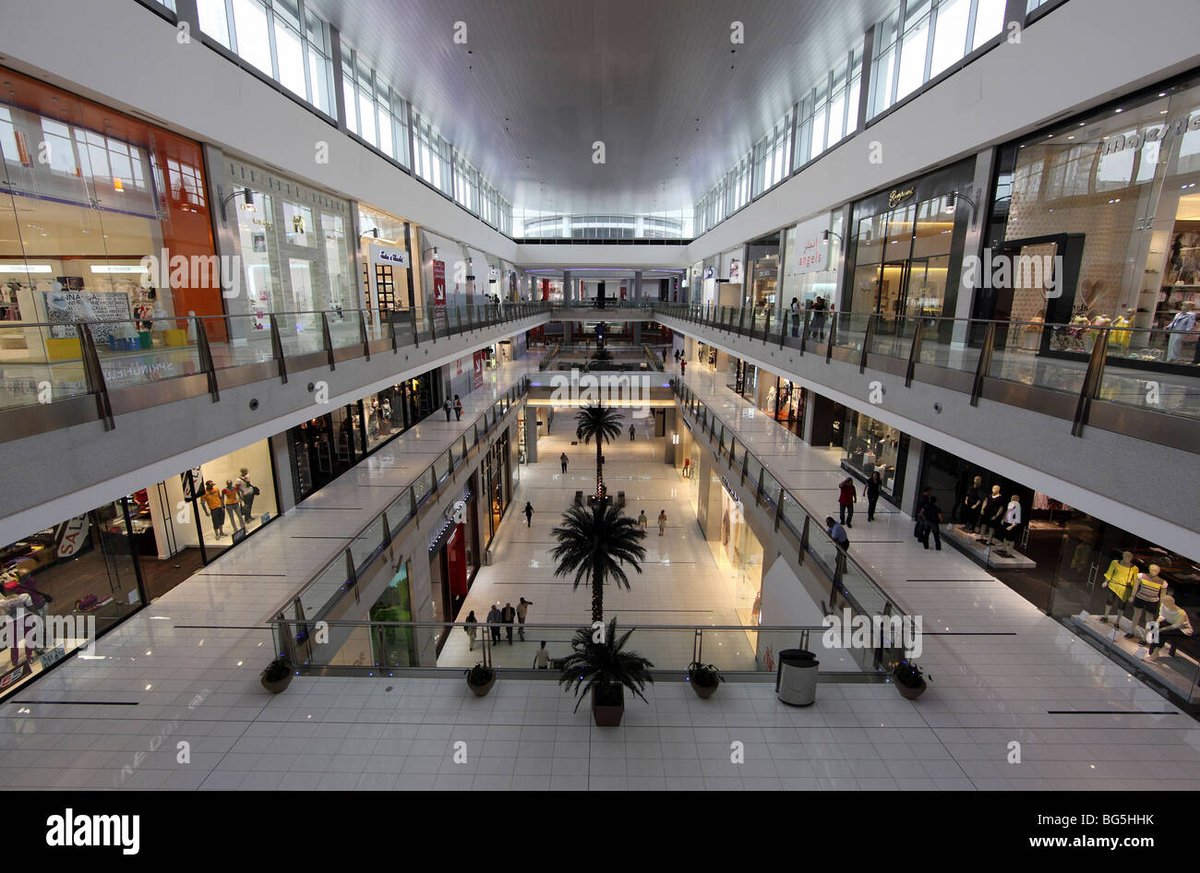
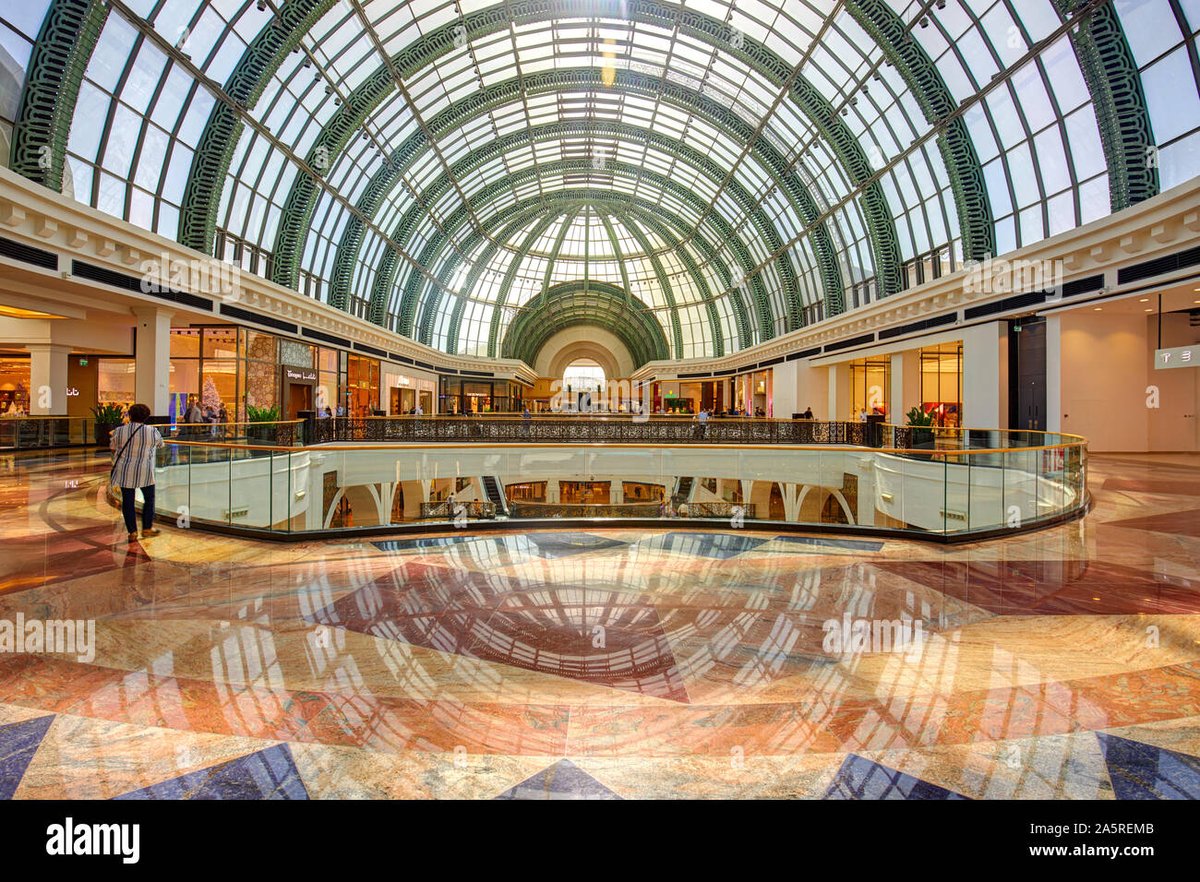
The Circle Mall, situated in Jumeirah Village Circle (JVC), Dubai, UAE, opened in 2021 under Nakheel Malls management. It offers 25,000 sqm of gross leasable area across two levels, housing over 200 outlets including 100 retail stores. Occupancy rate is 93%, matching Dubai's 2025 retail average of 92%, with 5% vacancy. Footfall stands at 6,000 daily visitors, rising to 10,000 on weekends, yielding 2.3 million annually and a 90-minute average dwell time, with 25% conversion rate.
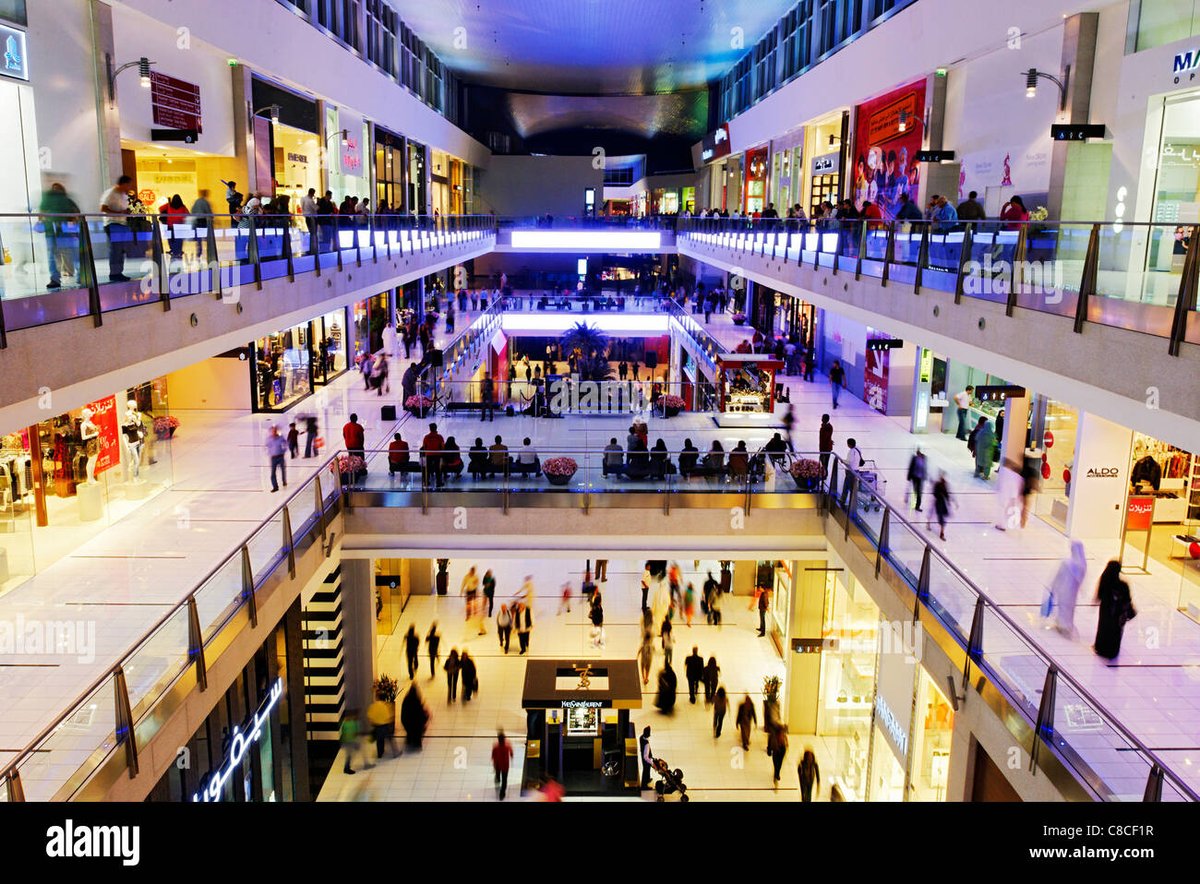
Tenant mix focuses on mid-tier accessibility: 40% fashion featuring Zara and local designers, 25% food and beverage with diverse options from shawarma to Italian, key anchors include Spinneys Supermarket, Nesto Hypermarket, and World Gym, plus 40 dining venues, a cinema, and entertainment facilities. The primary catchment area within 5 km holds 150,000 residents growing at 2.5% annually, drawing a mid-income demographic of 70% expatriates (35% Indian, 20% Pakistani, 15% Arab) and 60% young families aged 25-45, with median household income of AED 180,000 yearly.
Accessibility is supported by Al Khail Road, Sheikh Mohammed Bin Zayed Road, proximity to Dubai Metro (10 minutes), and 1,000 parking spaces. In the market, it positions as a value-oriented neighborhood hub amid JVC's 15% annual population growth and 92% residential occupancy, benefiting from low competitor density of 10 stores per sq km.
Leasing advantages encompass rents of AED 120-180 per sq ft annually (averaging AED 2,500 per sqm), offering 30% cost savings compared to central malls, flexible 3-5 year terms including fit-out contributions and 10-15% turnover rent elements, 7-8% yields, and 16% rent growth in line with Dubai's 7-8% suburban retail expansion.
Operational quality includes digital signage, loyalty programs (50% uptake), and events, though challenges arise from e-commerce erosion impacting 10-15% of sales, parking constraints during peaks, and saturation in groceries and casual dining categories. Broader risks involve expatriate turnover, peak-hour congestion, potential infrastructure aging in expanding JVC, and economic factors like inflation or oil fluctuations potentially reducing footfall by 5-10%.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 12:00 AM |
| Saturday | 10:00 AM — 12:00 AM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile
The Circle Mall attracts a diverse, mid-income visitor base from JVC's primary 5 km catchment of 150,000 residents, expanding at 2.5% yearly, and secondary 15 km area of 250,000. Demographics feature 70% expatriates, including 35% Indian, 20% Pakistani, and 15% Arab origins, with 60% comprising young families aged 25-45 (median age 32). Household size averages 3.8 persons, with 60% holding tertiary education and unemployment at 2.6%. Median annual income reaches AED 180,000, supporting per capita retail spending of USD 14,500 yearly (apparel USD 1,088, groceries USD 2,000, electronics USD 1,500). This profile favors value-oriented retail and family entertainment, though expatriate turnover poses risks to consistent footfall and spending patterns amid Dubai's high mobility.
Competitive Landscape
Direct competition remains low with a density of 10 stores per sq km in the neighborhood category, positioning The Circle Mall as a convenient local hub. Indirect rivalry stems from larger regional centers like Ibn Battuta Mall, which draw broader shoppers and tourists, potentially diverting 10-15% of discretionary spend. Dubai's 2025 retail market exhibits 7.85% leasing growth and 92% average occupancy, yet suburban areas face e-commerce pressures eroding physical sales and market saturation in categories like groceries and casual dining. JVC's 15% population influx supports steady demand, but retailers must differentiate through unique tenant mixes to counter online alternatives, given 99% internet penetration and high click-and-collect reliance.
Leasing Considerations
Annual rents range from AED 120-180 per sq ft (AED 2,500 per sqm average), yielding 30% savings over central Dubai locations, with 7-8% investment returns and 16% growth potential per 2025 reports. Leases typically last 3-5 years, incorporating 10-15% turnover rent and fit-out support for new tenants, amid 93% occupancy and 5% vacancy primarily in non-prime spaces (average 2,000 sqm available). Advantages include flexible terms and adjacency to 92% occupied residences boosting repeat visits, but challenges involve negotiating escalations amid rising operational costs from JVC expansion, e-commerce impacts on sales per sqm (AED 15,000 yearly average), and risks from economic volatility or saturation pressuring margins in weak categories like fast food.
Building Details
Detailed Market Analytics
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Dubai
Discover more shopping centers in Dubai.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city