Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
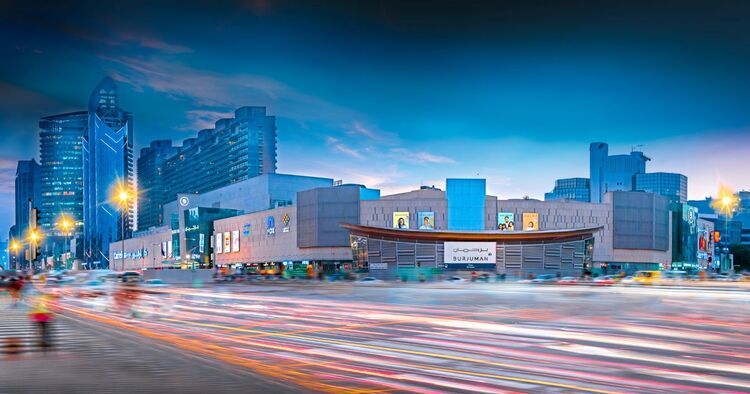
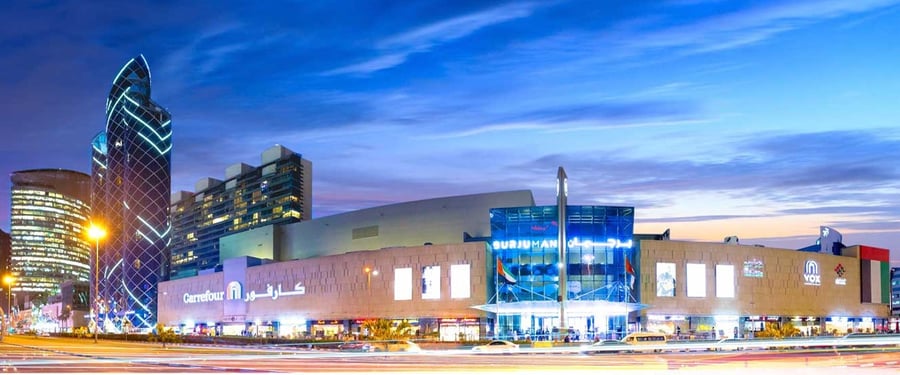
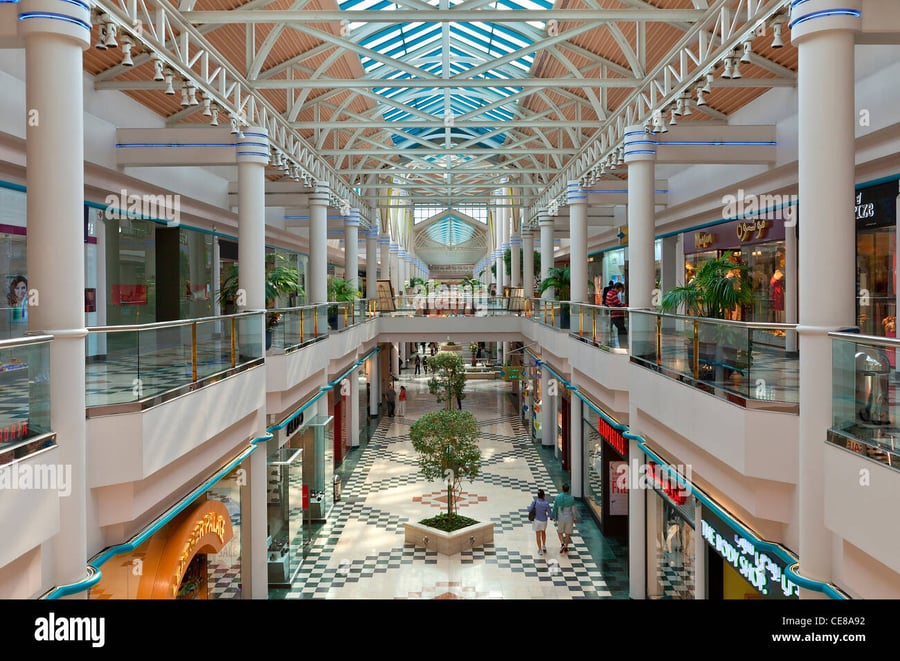
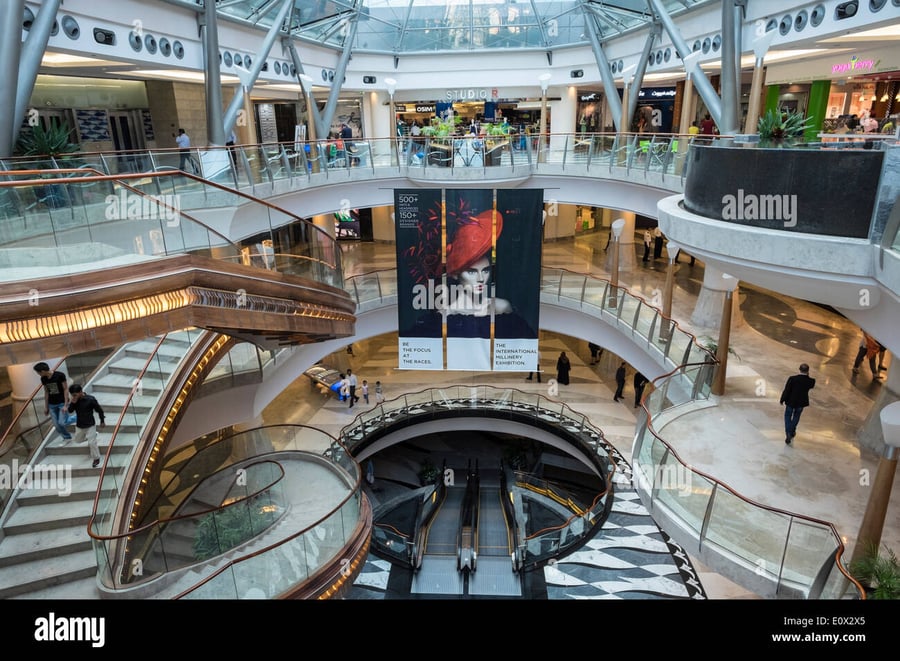
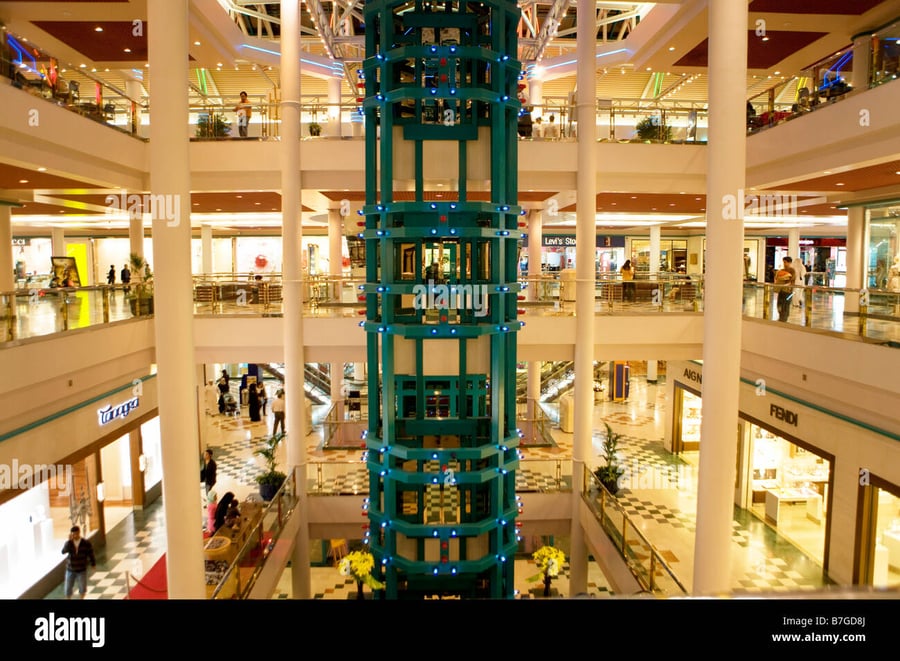
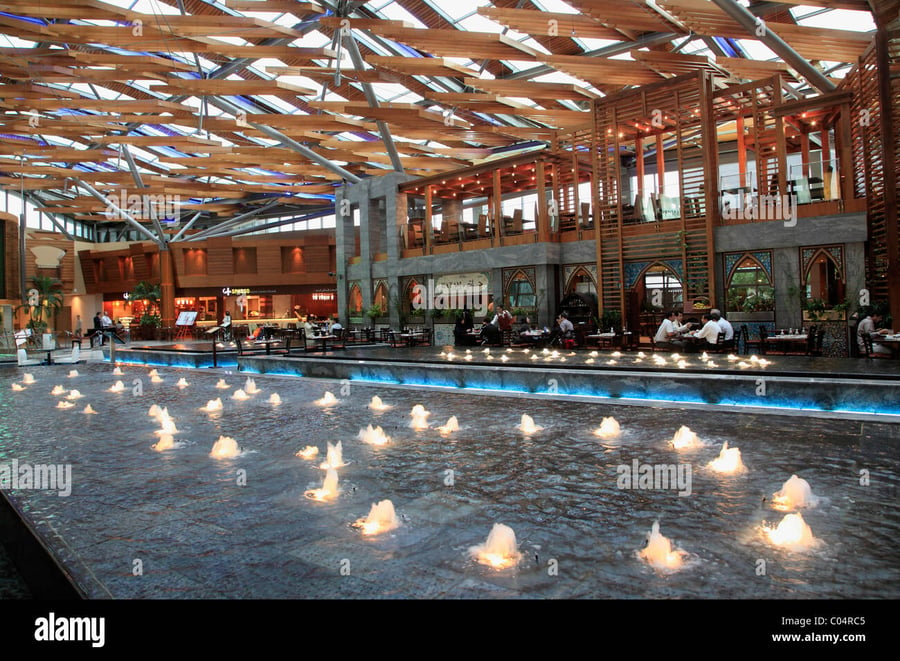
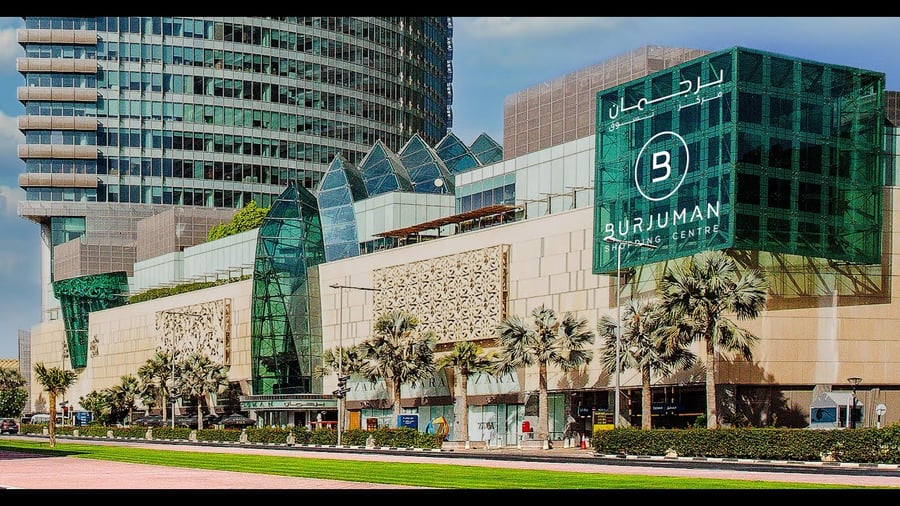
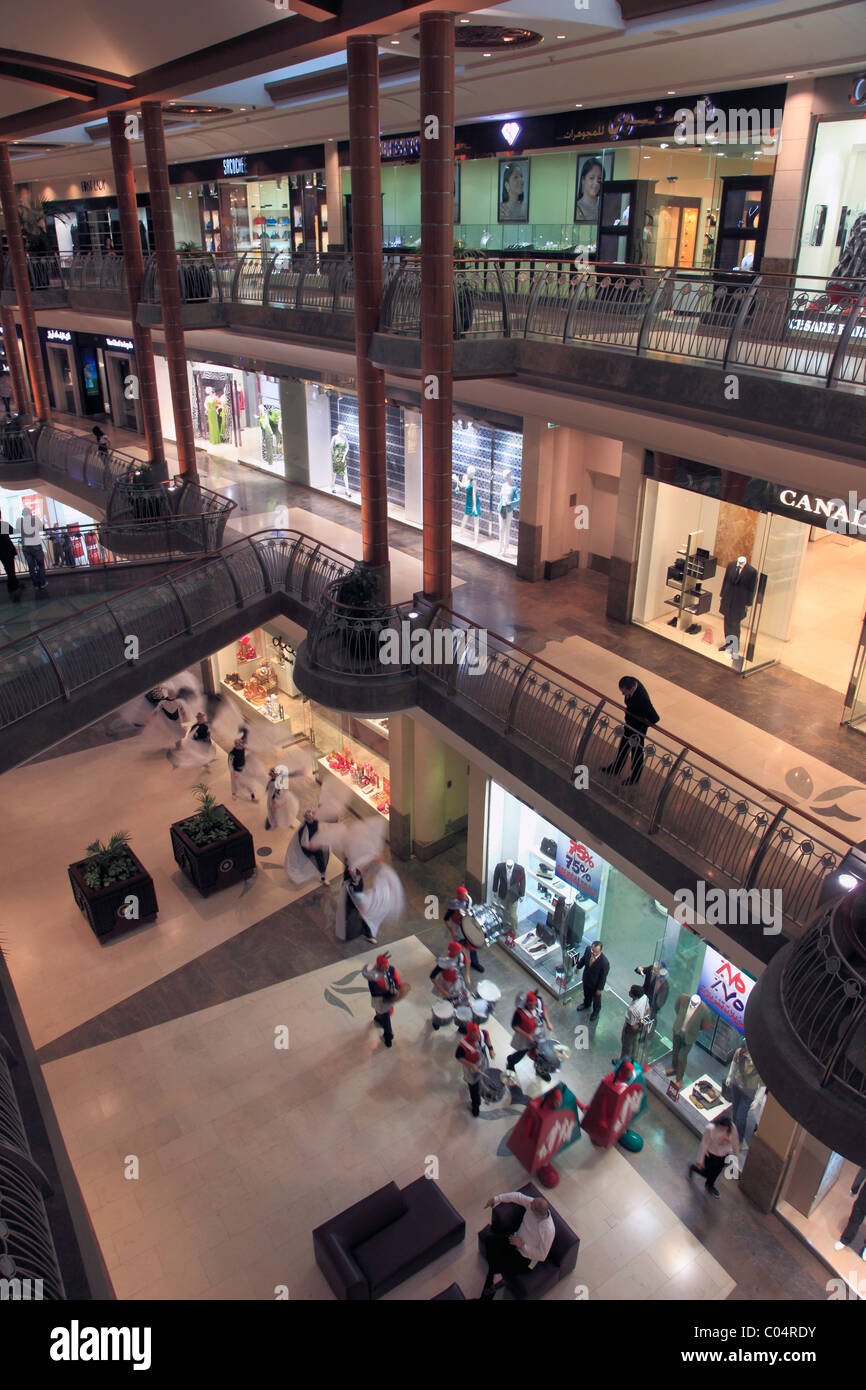
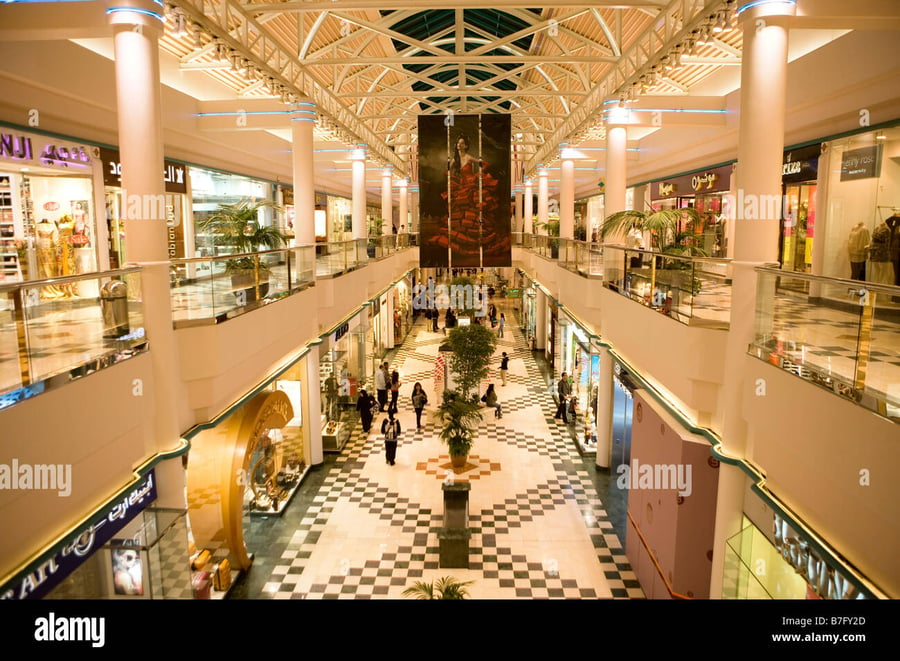
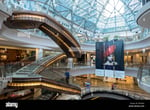
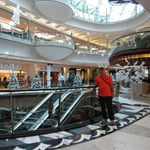
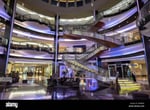
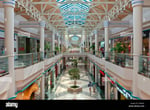
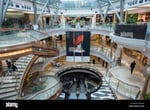
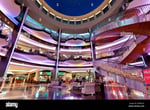
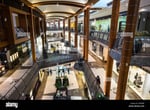
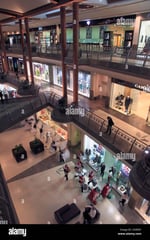
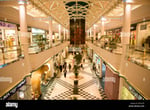
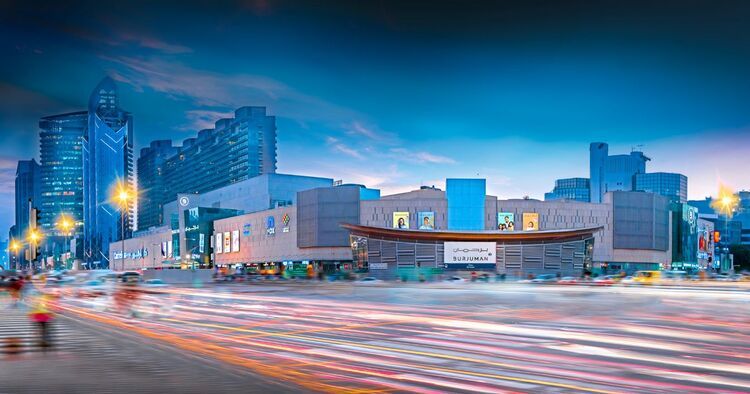
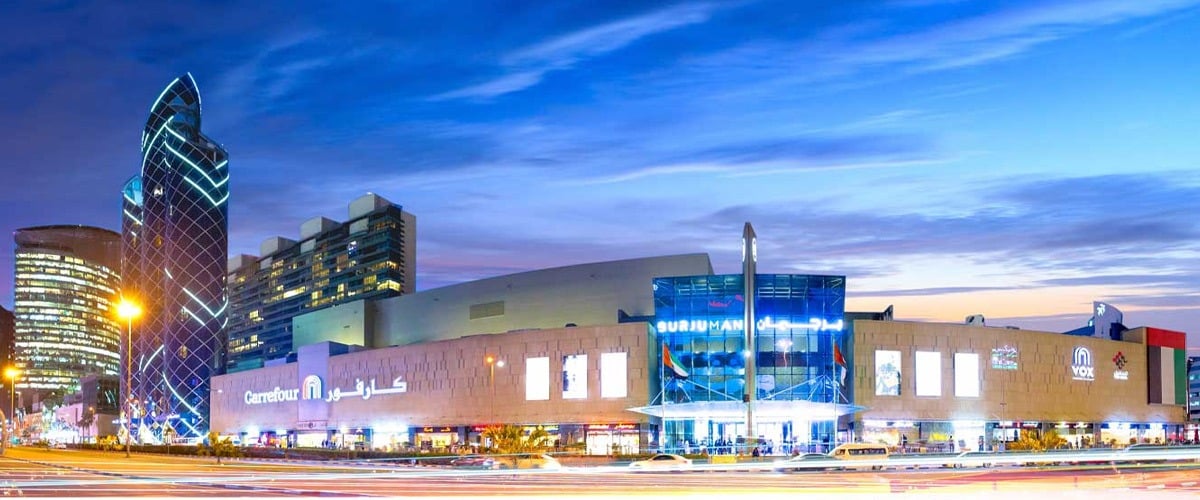
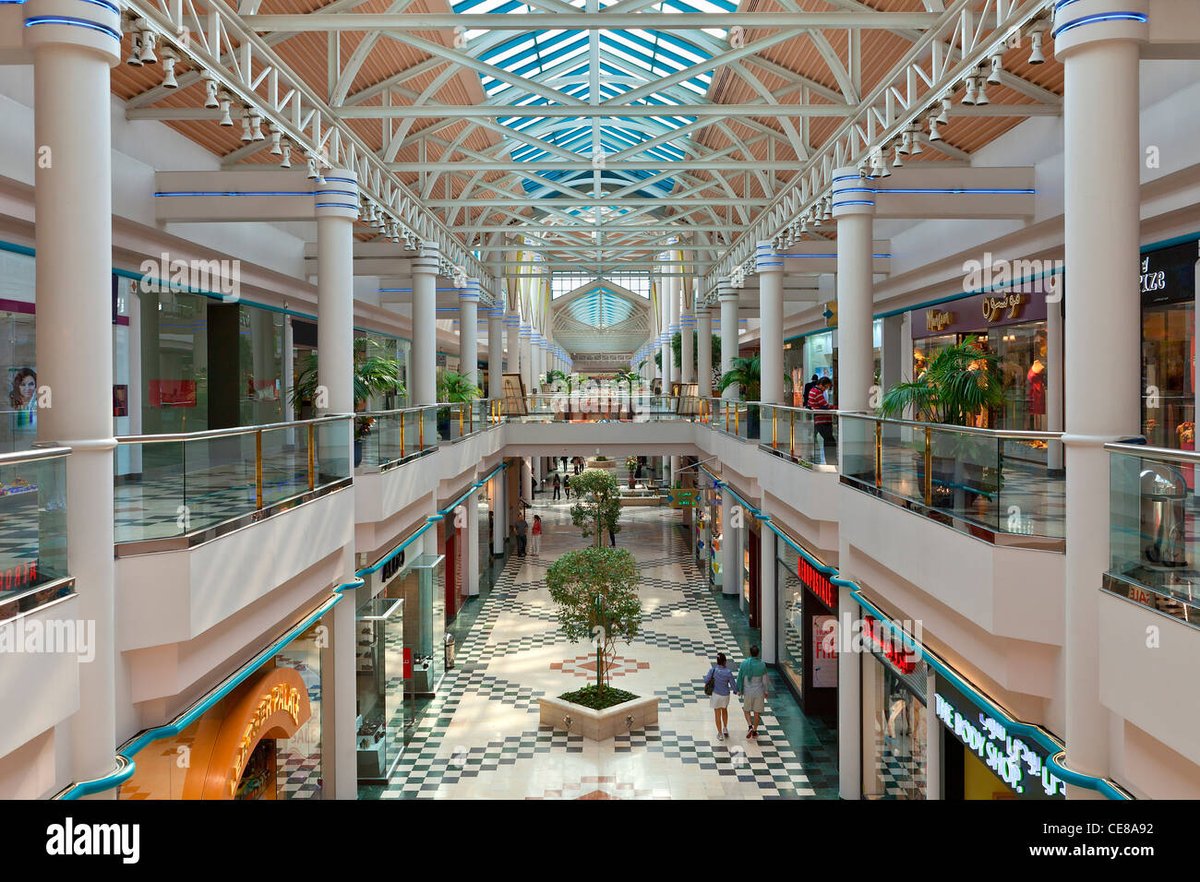
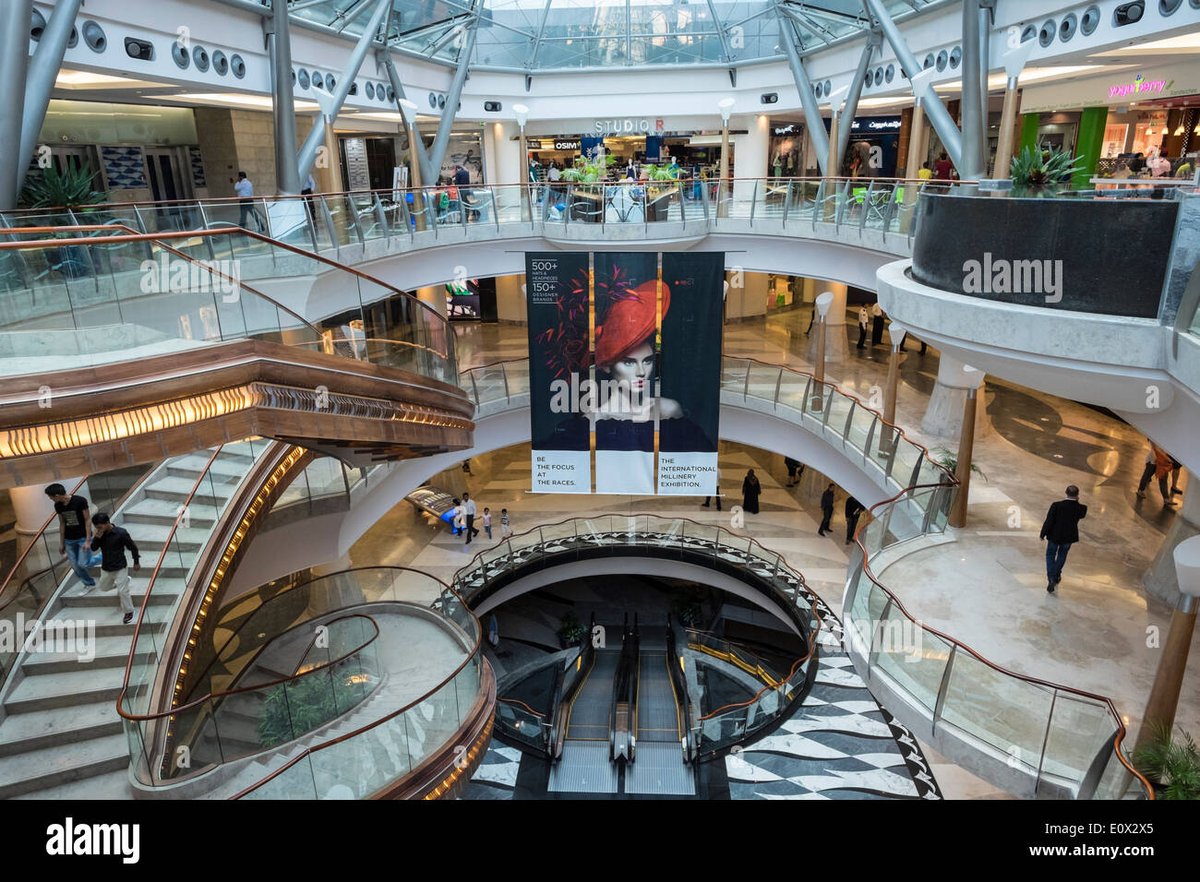
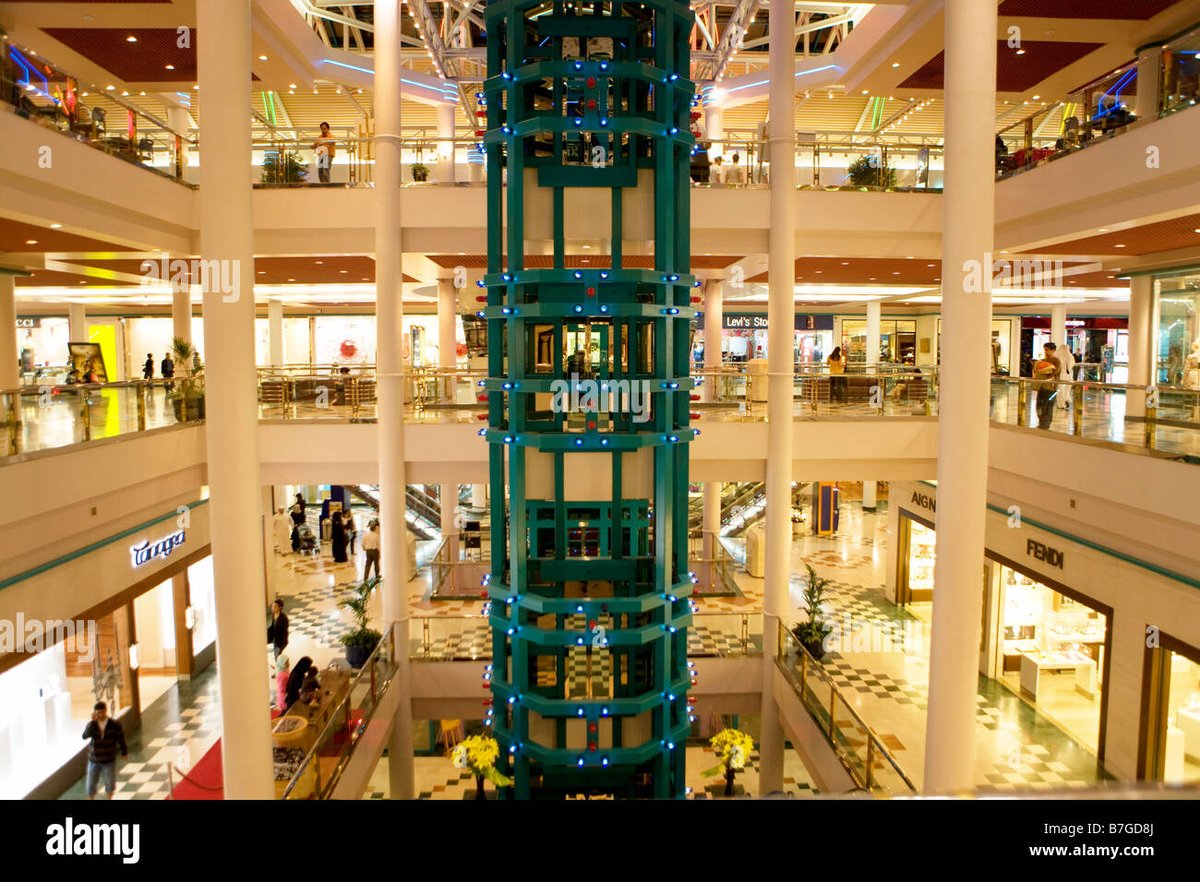
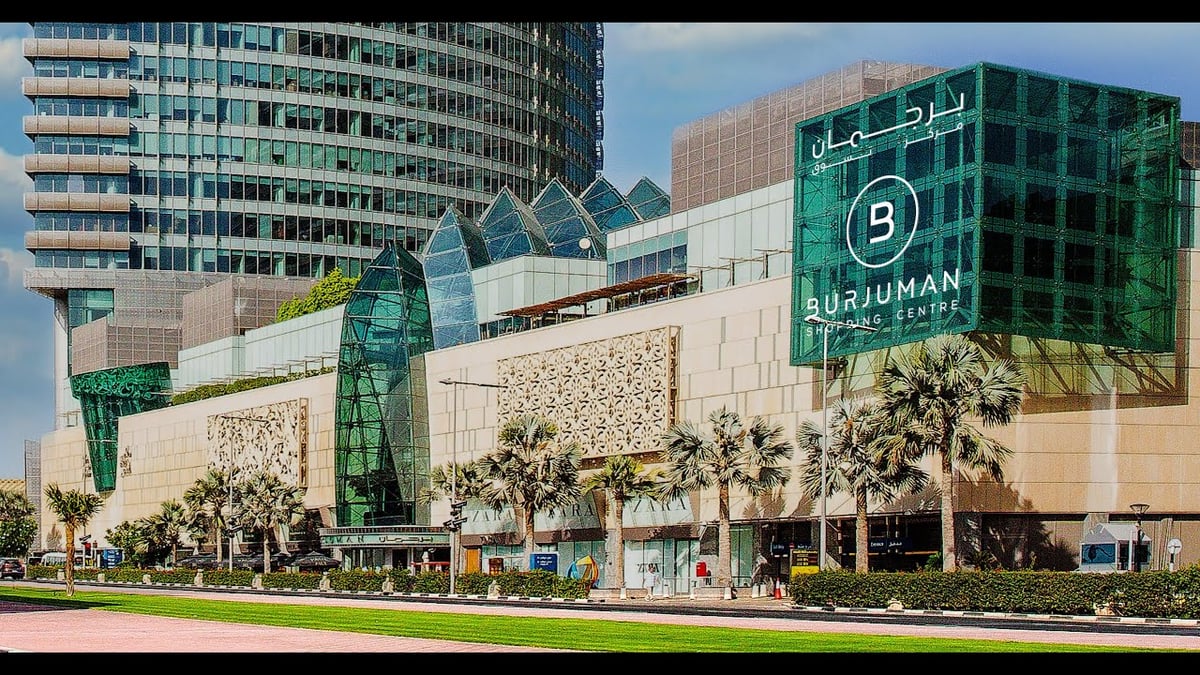
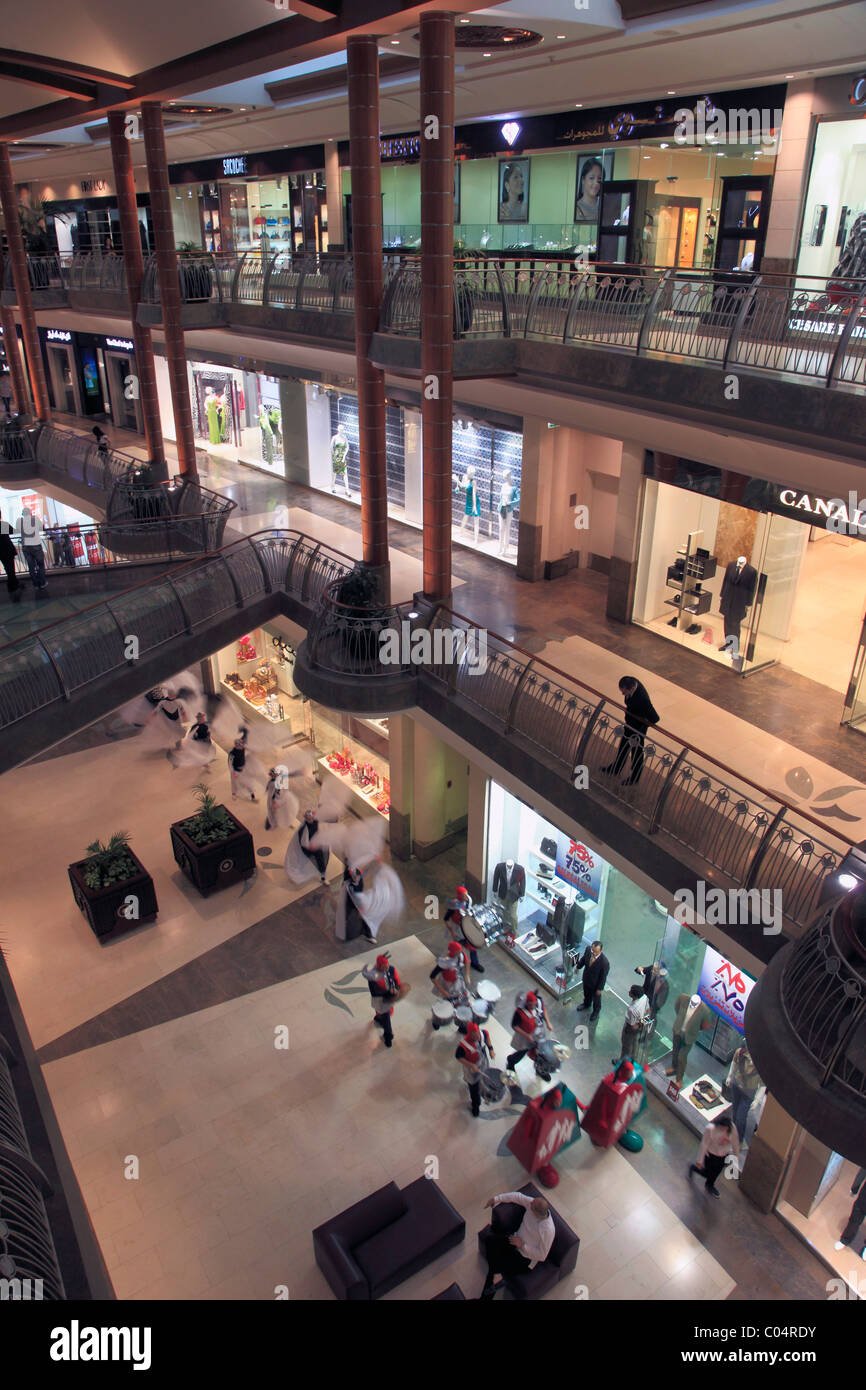
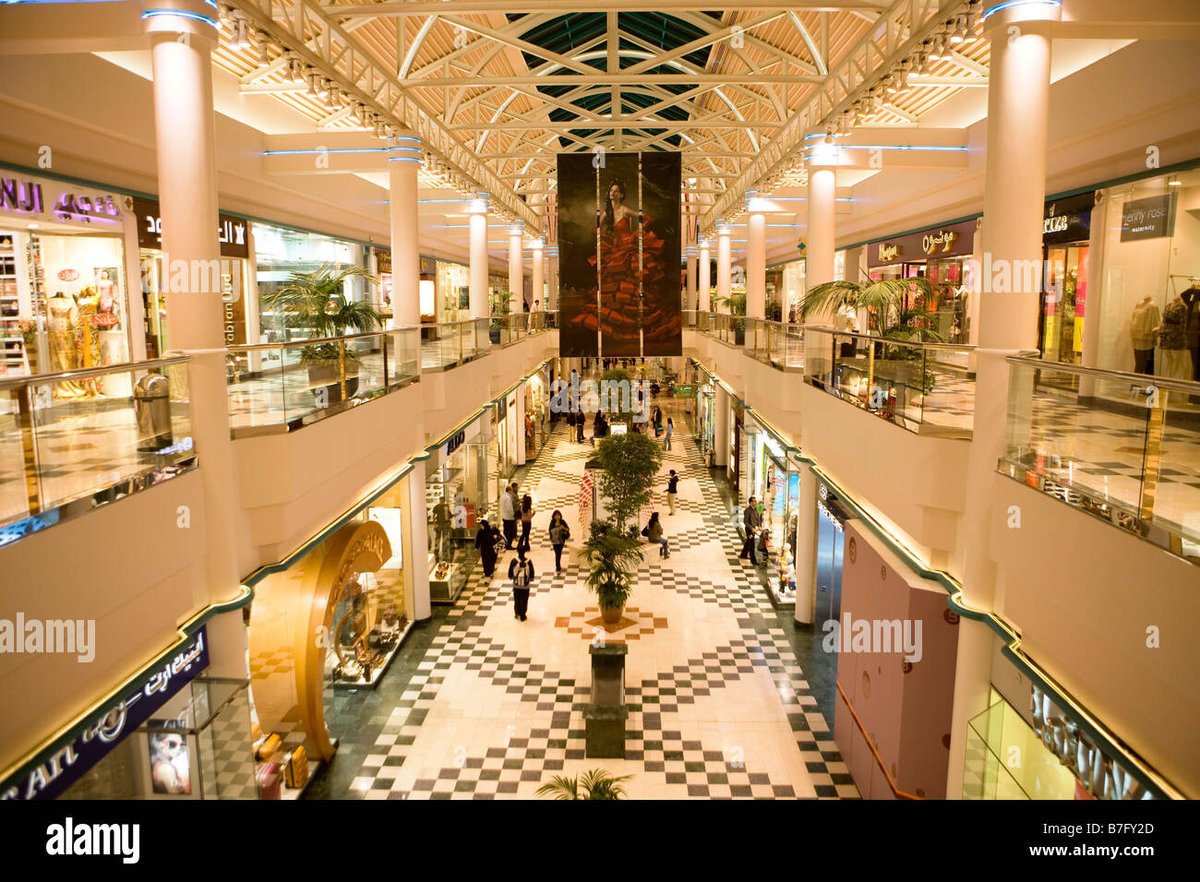
BurJuman, located in the Bur Dubai district of Dubai, UAE, is a mid-tier shopping center opened in 1997 and owned by Emaar Properties.
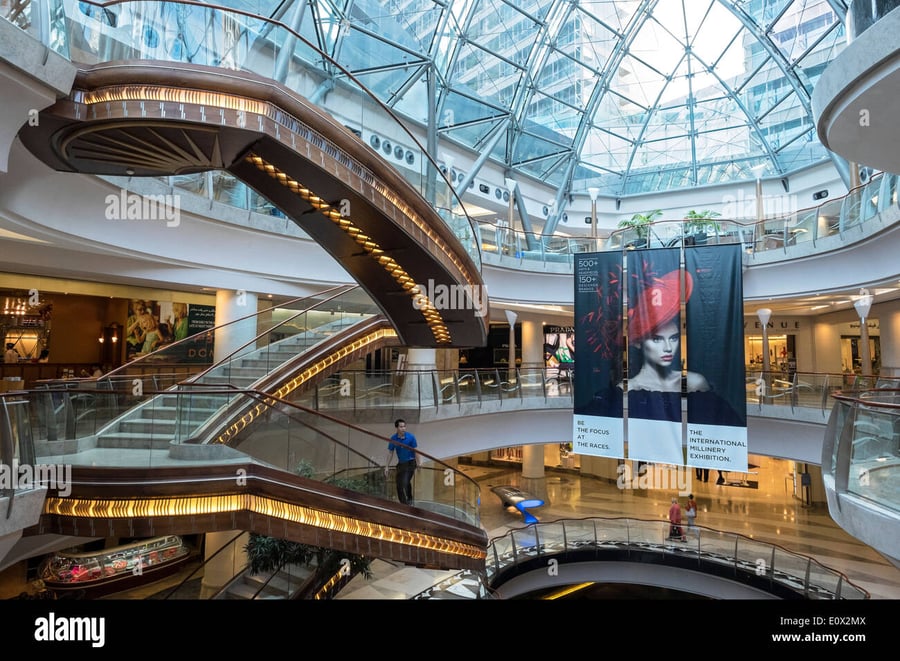
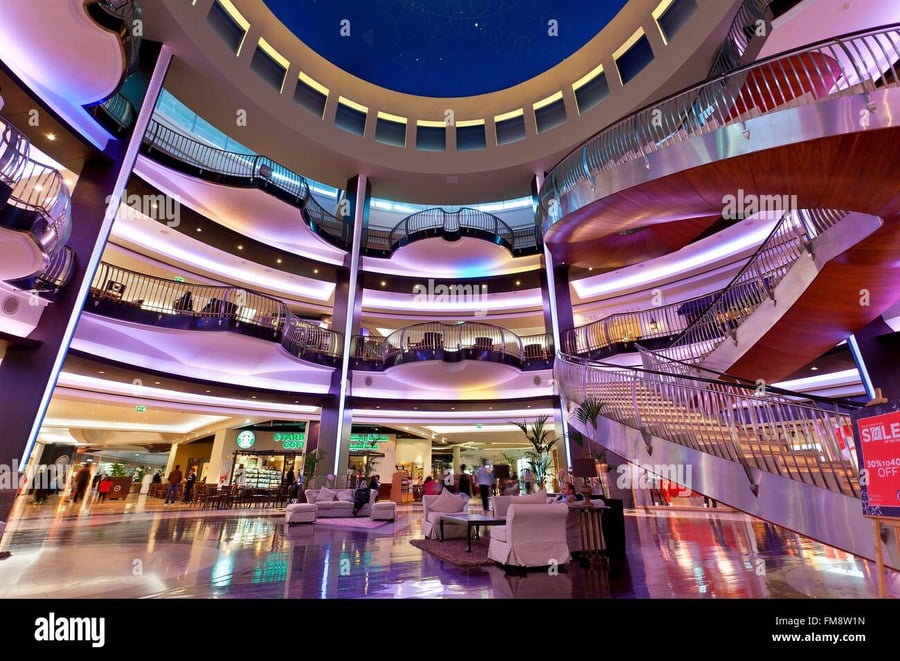
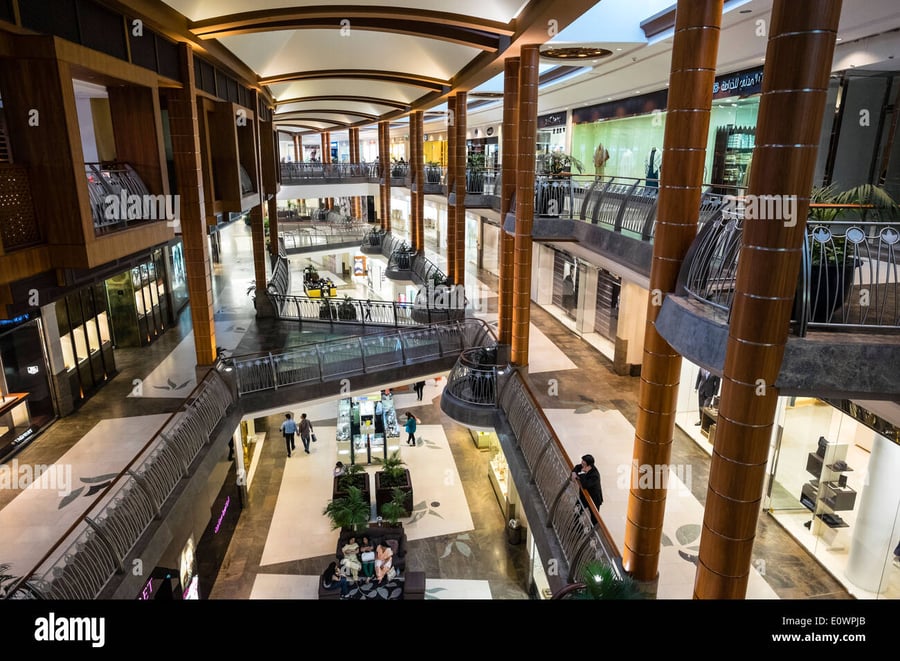
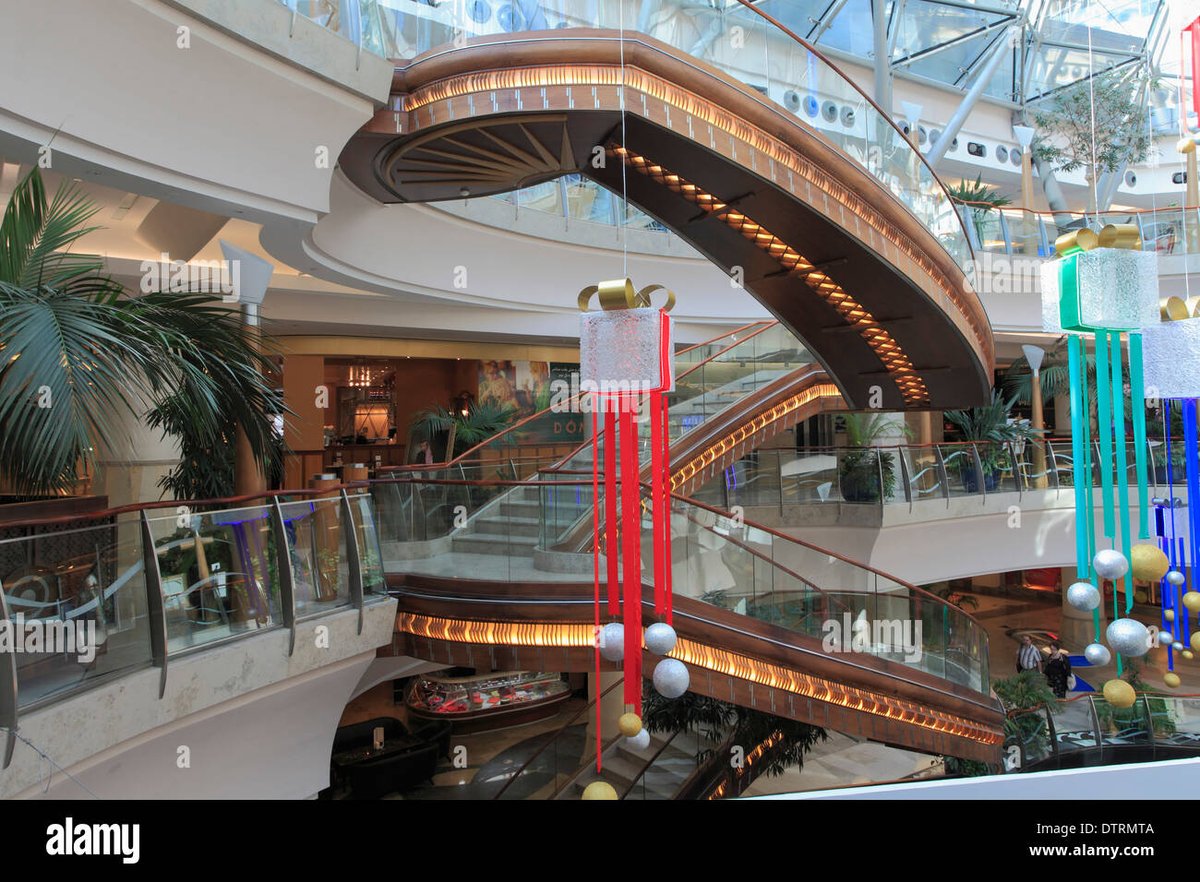
Spanning approximately 140,000 square meters of gross leasable area, it serves as a key retail node in the historic area near the Dubai Creek. The mall has undergone a multi-year transformation program, completed phases in 2024-2025, including facade upgrades, interior modernizations, and enhanced digital integrations, resulting in a double-digit footfall increase in 2025 compared to 2024.
Market position is transitional between luxury and mainstream retail, targeting a mix of local residents, expatriates, and tourists drawn to the adjacent Gold Souk and cultural sites.
Tenant mix comprises over 250 stores, with strengths in jewelry (e.g., international brands like Damas, Malabar Gold), fashion (Zara, H&M, Mango), electronics (eXtra, Sharaf DG), and department stores (formerly Debenhams, now reconfigured). Dining options include diverse cuisines from fast-casual to mid-range, with 30+ outlets.
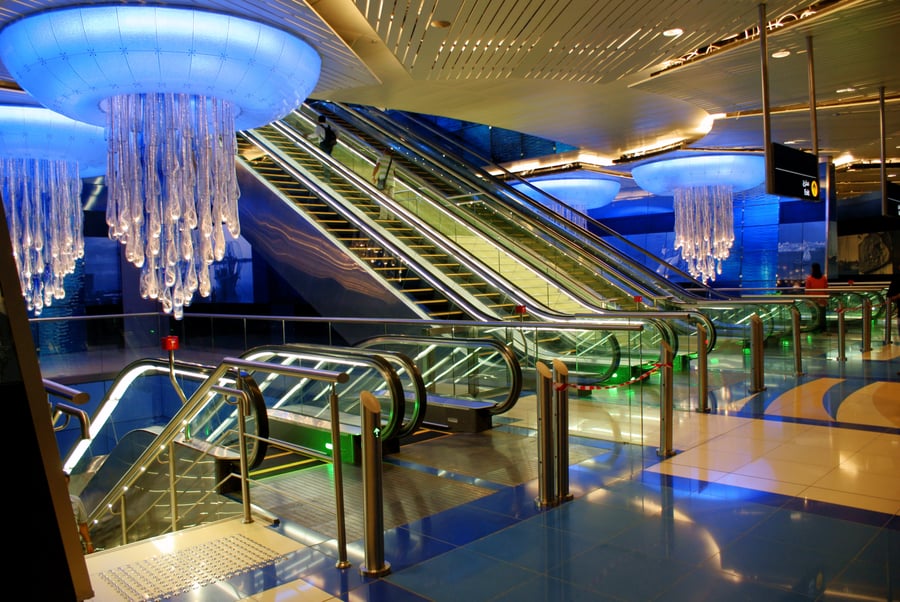
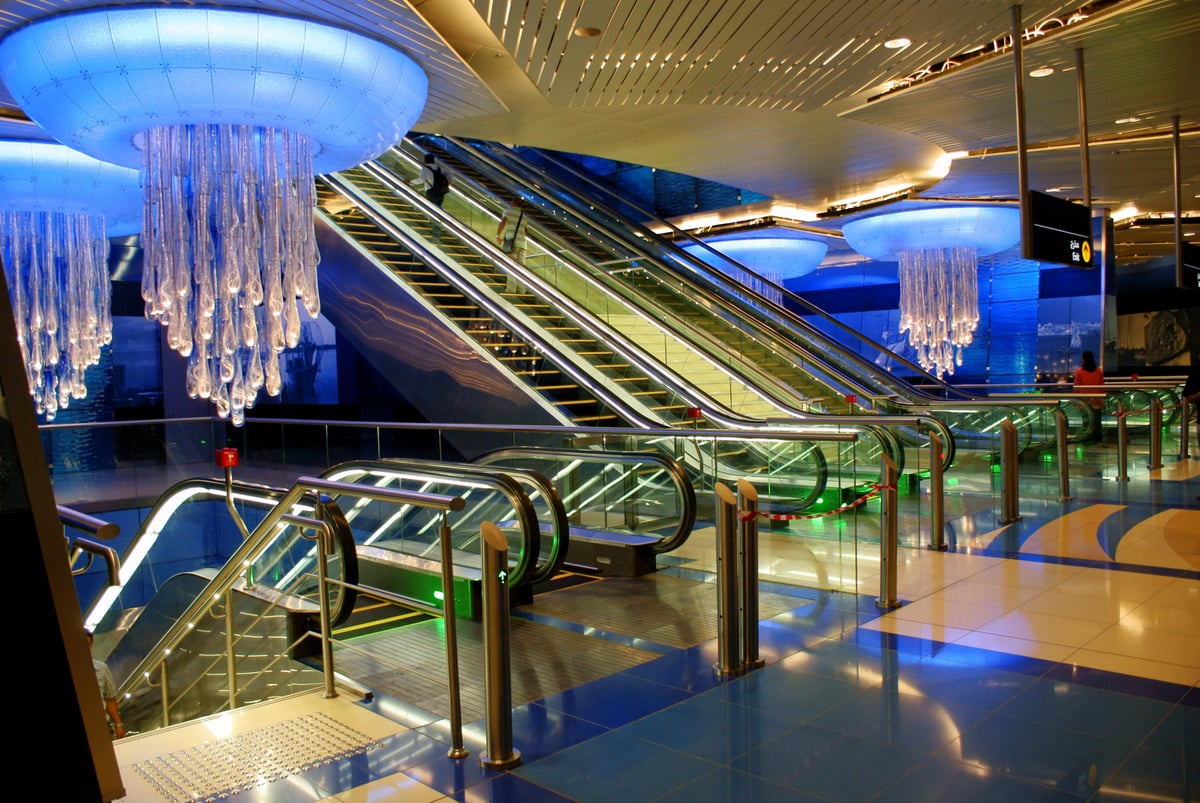
Accessibility is a major advantage, directly connected to BurJuman Metro Station on the Red Line, offering seamless public transport links, ample parking for 2,500 vehicles, and proximity to Sheikh Zayed Road (5-10 minutes drive to Downtown Dubai). Occupancy stands at around 95%, aligned with Dubai's robust retail market where prime malls average 98% per H1 2025 reports. Average rents range from AED 1,500-3,000 per sqm annually, competitive for secondary locations but pressured by high-end competitors.
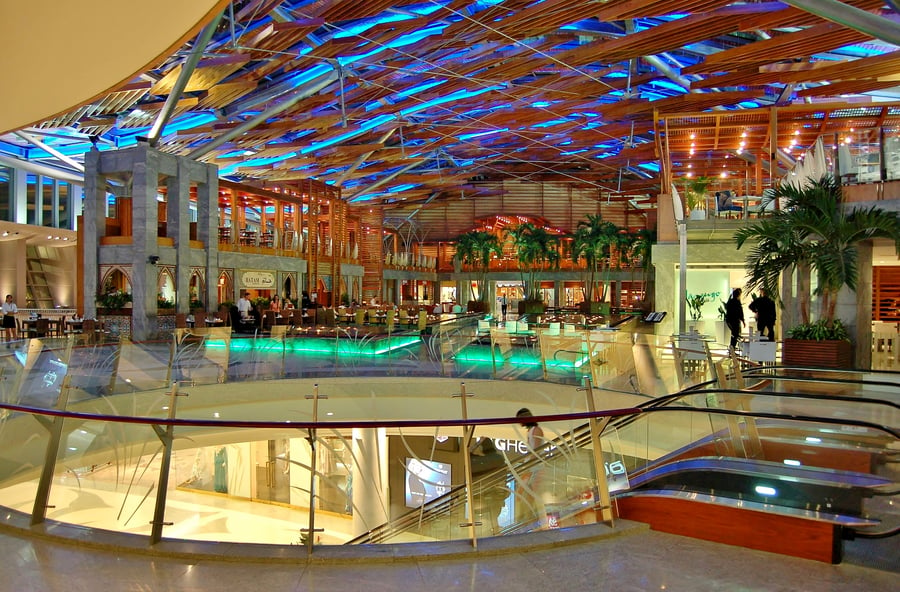
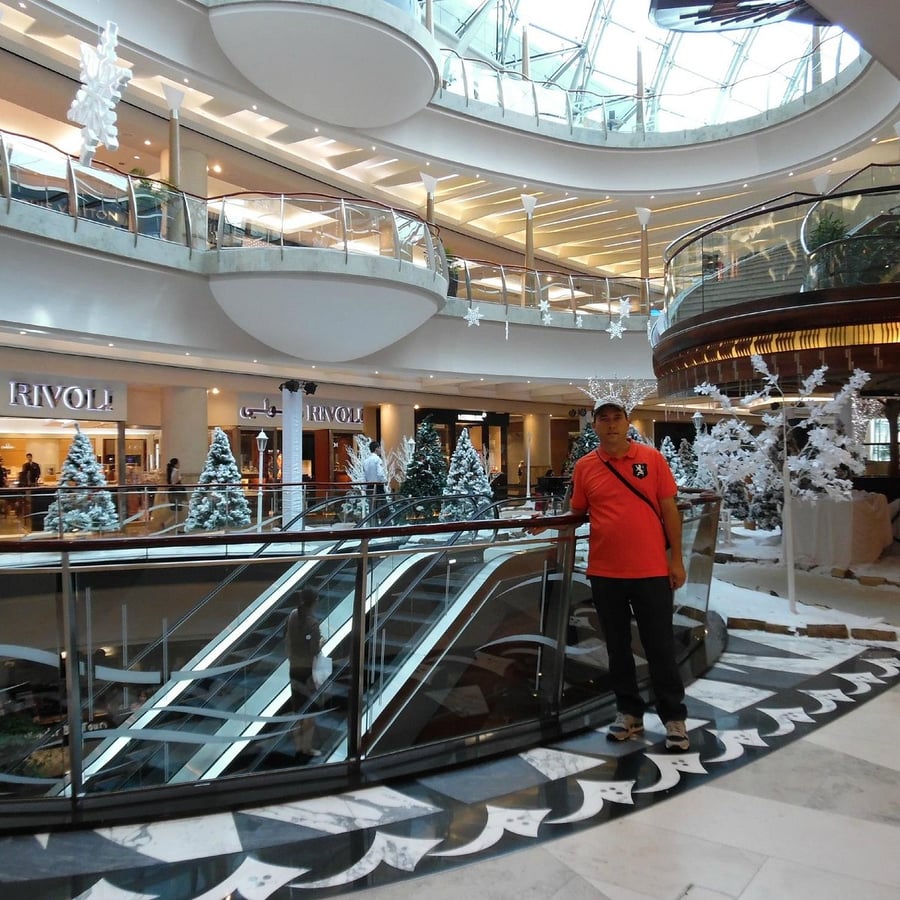
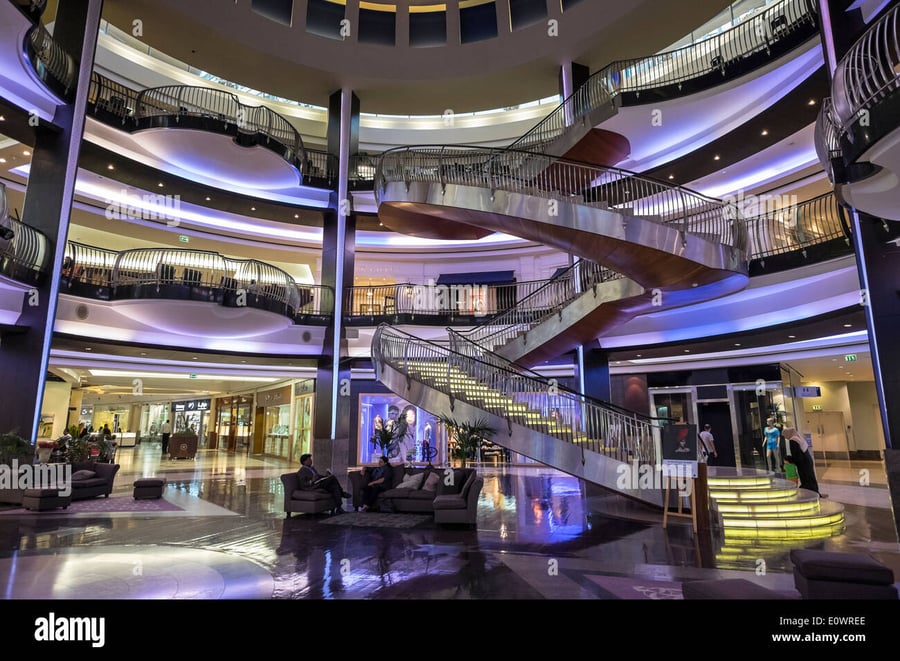
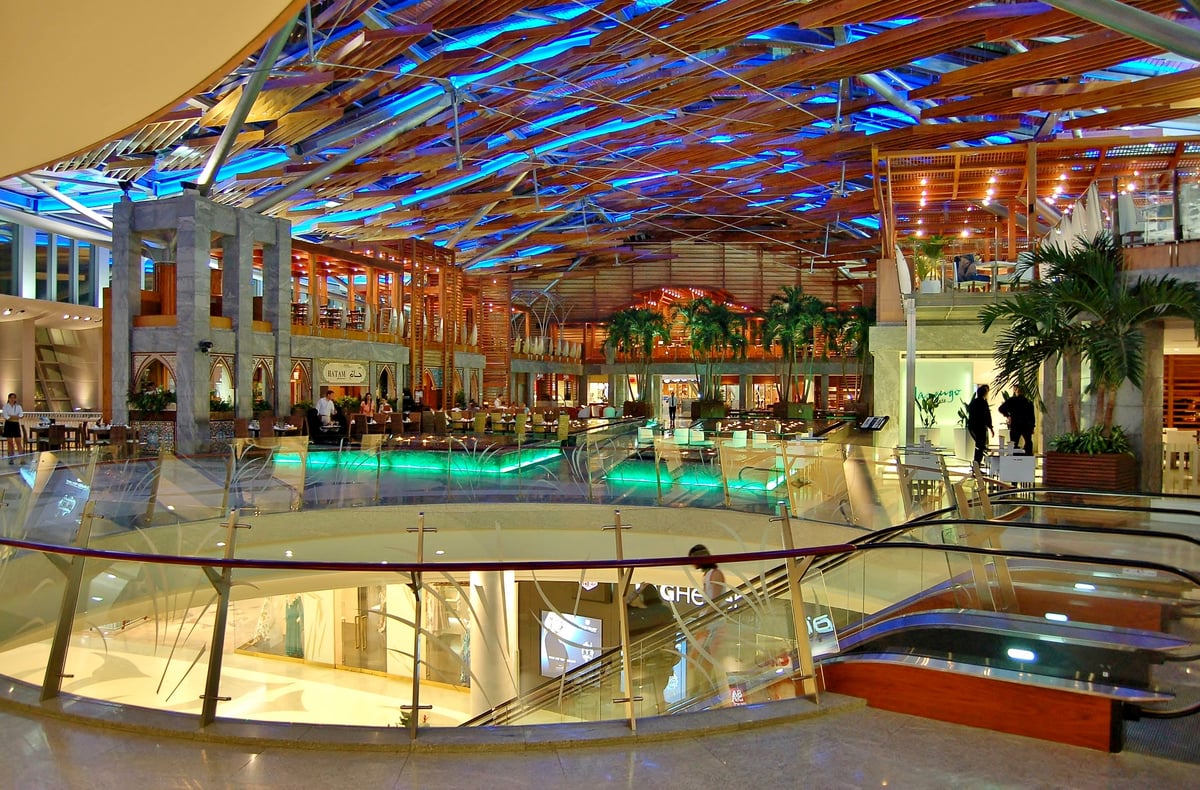
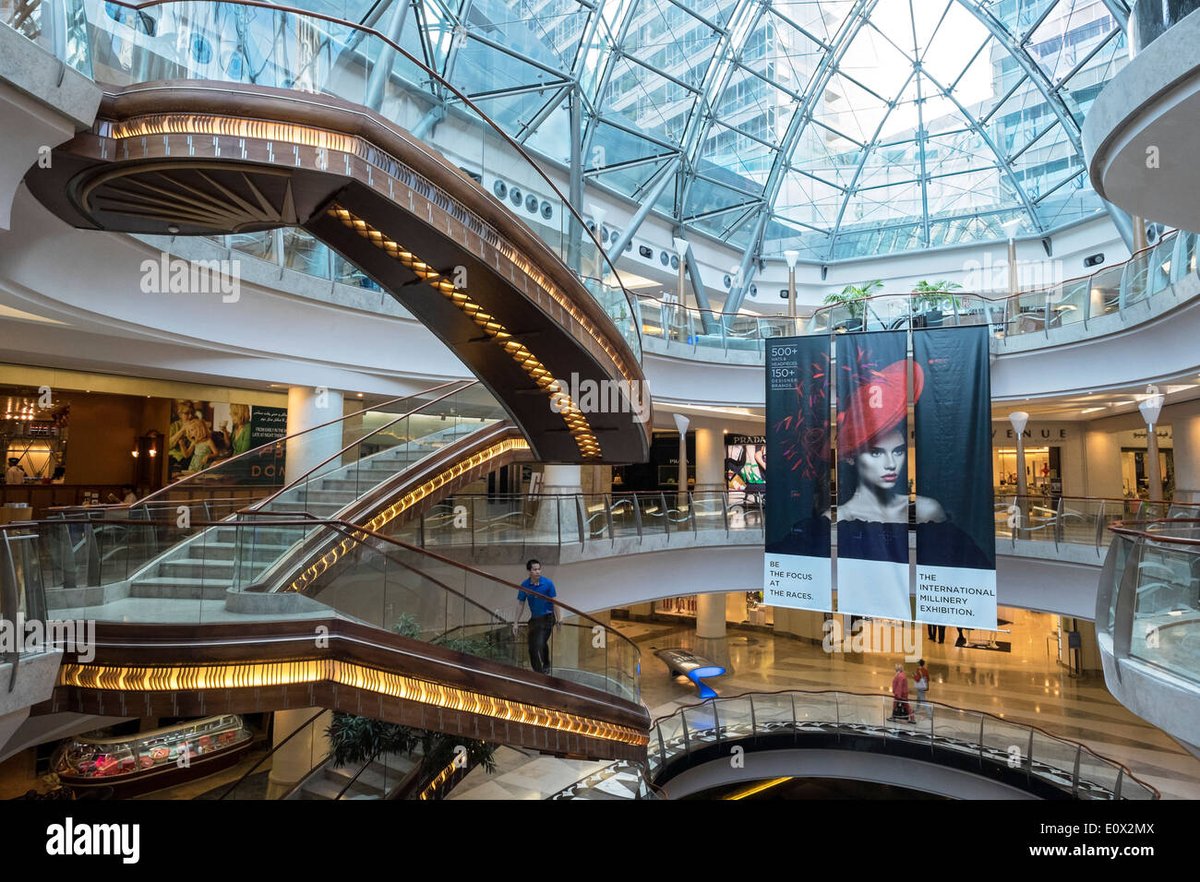
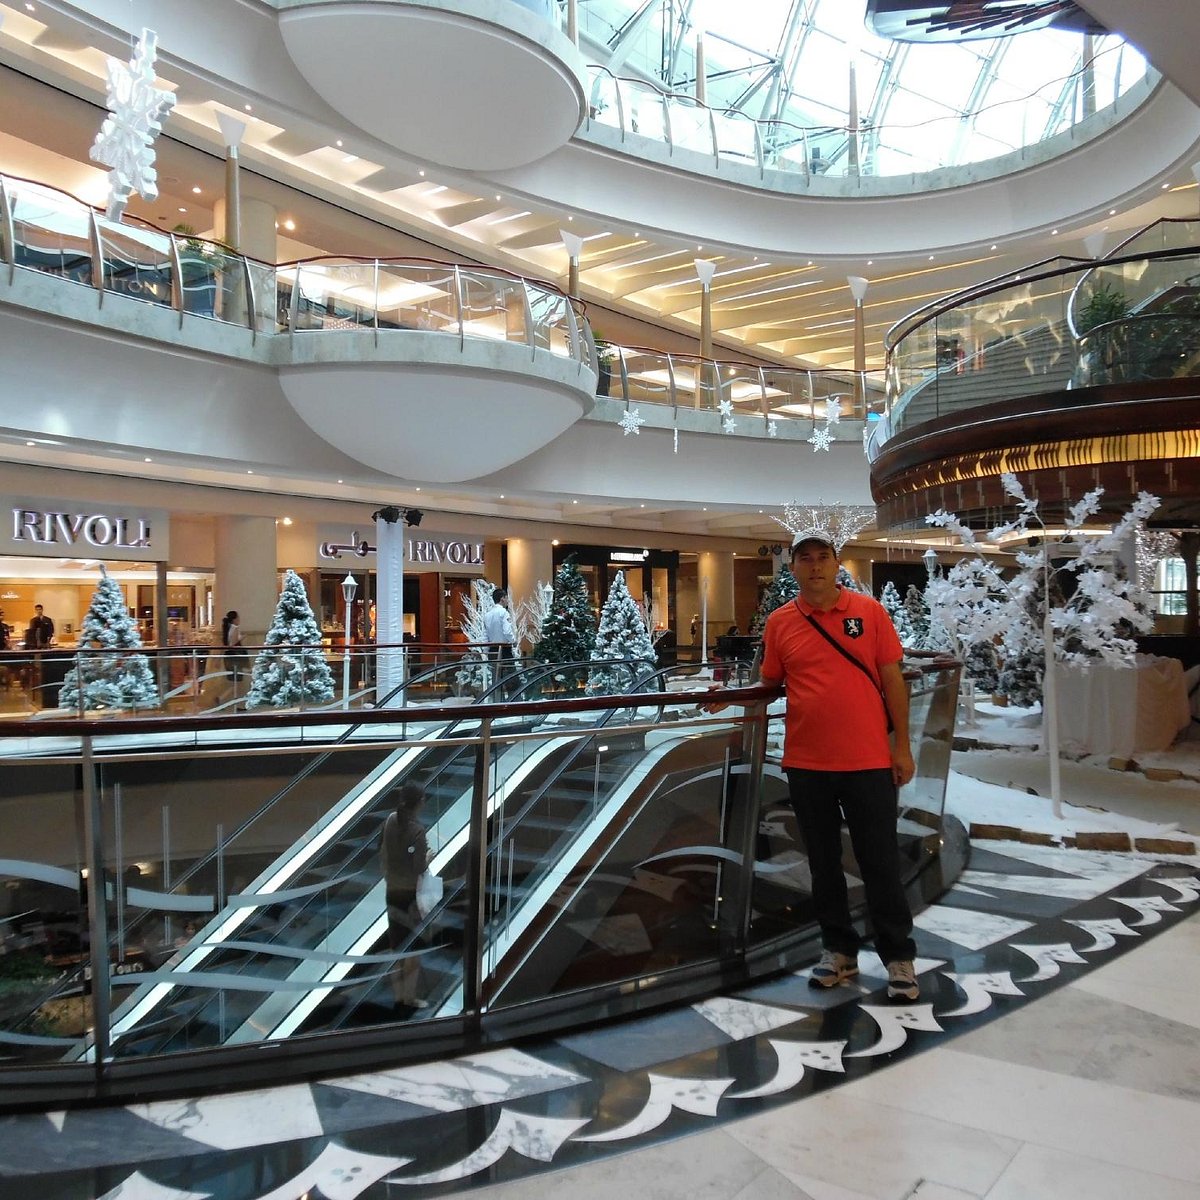
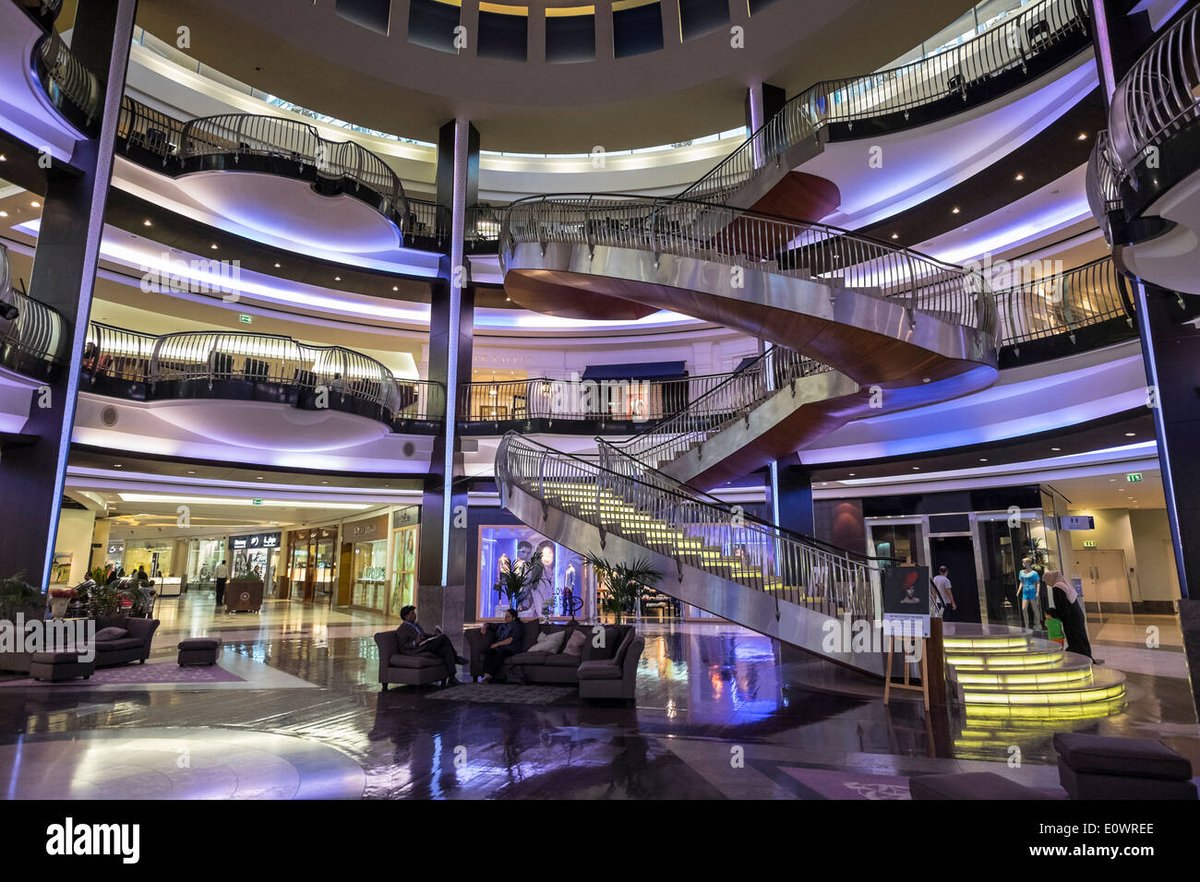
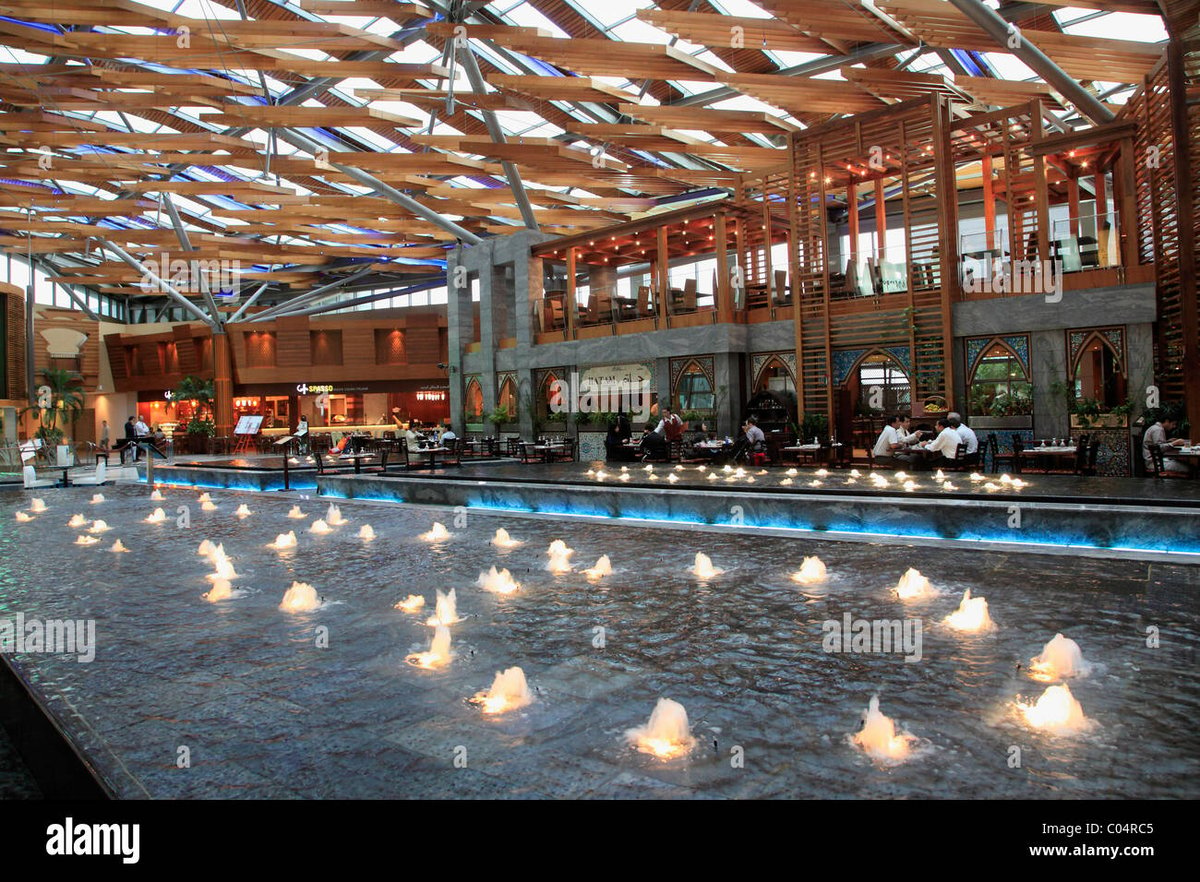
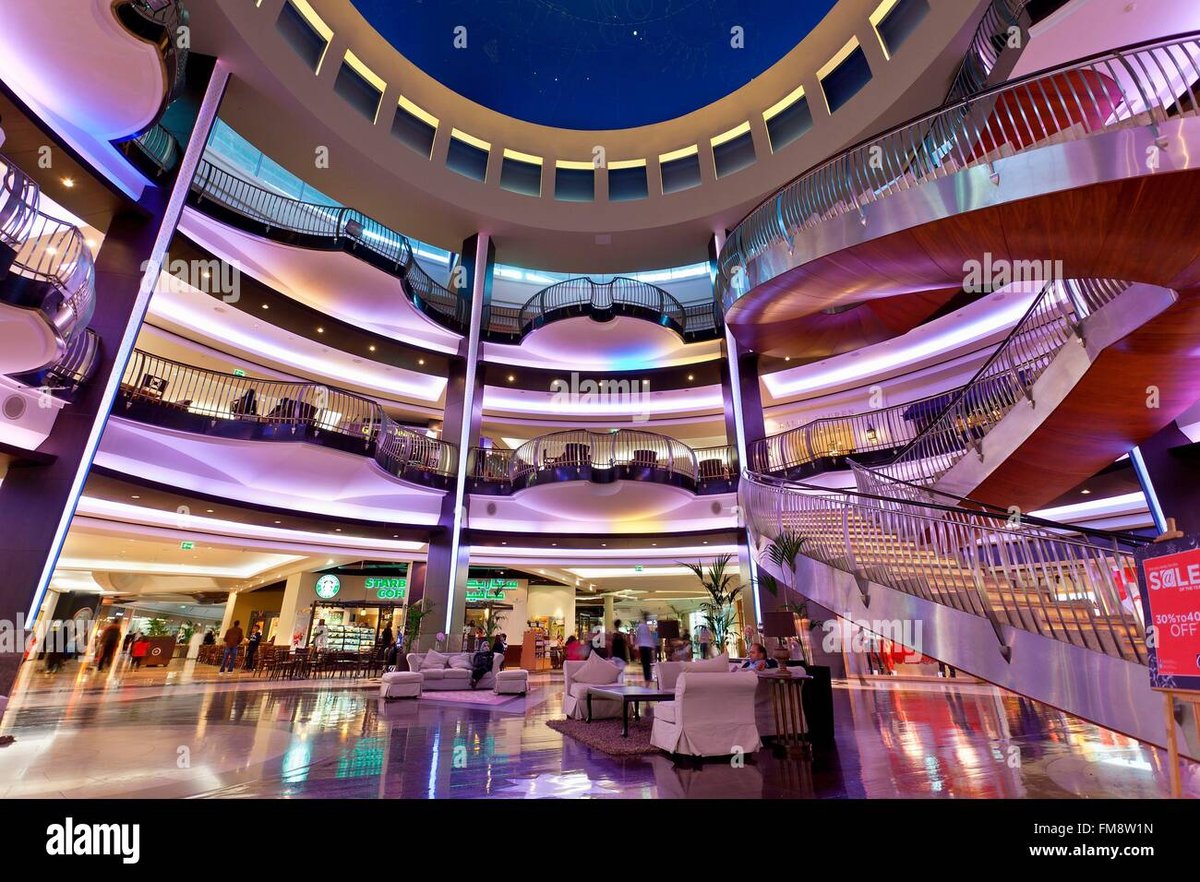
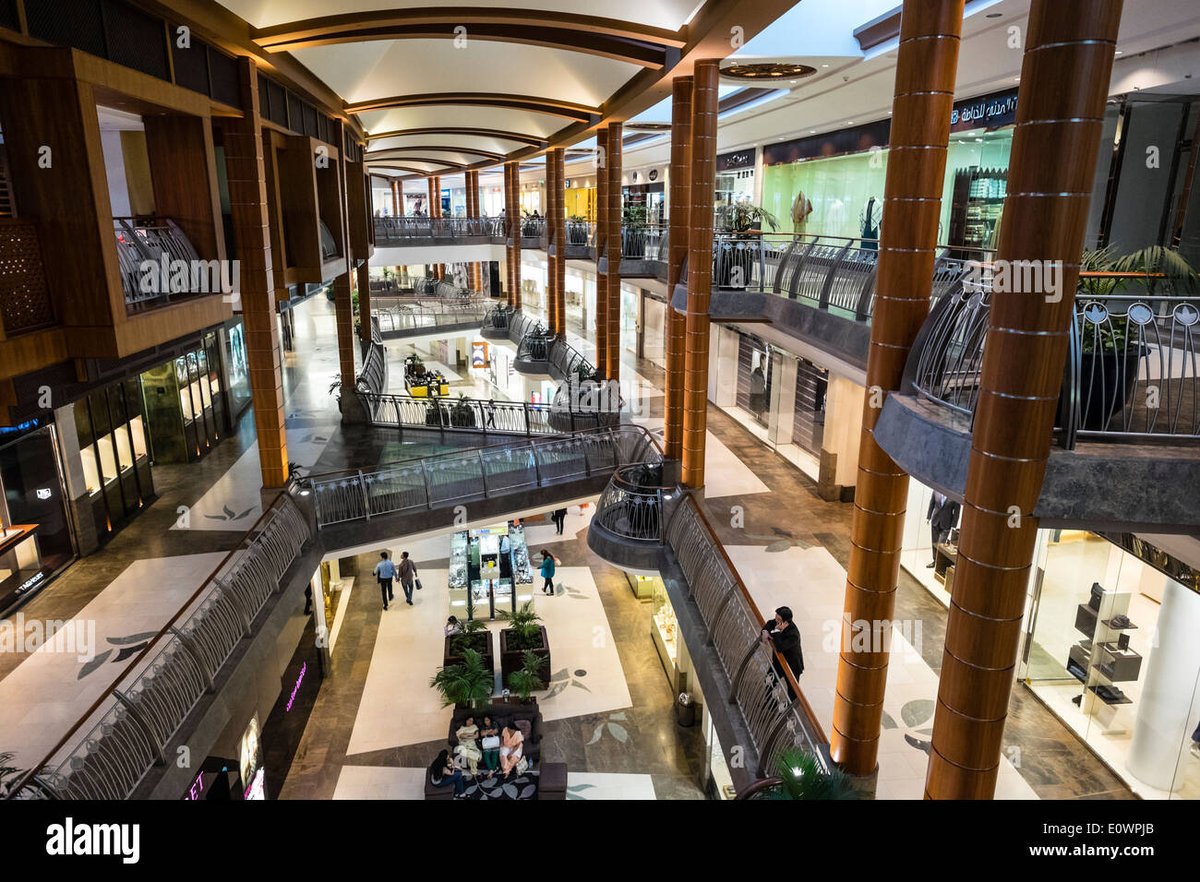
Operational quality has improved post-renovation, with modern HVAC, security, and event spaces boosting visitor dwell time.
Leasing advantages include flexible terms for mid-sized retailers, co-tenancy protections, and marketing support from Emaar. However, challenges include competition from mega-malls like Dubai Mall (15 million+ annual visitors) and Mall of the Emirates, potentially diluting footfall estimated at 8-10 million annually. The surrounding demographic is diverse, with 40% locals, 50% South Asian expats, and 10% tourists, but income levels are moderate (AED 10,000-20,000 household monthly), favoring value-oriented categories over ultra-luxury.
Market saturation in jewelry and electronics poses risks, alongside occasional access issues during peak traffic hours.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 11:00 PM |
| Saturday | 10:00 AM — 11:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
BurJuman draws from a diverse demographic profile in Bur Dubai, including 40% Emirati and Arab locals, 50% expatriates primarily from South Asia and the Philippines, and 10% international tourists attracted by nearby heritage sites. Household incomes average AED 10,000-20,000 monthly, supporting mid-market retail. Annual footfall is estimated at 8-10 million visitors, up 15-20% in 2025 due to transformations, though moderate compared to prime malls' 20+ million. Proximity to residential areas like Al Karama and Al Satwa ensures steady local traffic, but tourist influx varies seasonally, peaking during winter months. This mix supports stable performance for everyday essentials and affordable luxury, yet limits high-end sales potential amid broader Dubai market growth of 5-7% in retail sales per H1 2025 reports.
Tenant Mix and Competition
The tenant mix emphasizes jewelry (25% of space, leveraging Gold Souk synergy), fashion (30%), electronics (15%), and F&B (20%), with anchors like Carrefour and Virgin Megastore driving traffic. Recent additions post-2024 include experiential retail like pop-up zones and wellness outlets, enhancing diversity. However, competition is intense from nearby City Centre Mirdif and distant Dubai Mall, which offer superior variety and entertainment, capturing 60% more footfall. Weak categories include luxury fashion, where saturation and e-commerce erode shares. Operational synergies with Emaar's portfolio provide cross-promotions, but secondary positioning risks tenant churn if footfall growth stalls below 10% annually.
Lease Terms and Risks
Leasing terms feature base rents of AED 1,500-3,000 per sqm/year, plus 10-12% turnover rent, with incentives like 3-6 months free rent for new tenants and fit-out contributions up to AED 500/sqm. Minimum guarantees and co-tenancy clauses protect against anchor vacancies, common in Dubai's 95%+ occupancy environment. Risks include aging infrastructure pre-transformation, now mitigated but requiring ongoing capex; access challenges from congested Oud Metha roads during rush hours; and market saturation in jewelry/electronics, with 15% vacancy risk if tourism dips below 8 million visitors citywide. Economic factors like oil price volatility impact expat spending, potentially capping rent escalations at 5% annually per 2025 forecasts.
Building Details
Detailed Market Analytics
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Dubai
Discover more shopping centers in Dubai.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city