Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
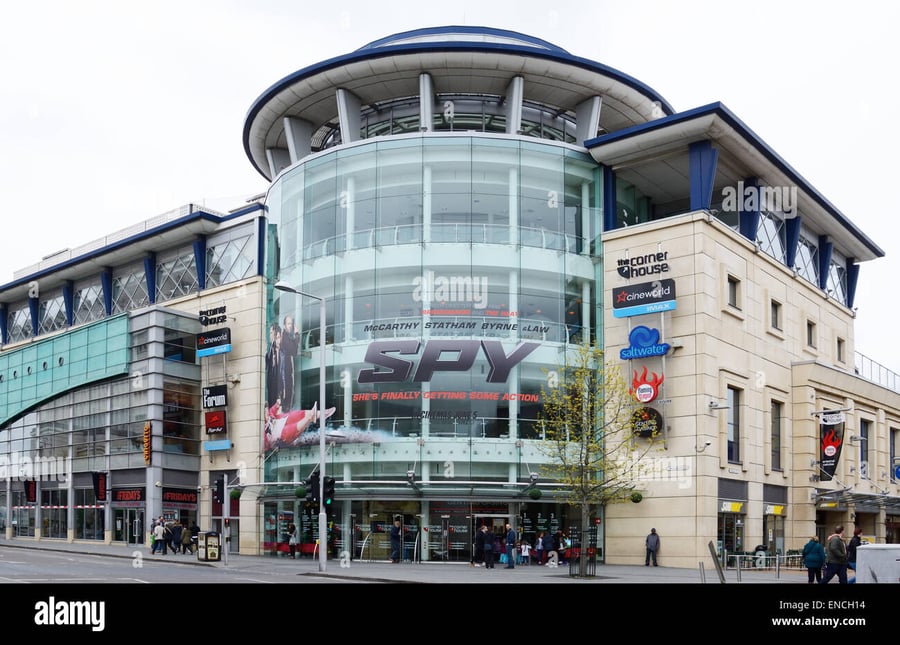
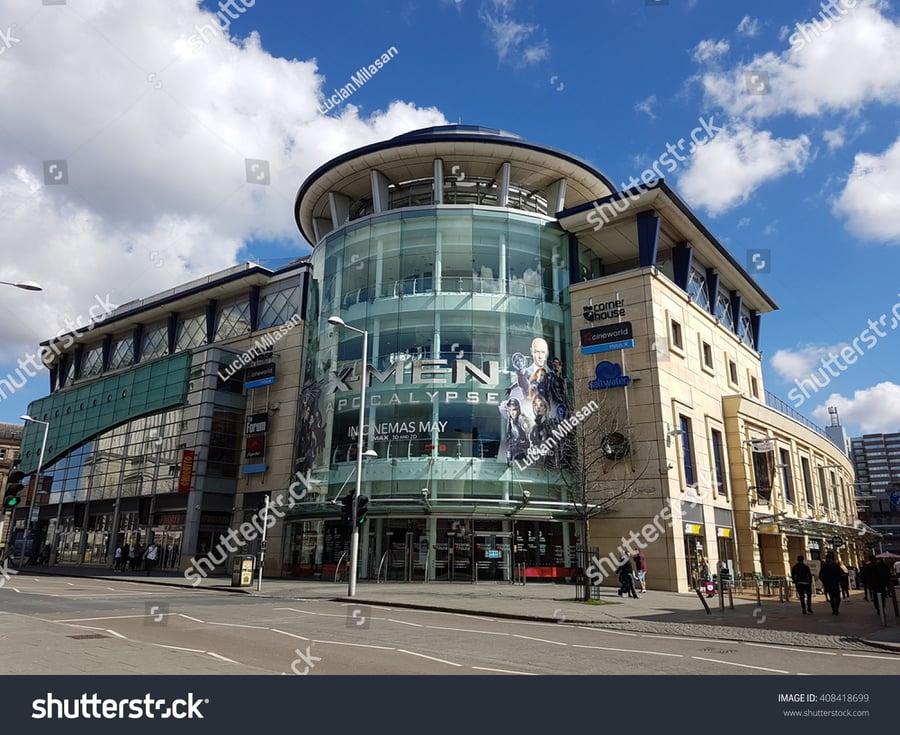
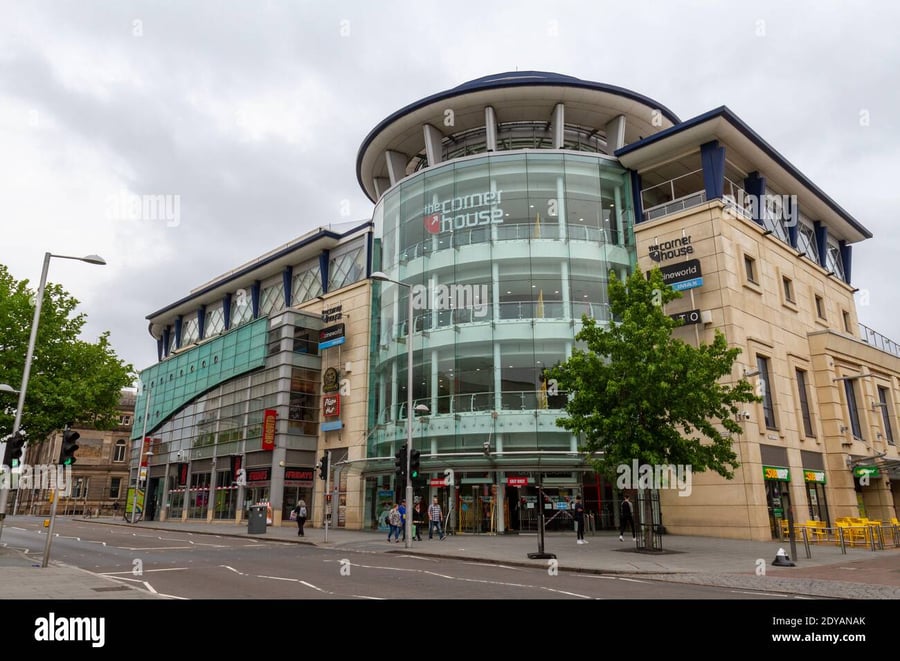
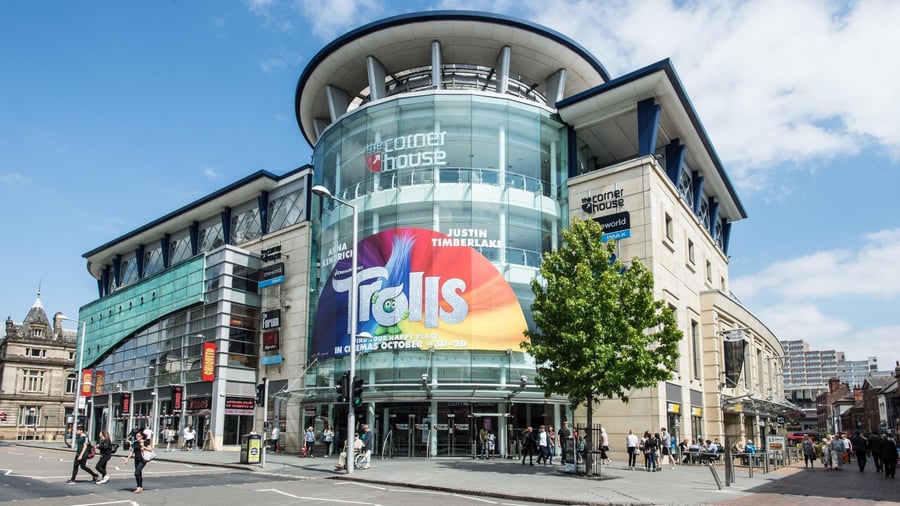
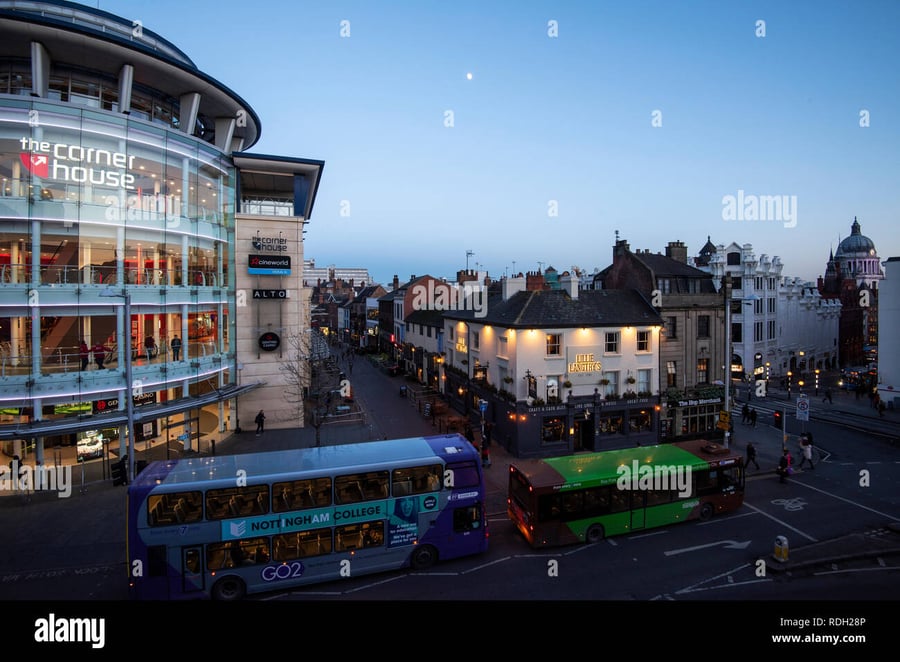
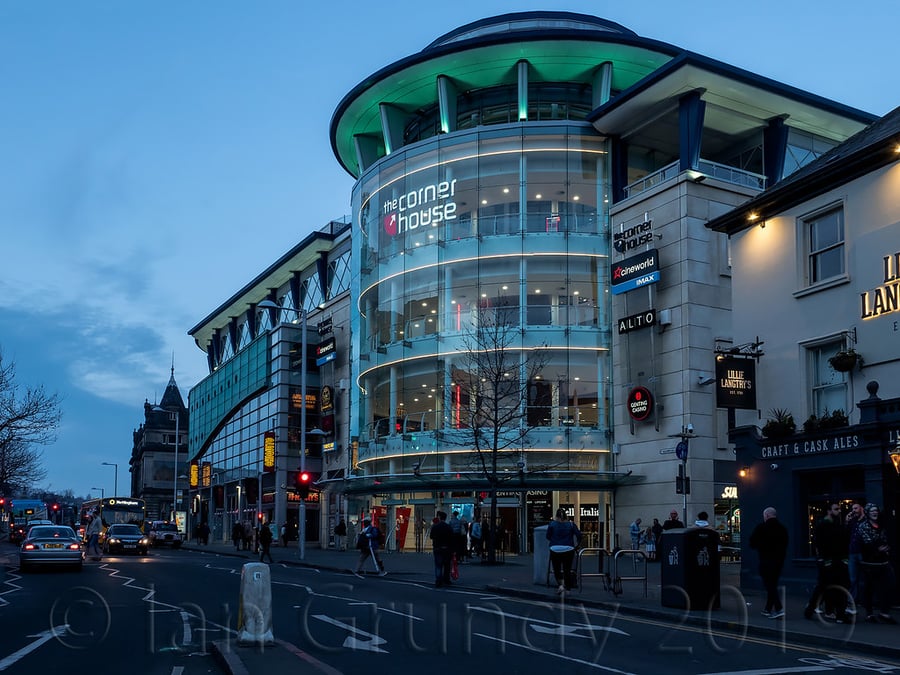
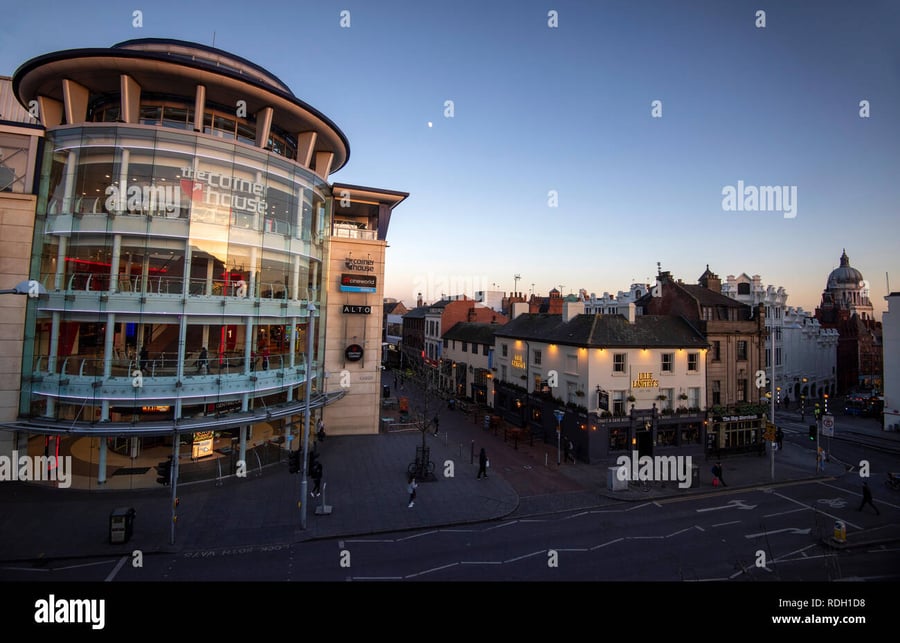
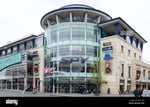
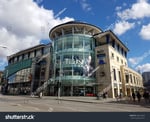
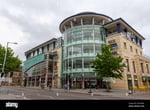
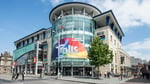
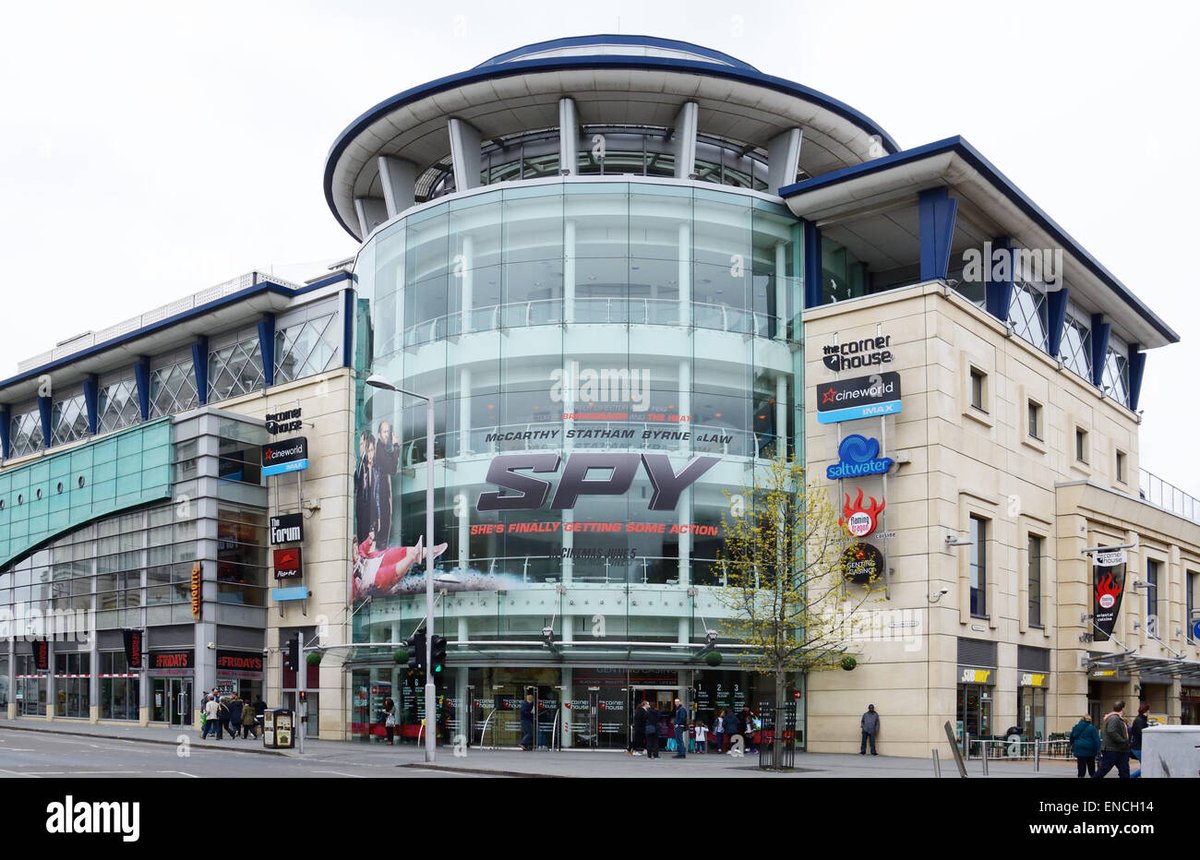
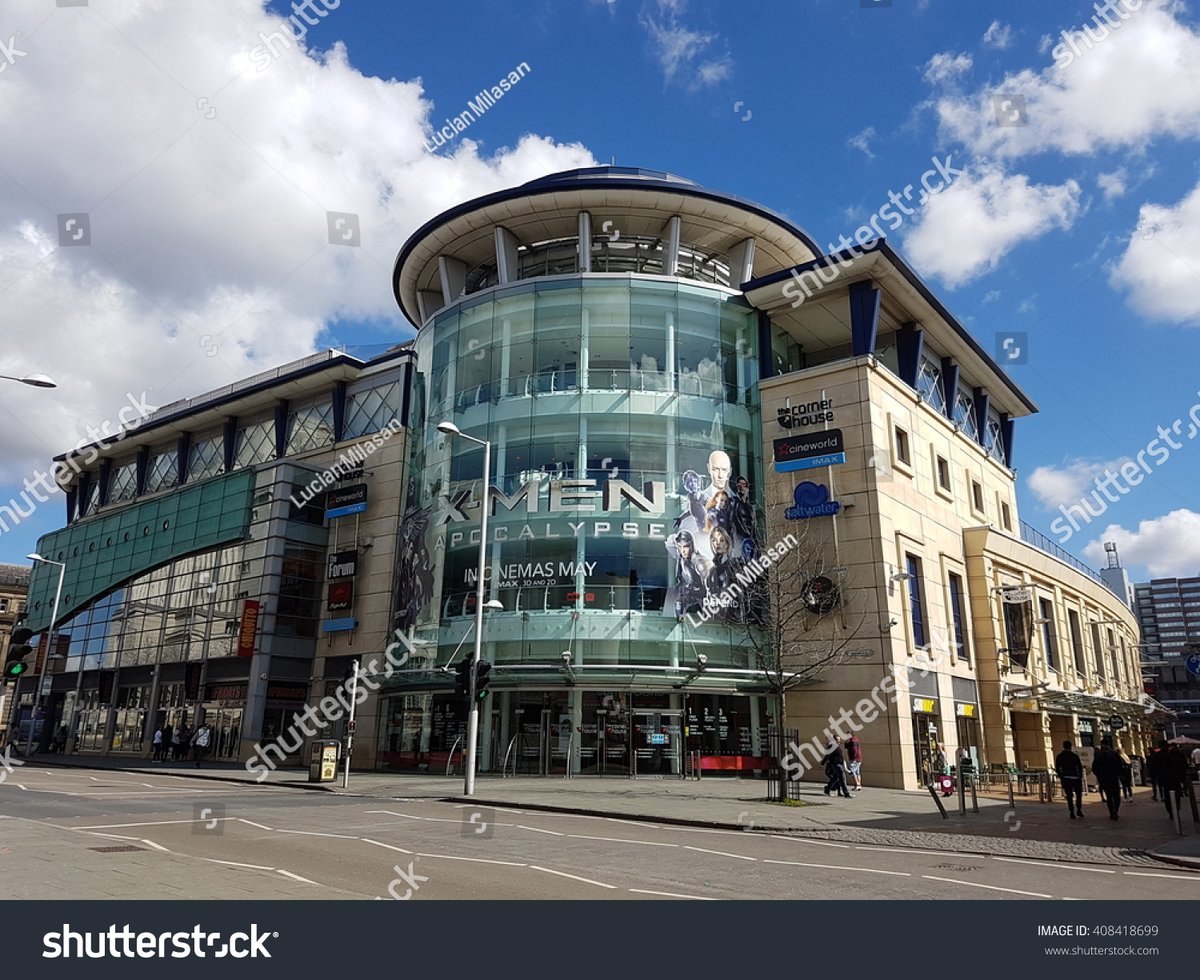
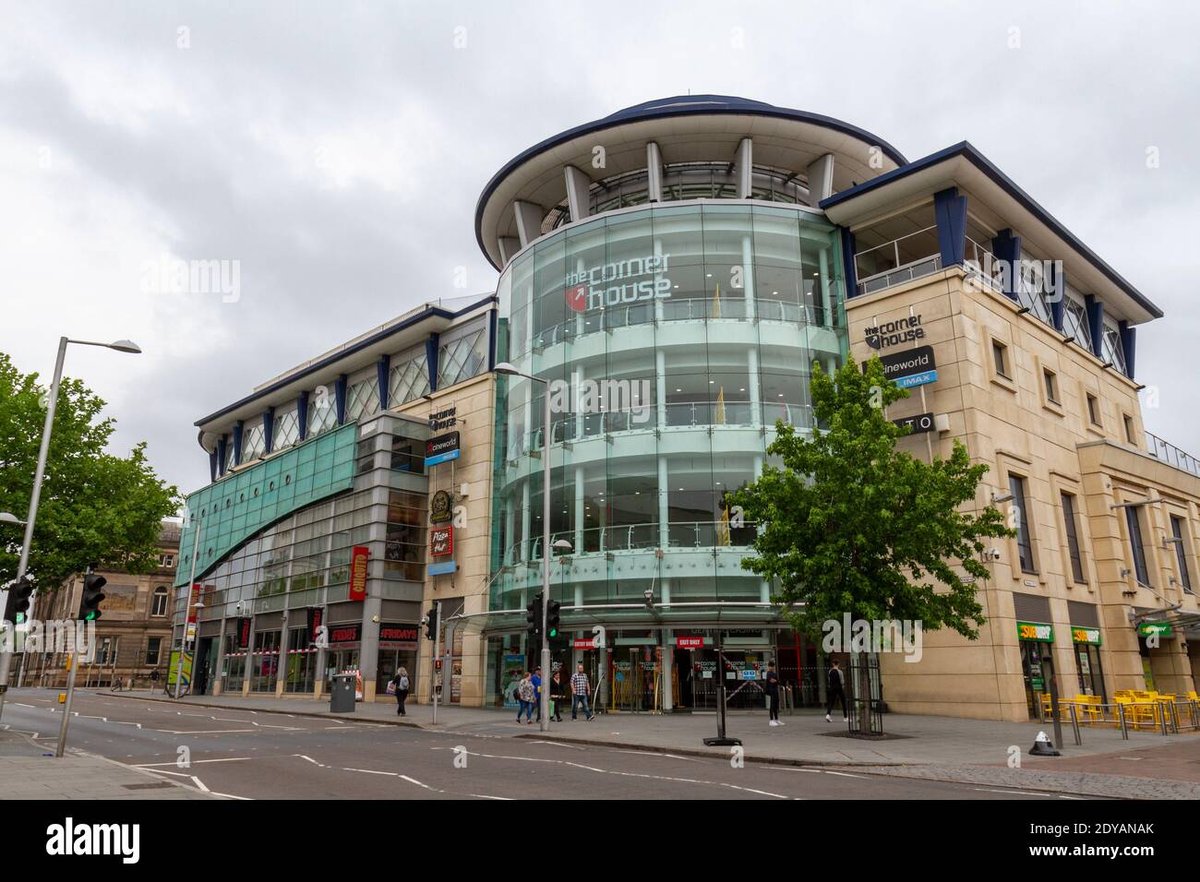
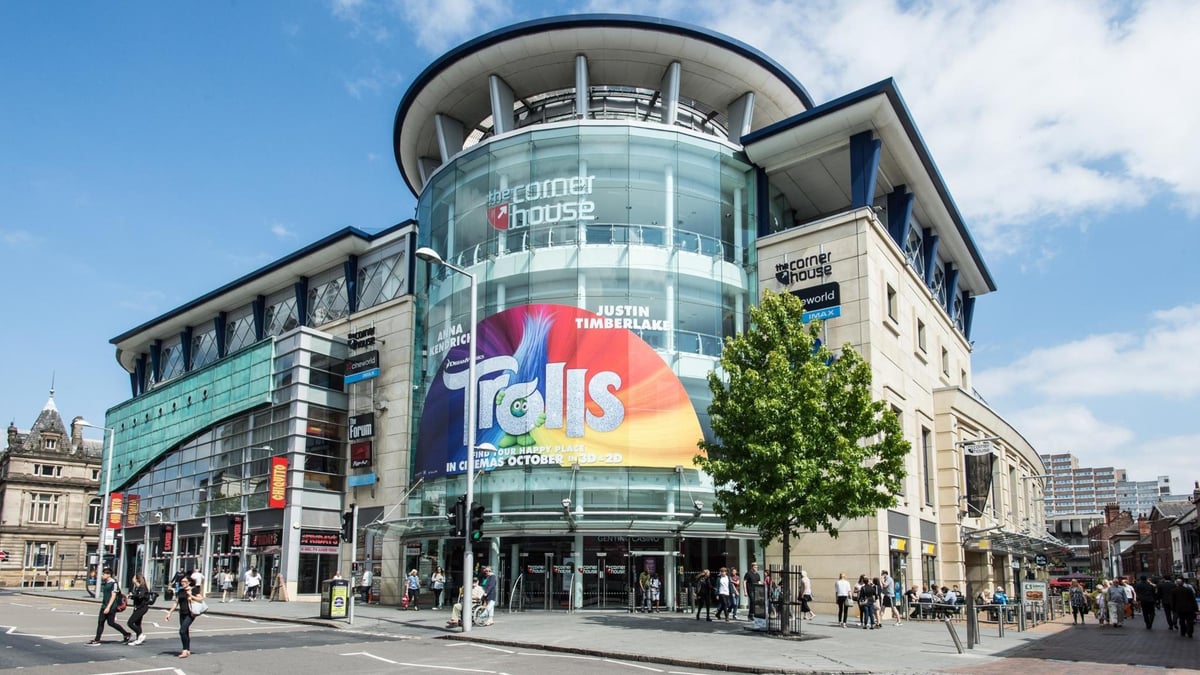
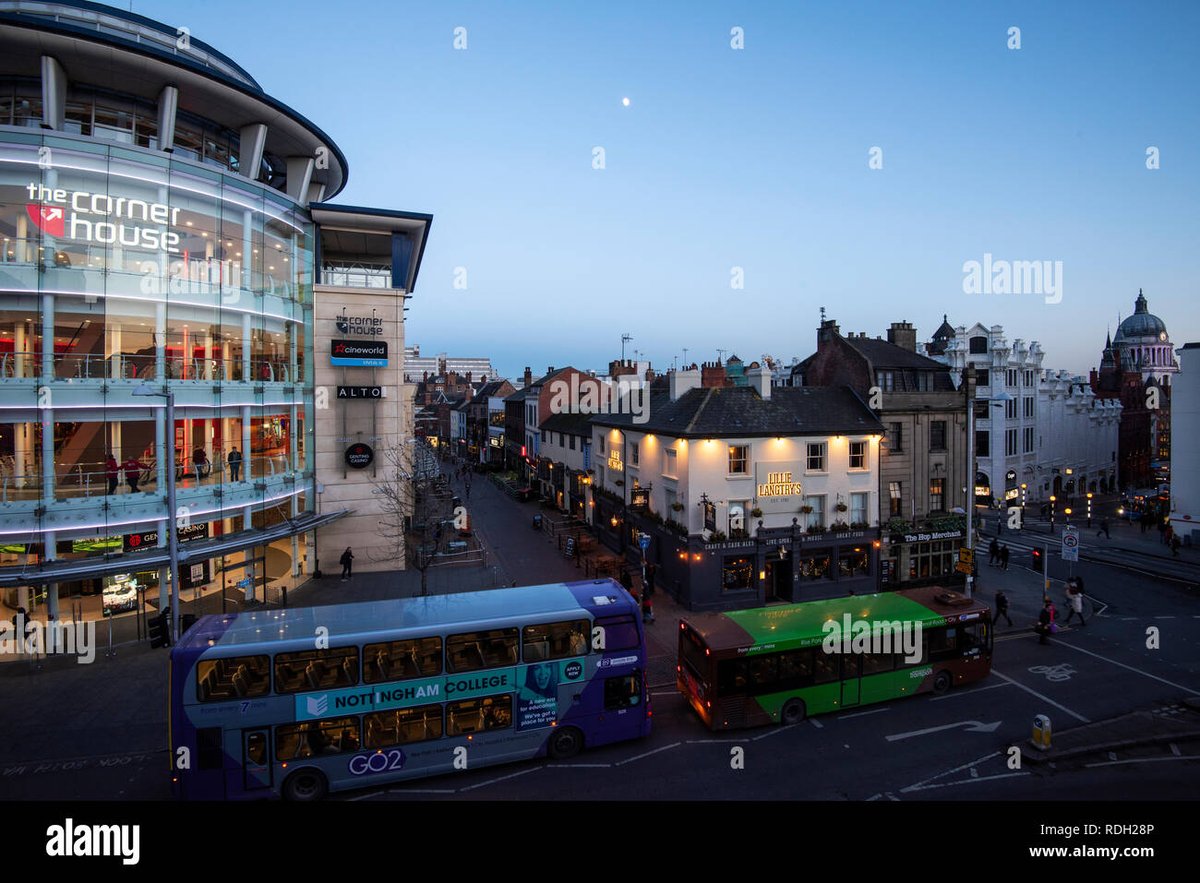
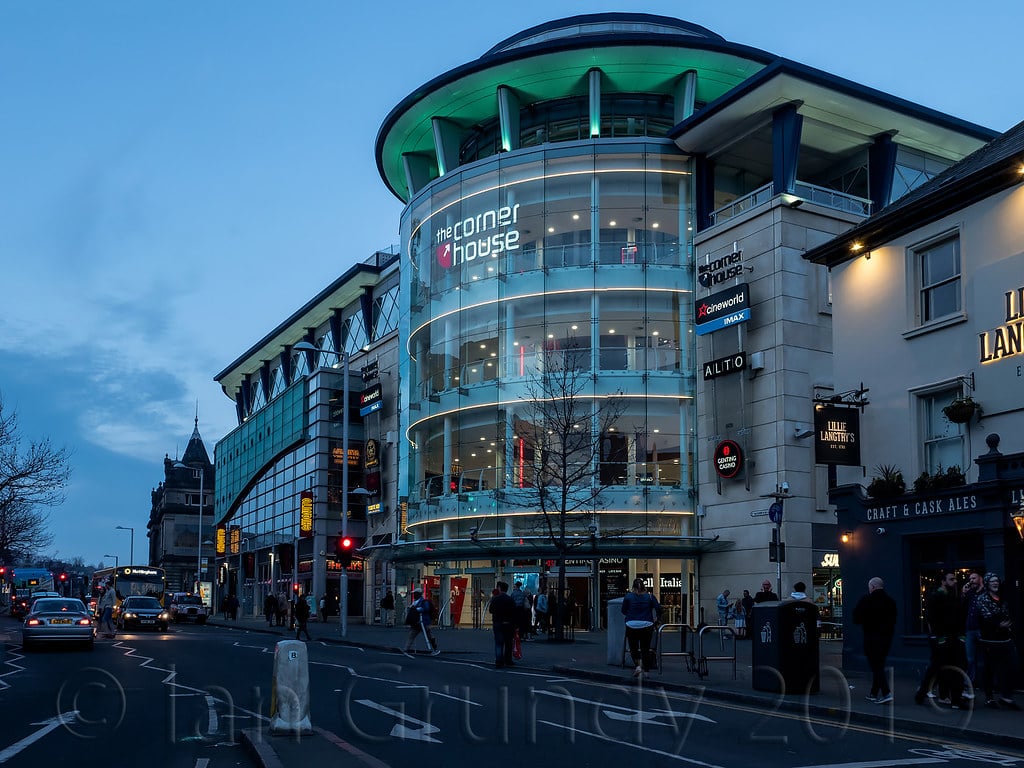
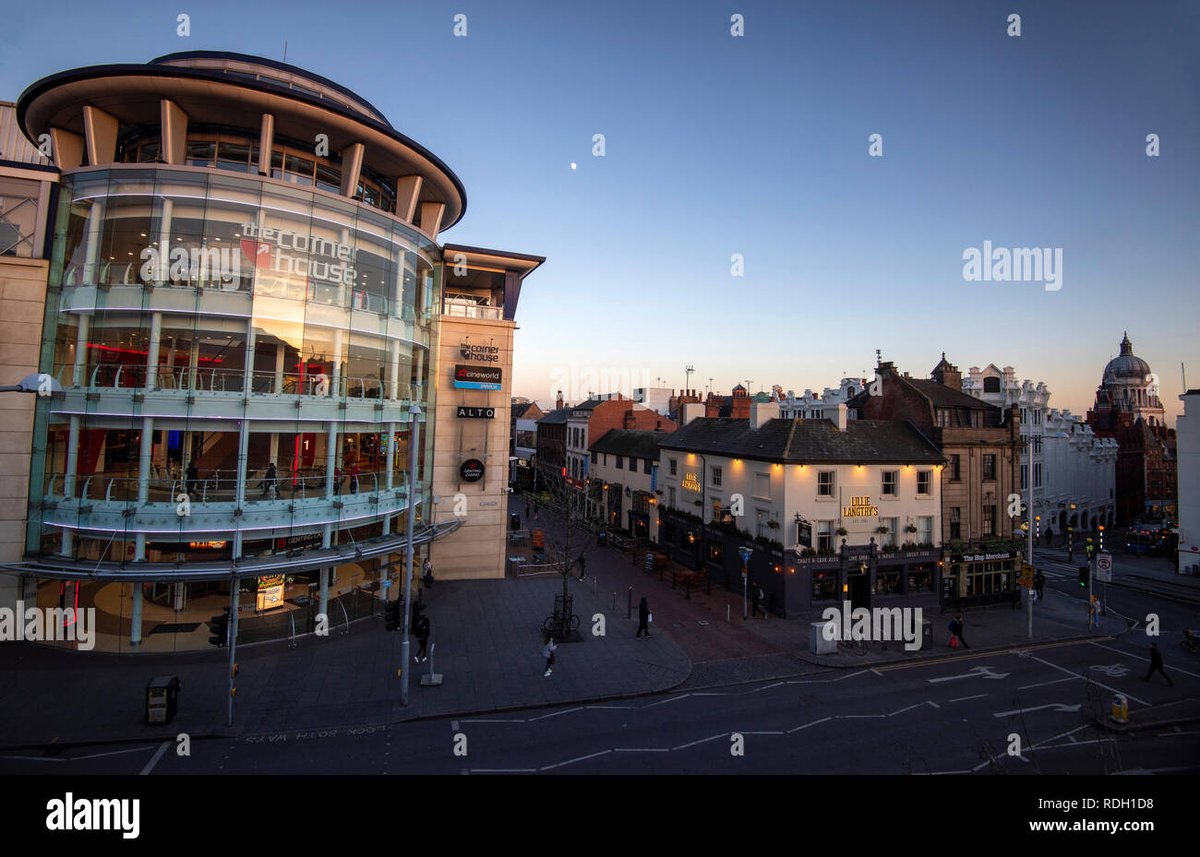
The Cornerhouse is a 200,000 sq ft multi-let leisure and entertainment complex located in the heart of Nottingham city centre, opposite the Theatre Royal Concert Hall and within walking distance of Nottingham Trent University and Nottingham railway station. Opened following a 50 million GBP redevelopment in 2022, it serves as the citys premier destination for leisure activities, drawing visitors for dining, cinema, gaming, and nightlife.
The tenant mix emphasizes food and beverage outlets, entertainment venues, and experiential leisure, with key occupiers including Vue Cinemas as the anchor with a 14-screen IMAX facility, Nandos, Wagamama, TGI Fridays, Slug and Lettuce, Revolution bar, Genting Casino, Roxy Ballroom for axe throwing and gaming, Funstation arcade, and Lost City Adventure Golf. Retail elements are limited, focusing instead on complementary leisure retail like arcade prizes.
Nottingham city centre benefits from robust footfall, with a 2.1 percent increase in 2024 compared to 2023, and climbed 64 places in UK retail rankings by 2025, driven by its comparison retail, leisure offer, and anchors. Occupancy remains high at approximately 95 percent based on recent lettings, supported by strong demand for leisure spaces amid post-pandemic recovery.
Leasing advantages include prime visibility from multiple city centre angles, high dwell time from entertainment draws boosting adjacent sales, flexible unit sizes from 1,000 to 10,000 sq ft suitable for pop-ups or full-service operators, and access to a young, affluent demographic including 50,000 students. However, rents are zone A around 50-70 GBP per sq ft, reflecting premium positioning but requiring high turnover to justify.
Market factors include improving vacancy rates below national averages at 10-12 percent in the city centre, yet competition from nearby Victoria Centre for shopping and online entertainment poses risks. Infrastructure is modern post-refurb, with excellent accessibility via trams, buses, and 1,200 parking spaces nearby, though pedestrian access can be affected by city centre events or construction.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
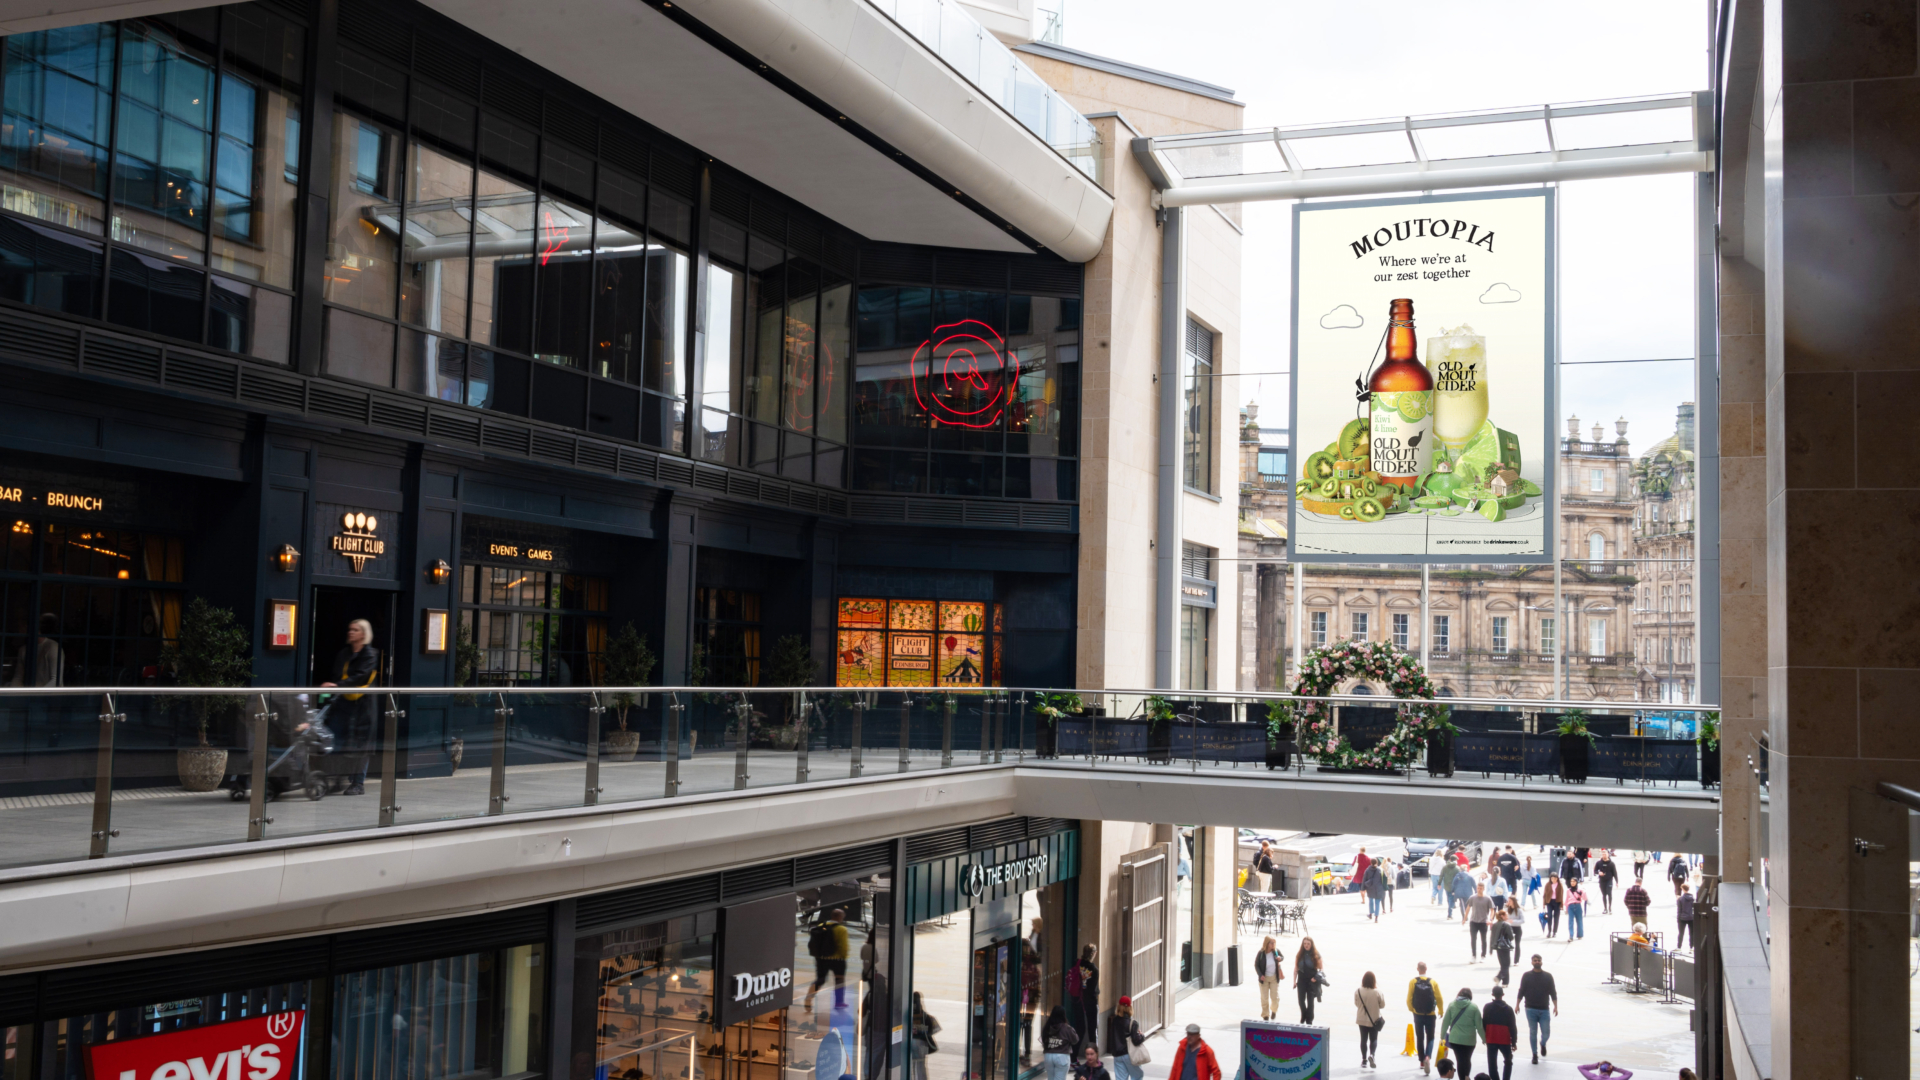
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 11:00 PM |
| Tuesday | 09:00 AM — 11:00 PM |
| Wednesday | 09:00 AM — 11:00 PM |
| Thursday | 09:00 AM — 11:00 PM |
| Friday | 09:00 AM — 11:00 PM |
| Saturday | 09:00 AM — 11:00 PM |
| Sunday | 09:00 AM — 11:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Footfall and Accessibility
Nottingham city centre recorded average weekly footfall of over 1.2 million visitors in 2024, with The Cornerhouse benefiting from its central location opposite cultural venues like the Theatre Royal, which attracts 300,000 annual attendees. Proximity to Nottingham railway station (five-minute walk) and tram lines ensures 70 percent of visitors arrive by public transport, reducing reliance on parking. However, peak evening footfall surges to 150,000 on weekends, driven by leisure, but daytime lulls outside university terms (September-June) can impact retail performance, with overall accessibility rated high yet vulnerable to traffic congestion during events.
Tenant Mix and Occupancy
The tenant mix at The Cornerhouse is leisure-dominant, with 60 percent food and beverage (Nandos, TGI Fridays, Wagamama), 30 percent entertainment (Vue Cinemas, Roxy Ballroom, Genting Casino), and 10 percent ancillary retail like arcades. Occupancy stands at 95 percent following the 2025 Vue letting, up from 85 percent pre-refurb, indicating strong demand for experiential uses. This composition supports high dwell times of 2-3 hours per visit, enhancing cross-spending, but limits traditional retail synergy, potentially challenging non-leisure tenants amid a 15 percent city-wide leisure vacancy drop in 2024.
Market Risks and Demographics
The primary catchment includes a 330,000 population within 30 minutes drive, with a young median age of 28 years, 15 percent students, and average household income of 32,000 GBP, favoring affordable leisure and casual dining. Competition arises from Victoria Centre (500,000 sq ft retail) and intu Broadmarsh redevelopment, capturing 40 percent of city shopping spend, while online streaming erodes cinema attendance by 10 percent annually. Risks include market saturation in F&B with 20 new outlets city-wide in 2024, aging high street infrastructure nearby, and economic pressures raising operational costs by 8 percent. Opportunities lie in leisure resilience, with sector sales up 5 percent in 2025.
Building Details
Detailed Market Analytics
City Snapshot
Nottingham, NTT
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Nottingham
Discover more shopping centers in Nottingham.

Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Nottingham, NTT
Comprehensive market intelligence for retail expansion in this city