Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
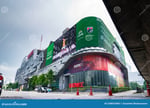
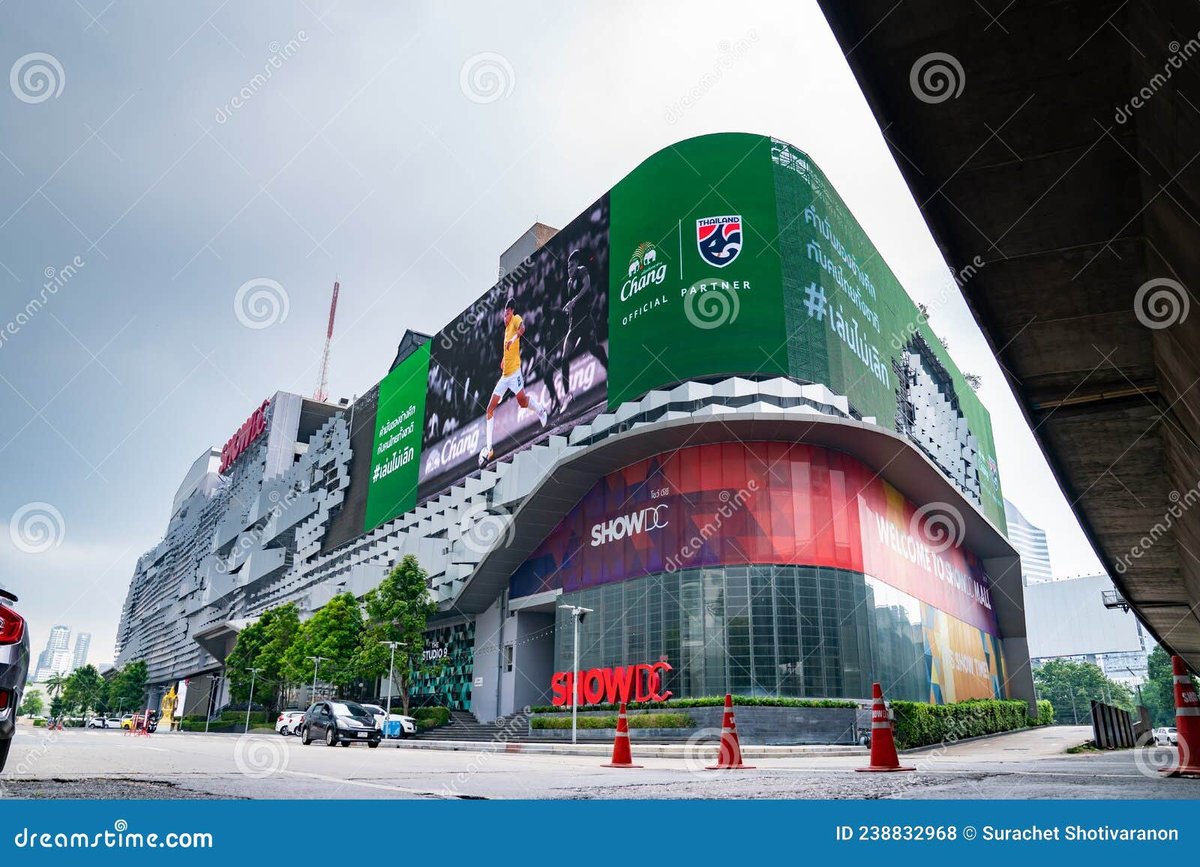
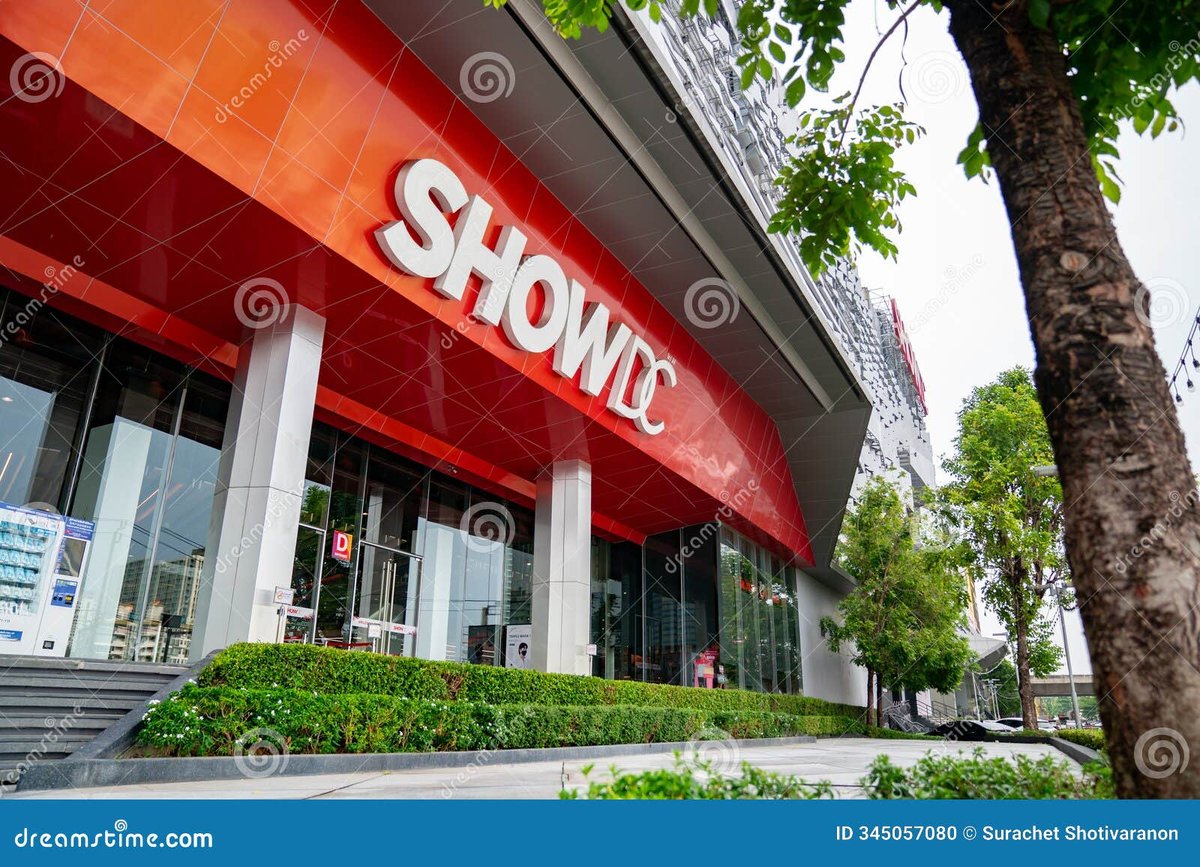
The Base Rama 2 is a mid-sized community shopping center located along Rama II Road in the Bang Khun Thian district of Bangkok, Thailand, approximately 20 kilometers southwest of the city center. Opened in 2014 and developed by TCC Assets (Land & Houses Group), it spans about 35,000 square meters of gross leasable area (GLA) across three levels, focusing on everyday retail, dining, and leisure for local residents.
The tenant mix emphasizes value-oriented fashion outlets like Uniqlo and H&M-inspired local brands, a Robinson Department Store anchor, a Major Cineplex cinema, and a diverse food court with over 50 vendors offering Thai, international, and fast-casual options. Supermarket presence includes a Tops Daily outlet, supporting grocery needs.
Market positionally, it serves as a convenient hub for the growing suburban population in Rama II corridor, where residential developments have surged due to affordable housing. Footfall averages 15,000-20,000 visitors daily on weekdays, peaking at 30,000 on weekends, driven by proximity to housing estates and schools.
Occupancy rates hover around 92% as of recent JLL Thailand reports, reflecting stable demand in the non-prime segment.
Rent levels range from 800-1,200 THB per square meter per month for ground-floor spaces, competitive for secondary locations but lower than central Bangkok malls.
Accessibility is facilitated by BTS extensions in planning, though current reliance on personal vehicles and songthaews leads to moderate traffic congestion during peak hours.
Operational quality is solid with modern HVAC systems and ample parking for 1,200 cars, but the mall faces challenges from aging facade elements and seasonal flooding risks in the low-lying area.
Leasing advantages include flexible terms for pop-ups and short leases (1-3 years), lower fit-out costs compared to premium centers, and targeted marketing to 200,000+ local households with median incomes of 30,000-50,000 THB monthly. However, drawbacks encompass competition from nearby Big C Supercenter and Central Rama 2, which draw higher-spending crowds, and market saturation in budget retail categories.
Overall, it suits cost-conscious retailers targeting family-oriented demographics seeking community engagement over luxury experiences.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 11:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile
The primary catchment area encompasses 250,000 residents within a 5-kilometer radius, predominantly middle to lower-middle income families (household income 25,000-60,000 THB/month) employed in manufacturing, logistics, and services along the industrial Rama II belt. Age demographics skew towards 25-45-year-olds with children, supported by data from Thailand's National Statistical Office indicating 40% family units in Bang Khun Thian. High local loyalty stems from residential density, with 70% of visitors from nearby condos and townhomes developed post-2010. However, limited appeal to higher-income tourists or urban professionals due to suburban isolation poses risks for premium brands, potentially capping sales growth at 5-7% annually amid economic pressures on discretionary spending.
Competitive Landscape
Direct competitors include Central Rama 2 (larger at 100,000 sqm GLA, 15% higher footfall) and Seacon Square (entertainment-focused, drawing regional crowds), both within 5-10 km, intensifying rivalry for apparel and F&B categories per CBRE Thailand's 2023 retail report. The Base differentiates via localized tenant mix and lower pricing, achieving 85% tenant retention, but faces pressure from e-commerce penetration (20% sales shift) and informal markets nearby. Market saturation in grocery and casual dining results in 10-15% vacancy risks for similar spaces, advising lessees to prioritize unique concepts to avoid overlap and ensure 10-15% ROI thresholds.
Leasing Metrics and Risks
Base rents average 900 THB/sqm/month for prime zones, with turnover rents at 8-10% of sales, offering flexibility for emerging retailers; escalation clauses cap at 5% annually, per typical TCC lease structures. Operational costs add 200-300 THB/sqm for CAM fees, covering security and maintenance at 95% uptime. Advantages include 6-month build-out periods and co-op marketing budgets of 50,000 THB/quarter. Risks involve access bottlenecks from Rama II traffic (30-45 min delays) and infrastructure vulnerabilities like power outages during monsoons, potentially reducing footfall by 20%. Lessees should negotiate escalation pauses amid 3-4% Bangkok retail vacancy rates, ensuring alignment with projected 4-6% sales per sqm growth in suburban markets.
Building Details
Detailed Market Analytics
City Snapshot
Bangkok
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Bangkok
Discover more shopping centers in Bangkok.
Popular in Thailand
Top retail destinations across Thailand.



Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Bangkok
Comprehensive market intelligence for retail expansion in this city