Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
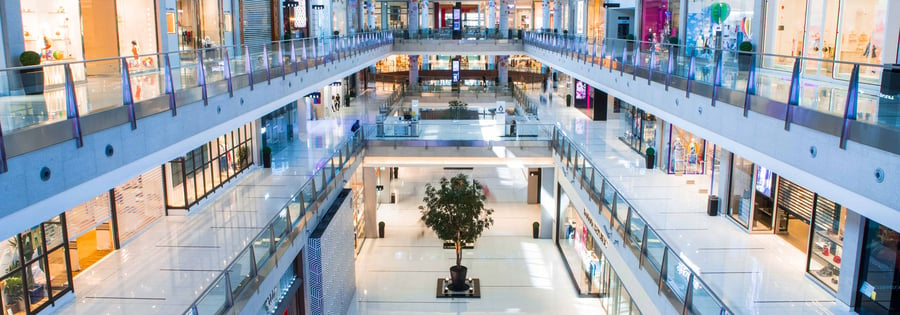
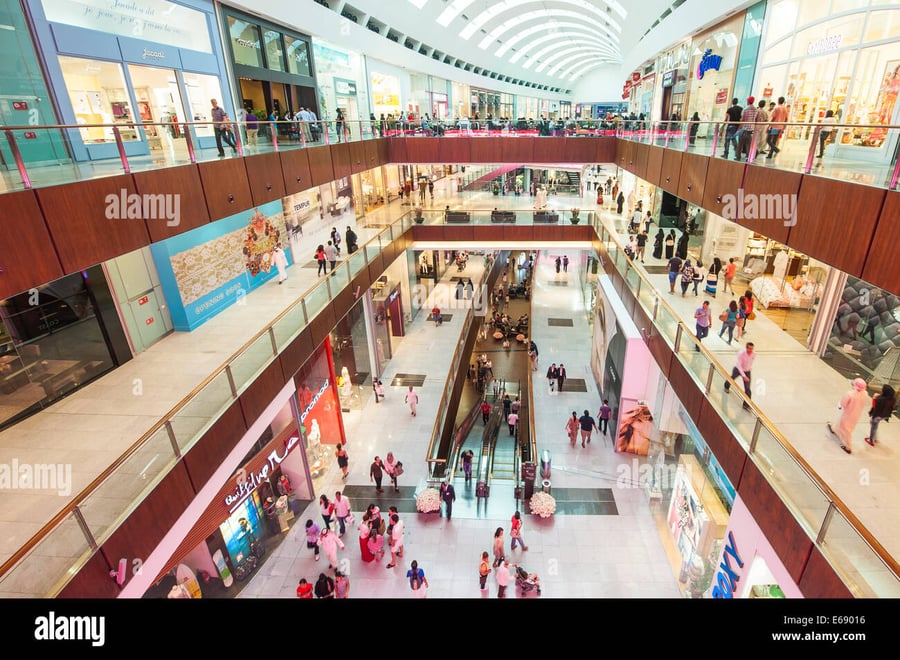
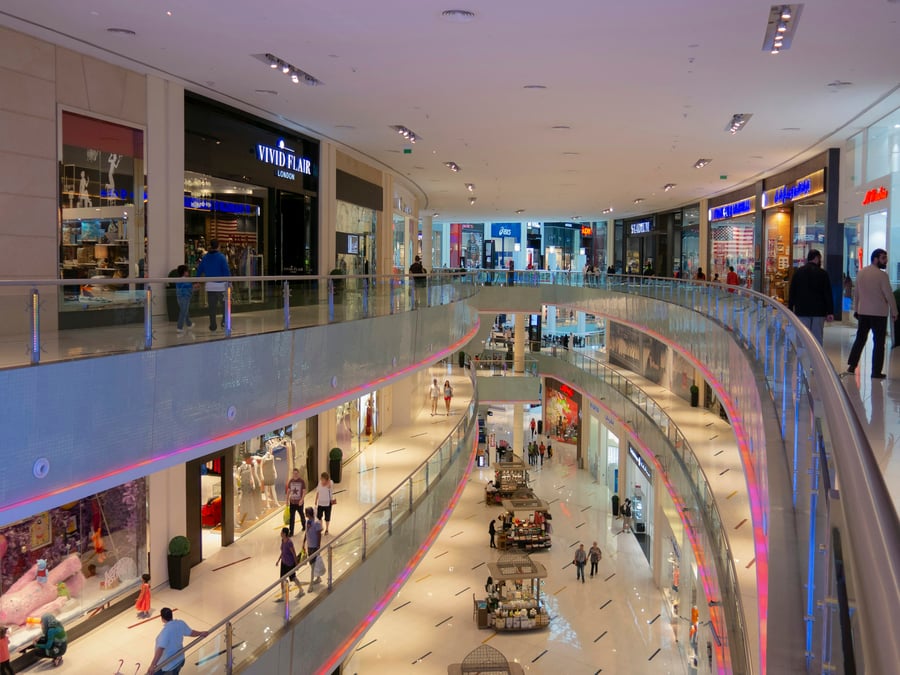
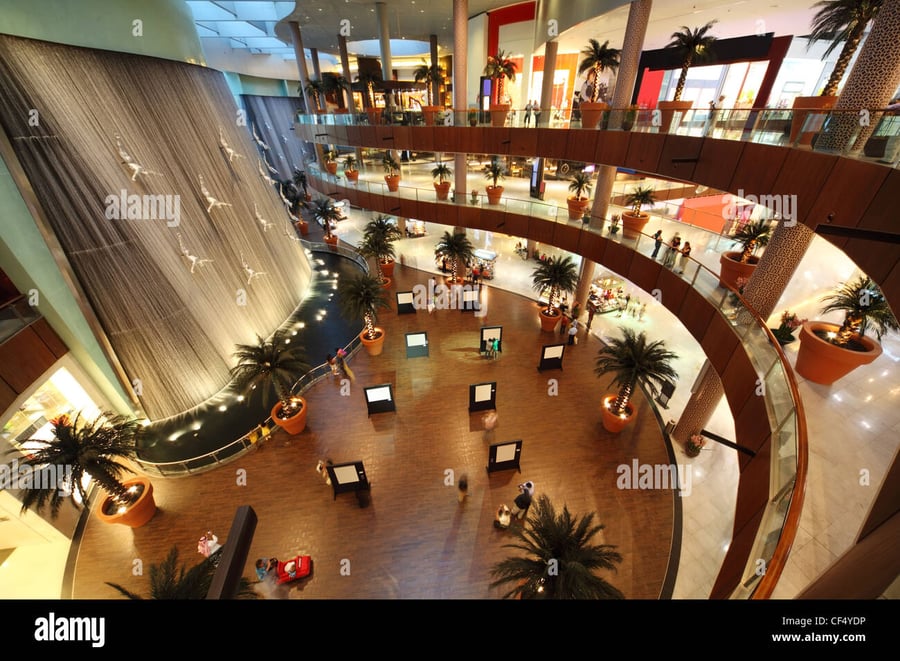
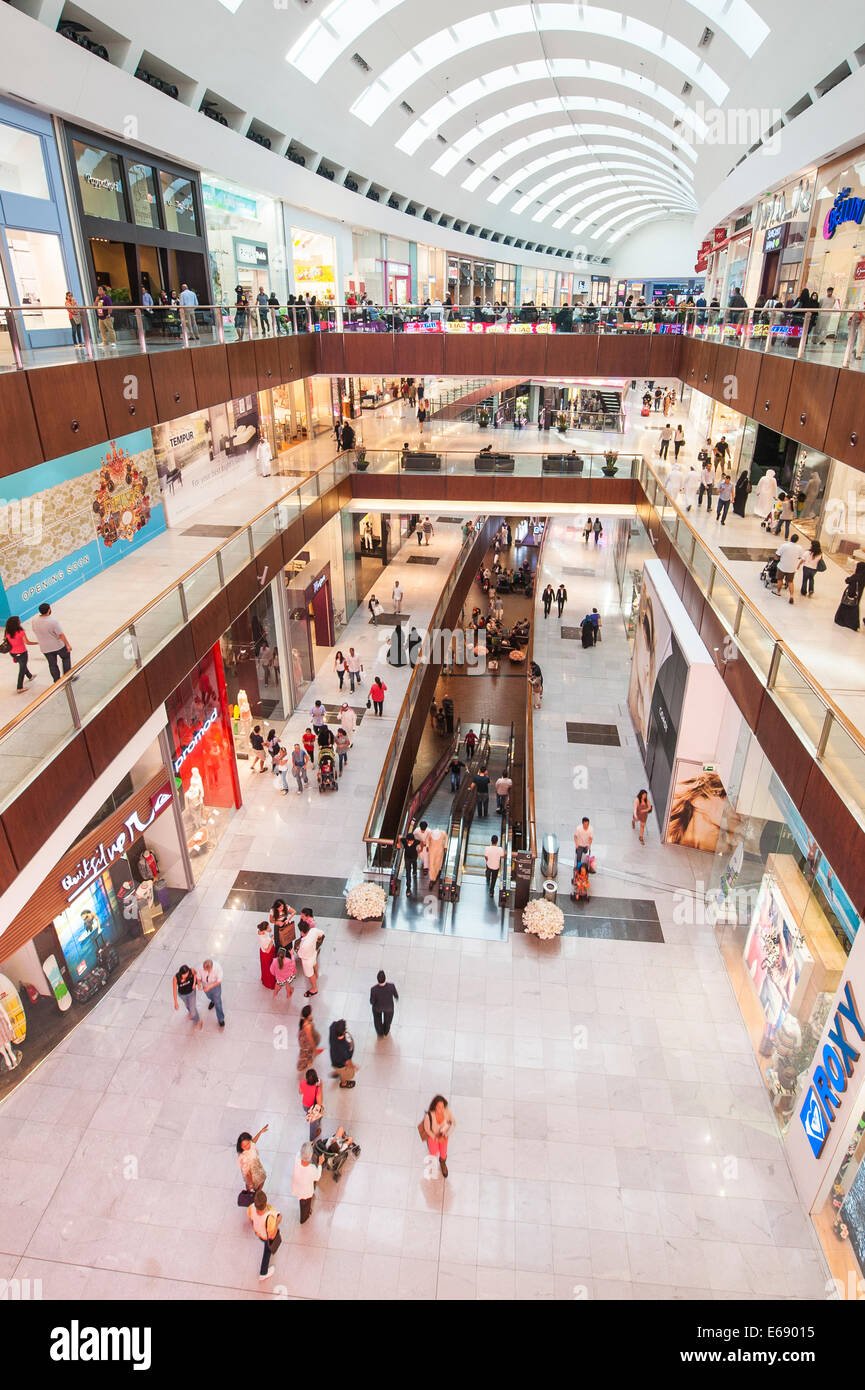
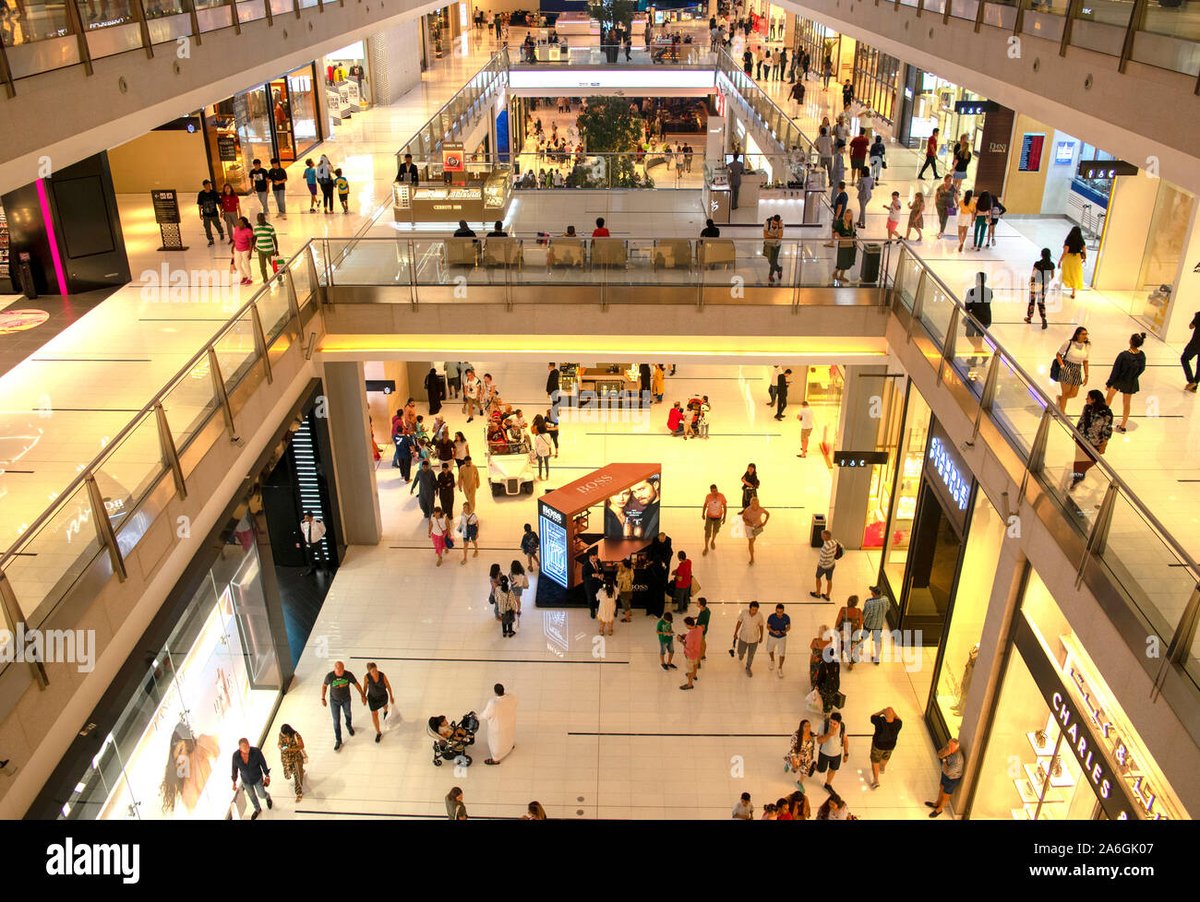
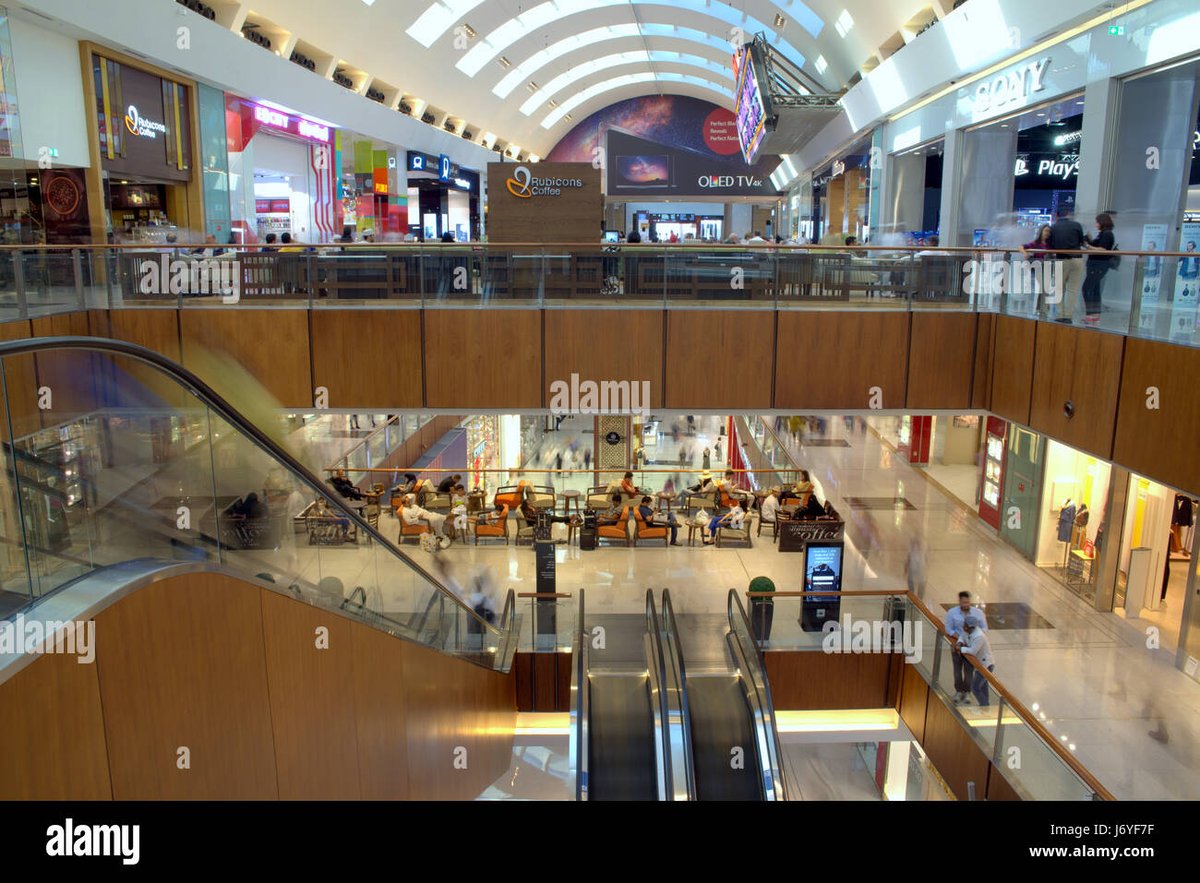
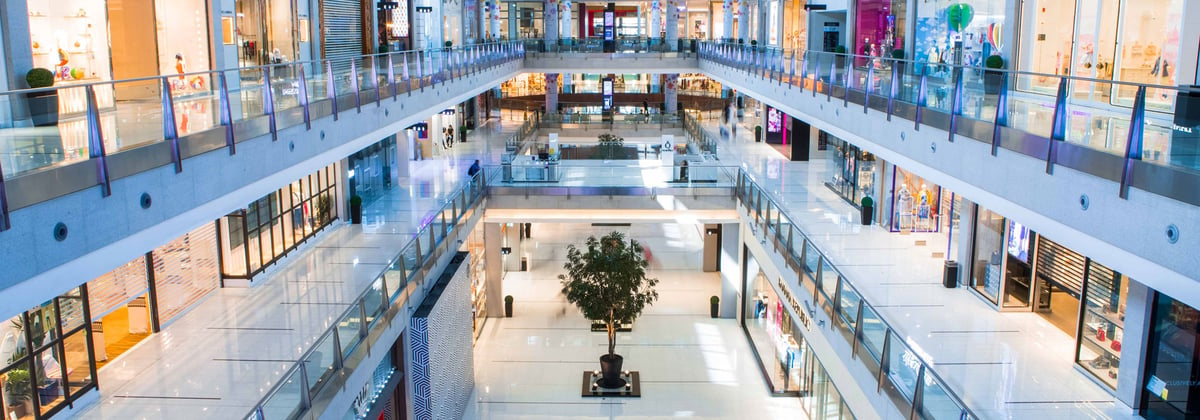
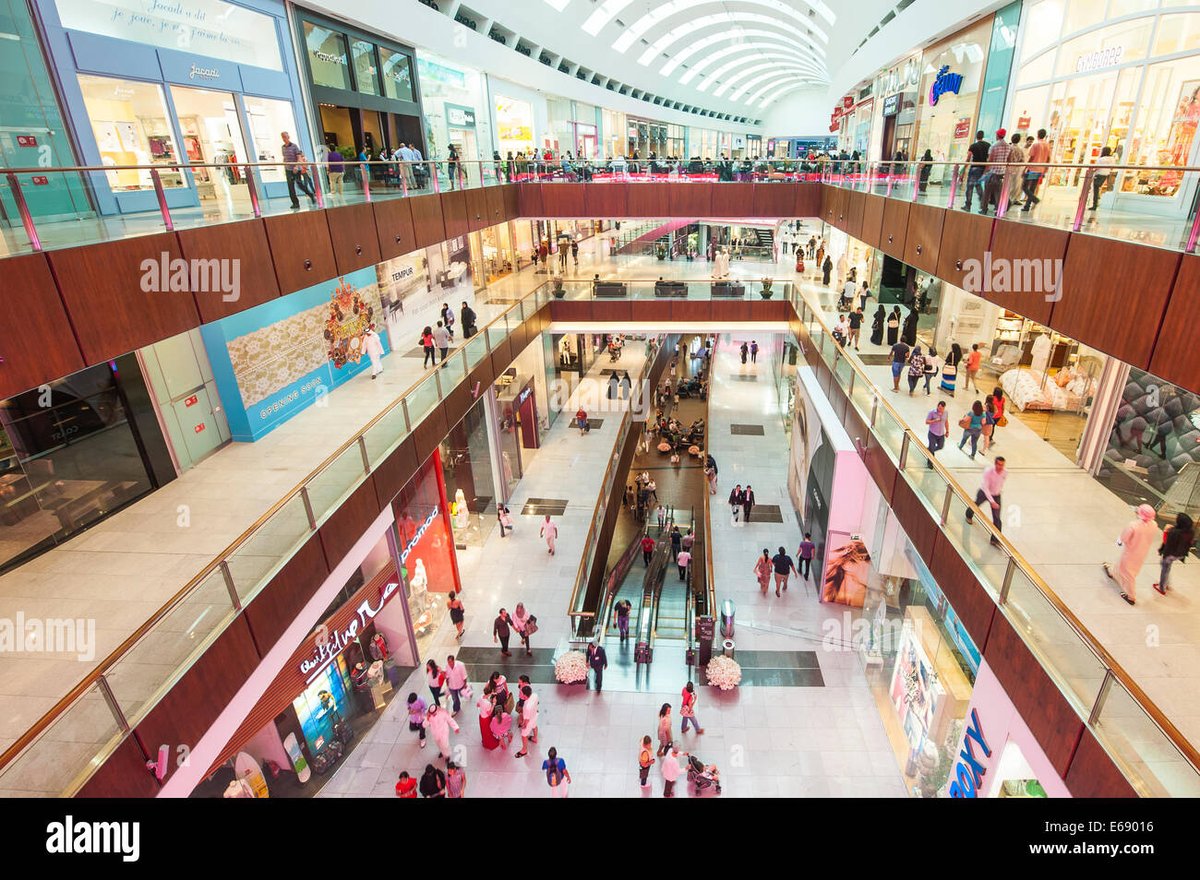
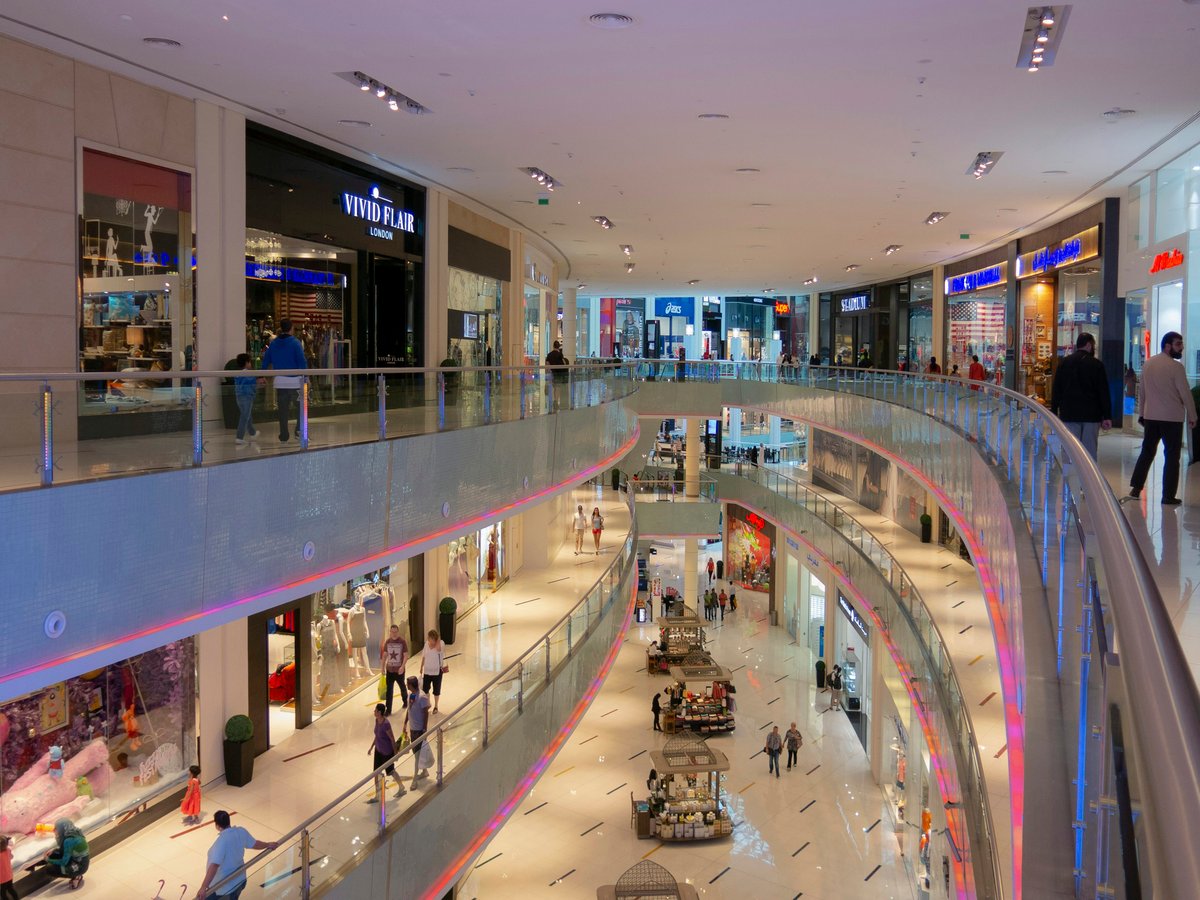
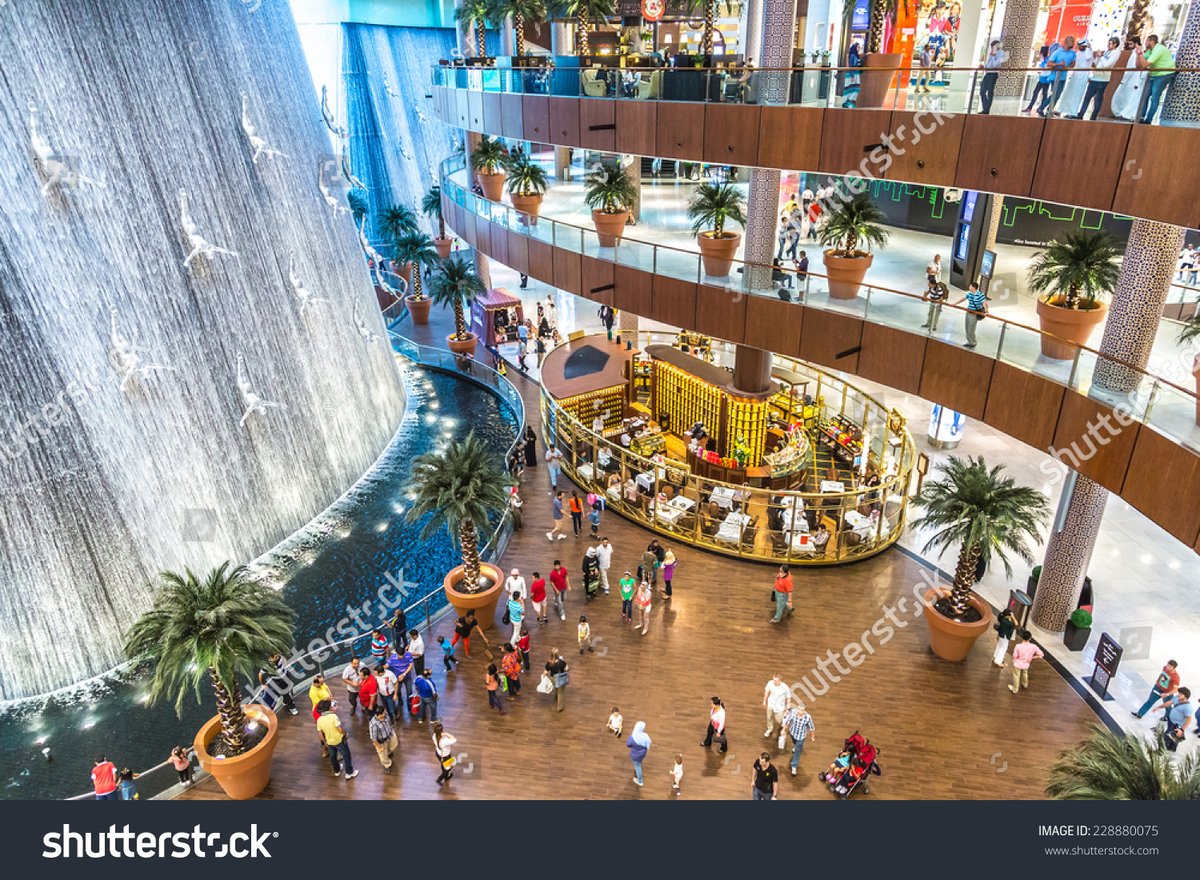
JLT Retail Centre is a decentralized retail hub in Jumeirah Lakes Towers (JLT), Dubai, developed by DMCC in 2008.
Spanning 45,000 sqm of gross leasable area across 26 clusters around artificial lakes, it functions as a neighborhood convenience center serving the DMCC free zone with 17,000 companies and nearby residential areas. The tenant mix emphasizes everyday essentials and services: 45% F&B outlets including multicultural cafes and restaurants (Greek, Asian, Levantine, Thai), 30% fashion and lifestyle stores, 15% services such as pharmacies, salons, spas, and childcare, and 10% other retail.
Anchors include Spinneys Waitrose and two Carrefour supermarkets, with over 470 F&B units and 80 stores total, featuring high diversity and 15 unique concepts. Occupancy stands at 95% with a 4% vacancy rate and 2,000 sqm available space. Daily footfall is 20,000 to 30,000, translating to 1.5 million annual visitors, with average dwell time of 2 hours and 25% conversion rate; sales average AED 12,000 per sqm yearly.
Rents are competitive at AED 150-250 per sq ft annually (AED 350 per sqm monthly for ground floor), lower than central malls AED 400+ per sqm, yielding 7-8%.
Accessibility is strong via DMCC Metro Station (1-minute walk), Sheikh Zayed Road buses, and 3,000 parking spaces. The primary catchment of 150,000 residents within 5 km comprises diverse expatriates, young professionals, and families (median age 33, household size 3.8, 65% tertiary educated, median income AED 240,000 annually), driving mid-tier spending (USD 11,000 per capita yearly on retail).
Market position is mid-tier in Dubais resilient retail sector, benefiting from 8% projected growth in 2025 due to expat influx and citywide 8.3% rent increases, but faces e-commerce pressure and seasonal summer heat.
Leasing advantages include flexible 3-5 year terms with turnover options, 5-7% annual escalations, monthly promotions, and 30% loyalty penetration. Challenges encompass fragmented layout reducing draw versus centralized malls, aging pre-2010 infrastructure increasing maintenance costs, F&B saturation, and medium competition from Dubai Marina, Ibn Battuta Mall, and Mercato, which offer broader entertainment.
Operational quality is supported by advanced security, digital signage, and ongoing tenant pipeline, though capacity strains from 6% population growth persist without full expansion.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 11:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics
The primary catchment area within 5 km includes 150,000 residents, predominantly diverse expatriates such as young professionals and families. Median age is 33 years, with household size averaging 3.8 persons; 65% hold tertiary education. Median annual household income is AED 240,000, supporting per capita retail spending of USD 11,000 yearly (USD 1,500 on apparel, USD 2,500 on groceries, USD 1,200 on electronics). Unemployment is low at 1.9%, and population growth is 6% annually. This profile favors convenience retail and F&B but limits luxury appeal due to mid-tier focus and local dependency on DMCC business traffic.
Competition
Competition is medium from nearby destinations like Dubai Marina, Ibn Battuta Mall, and Mercato, which provide broader entertainment, shopping variety, and higher tourist draw, potentially diluting footfall for F&B and convenience categories. High e-commerce rivalry, with 99% internet penetration and 40% click-and-collect adoption, pressures physical non-essential retail. Mid-tier positioning exposes it to market saturation in essentials, though adjacency to DMCC free zone sustains consistent business traffic amid Dubais overall mall occupancy exceeding 97%.
Lease Terms
Leases offer 3-5 year terms with flexible turnover options and 5-7% annual escalations, contributing to stable occupancy above 90%. Rents range AED 150-250 per sq ft annually, competitive versus central malls AED 400+ per sqm, yielding 7-8% in the freehold zone. Additional incentives include monthly promotions, 30% loyalty program penetration, and a pipeline of 10 new tenants, supporting projected 8% retail growth in 2025. Risks involve economic sensitivities in mid-tier segments and seasonal fluctuations.
Building Details
Detailed Market Analytics
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Dubai
Discover more shopping centers in Dubai.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Dubai
Comprehensive market intelligence for retail expansion in this city