





Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
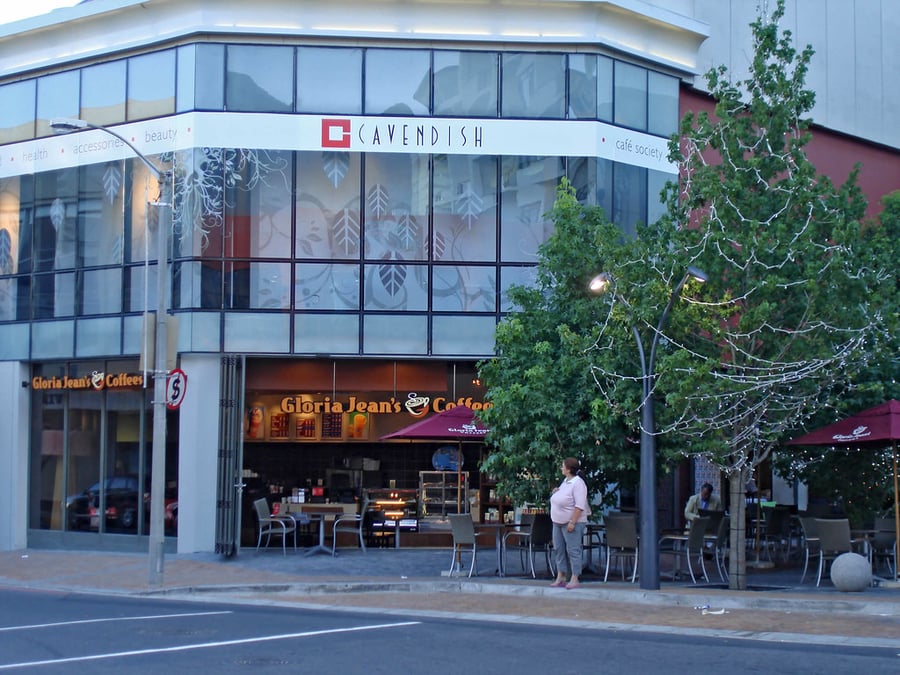
Cavendish Square is a regional shopping centre located in Claremont, within Cape Towns Southern Suburbs, spanning approximately 40,000 square metres of gross leasable area with over 200 stores. Opened in 1973 and owned by Old Mutual Properties, it positions itself as an upscale fashion and lifestyle destination targeting middle to upper-income consumers. The tenant mix emphasizes fashion and accessories, featuring anchors such as Woolworths, Edgars, Truworths, H&M, and Mr Price, alongside specialty stores for homeware, electronics, and beauty.
Dining options include 19 restaurants and a food court with chains like Spur, KFC, and ColCacchio, complemented by 16 cinemas (transitioning to Nu Metro in 2025 after Ster-Kinekor closure). Footfall averages 1.7 million visitors monthly, supported by strong local draw from affluent suburbs like Constantia and Rondebosch. Occupancy remains high at around 95 percent based on recent commercial reports, reflecting robust demand in a market with Cape Town retail vacancy rates below 5 percent in 2024.
Accessibility is favorable via major arterials like the M3 highway, with ample parking for 2,500 vehicles and proximity to MyCiTi bus services, though traffic congestion during peak hours poses challenges.
Rent levels range from R300 to R600 per square metre monthly for prime spaces, competitive for the segment but pressured by economic slowdowns affecting discretionary spending. Market factors include a demographic of professionals and families with household incomes over R500,000 annually, driving sales in apparel categories exceeding national averages by 15 percent per industry benchmarks. Advantages for lessees include established brand synergy and high dwell time of 90 minutes per visit, enhancing conversion rates.
Drawbacks encompass saturation in fashion retail, with nearby competitors like Blue Route Mall diluting traffic, and infrastructure updates needed for aging elements despite periodic refurbishments.
Overall, it offers stable performance in a resilient suburban market, though retailers must navigate South Africas 2.5 percent retail growth projection for 2025 amid inflation concerns.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 07:00 PM |
| Tuesday | 09:00 AM — 07:00 PM |
| Wednesday | 09:00 AM — 07:00 PM |
| Thursday | 09:00 AM — 07:00 PM |
| Friday | 09:00 AM — 07:00 PM |
| Saturday | 09:00 AM — 07:00 PM |
| Sunday | 09:00 AM — 05:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile
The primary catchment area encompasses affluent Southern Suburbs residents, with 60 percent of shoppers from households earning above R30,000 monthly, per 2023 market studies. This includes young professionals, families, and retirees from areas like Claremont and Newlands, favoring premium fashion and lifestyle goods. Gender skews 55 percent female, with strong weekend family traffic. However, economic pressures have shifted spending toward value-oriented categories, reducing impulse buys by 10 percent year-on-year, requiring adaptive merchandising to maintain relevance in this selective demographic.
Competitive Landscape
Cavendish Square faces competition from regional peers like Canal Walk (larger scale, 500 stores) and local venues such as Claremont Riverside, which offer similar upscale mixes but better entertainment anchors. V&A Waterfront draws tourist footfall, impacting seasonal sales by up to 20 percent during holidays. Strengths lie in suburban convenience, minimizing commute times under 20 minutes for 70 percent of visitors, versus city-centre rivals. Risks include market saturation in apparel, with 40 percent of space dedicated to fashion amid e-commerce growth capturing 15 percent of category sales nationally in 2024, necessitating differentiation through exclusive local brands.
Operational Quality and Lease Terms
Operational metrics highlight 95 percent occupancy and annual turnover of R2.5 billion, per property reports, with footfall conversion rates at 25 percent above suburban averages due to quality tenant curation and 24-hour security. Lease terms typically span 5 years with escalations of 8 percent annually, including turnover rents for high performers, but include strict category restrictions to preserve mix balance. Challenges involve maintenance costs from 50-year-old infrastructure, with recent R100 million refurbishment addressing HVAC and facades. Accessibility aids performance, yet public transport limitations expose reliance on private vehicles, vulnerable to fuel price hikes influencing 30 percent of traffic patterns.
Building Details
Detailed Market Analytics
City Snapshot
Cape Town
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Cape Town
Discover more shopping centers in Cape Town.





Popular in South Africa
Top retail destinations across South Africa.




Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Cape Town
Comprehensive market intelligence for retail expansion in this city