



Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
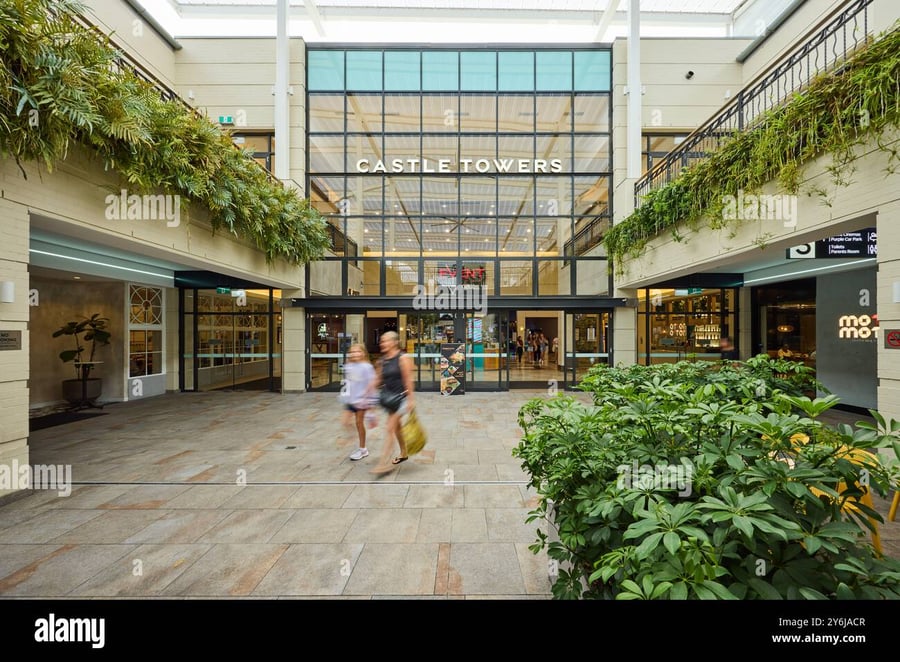
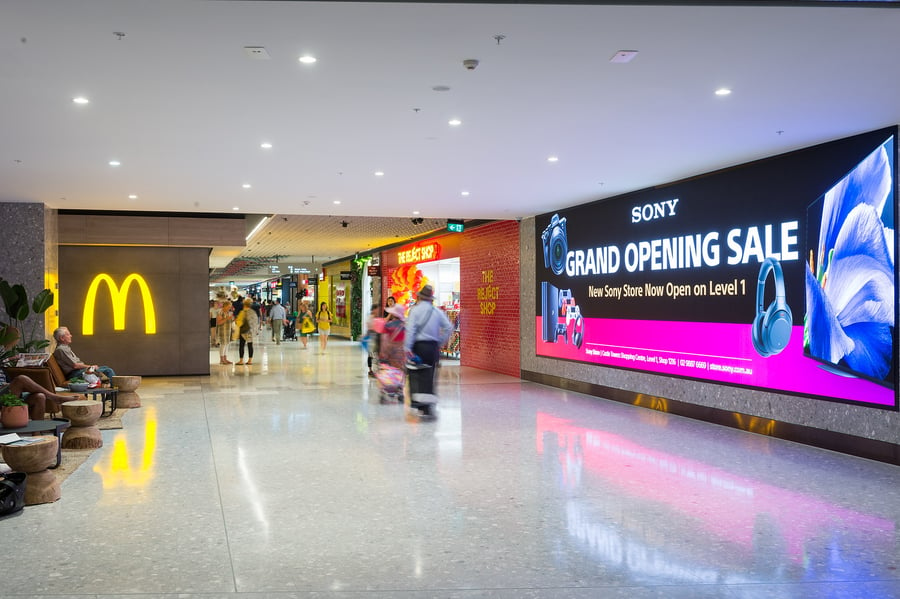
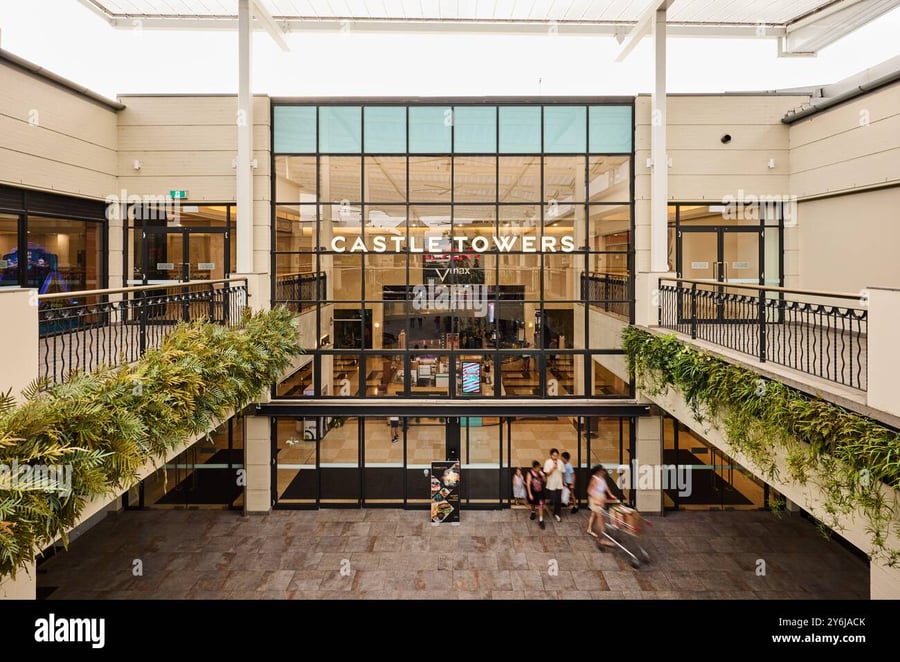
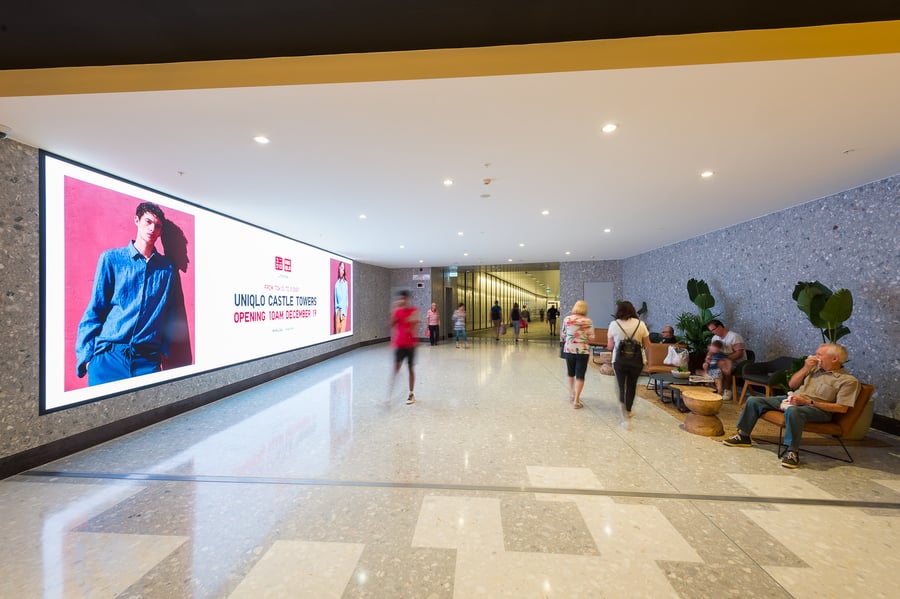
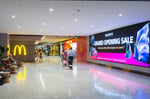
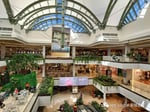
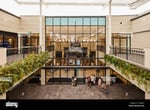
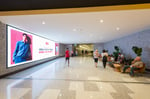
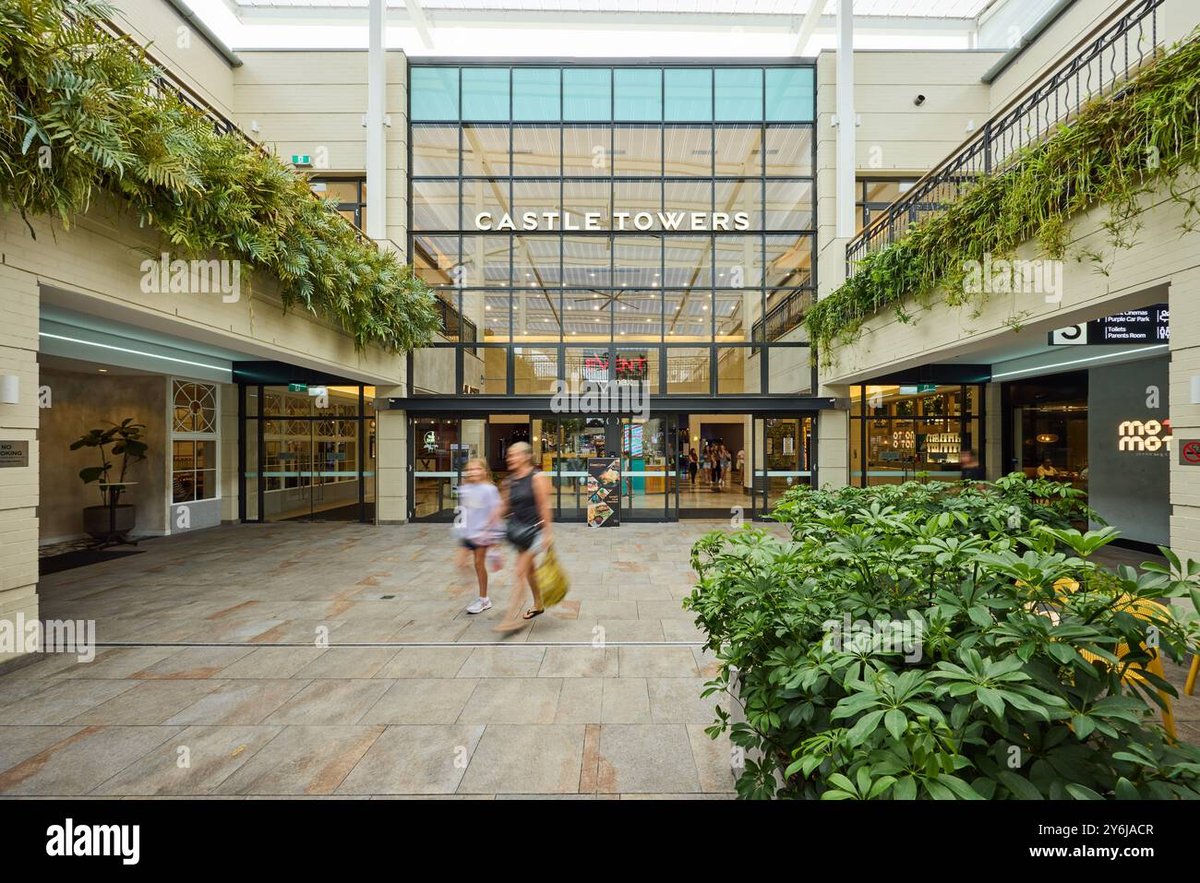
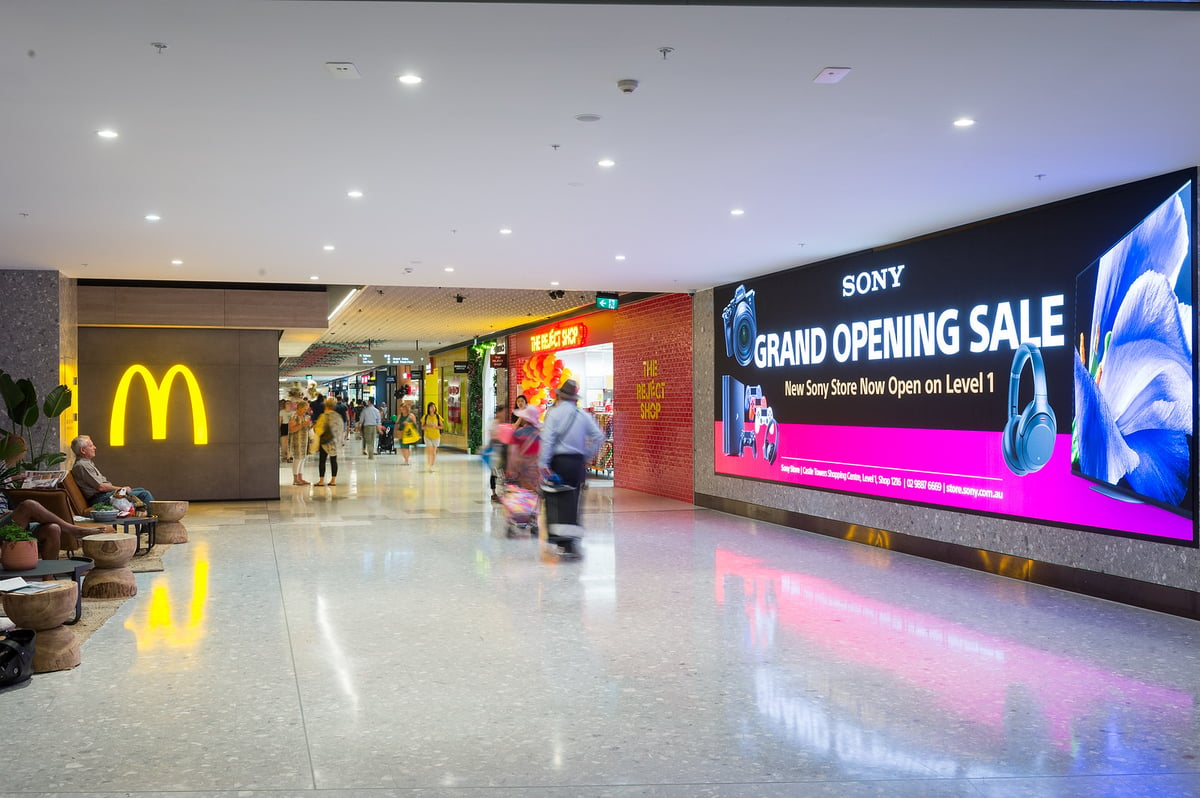
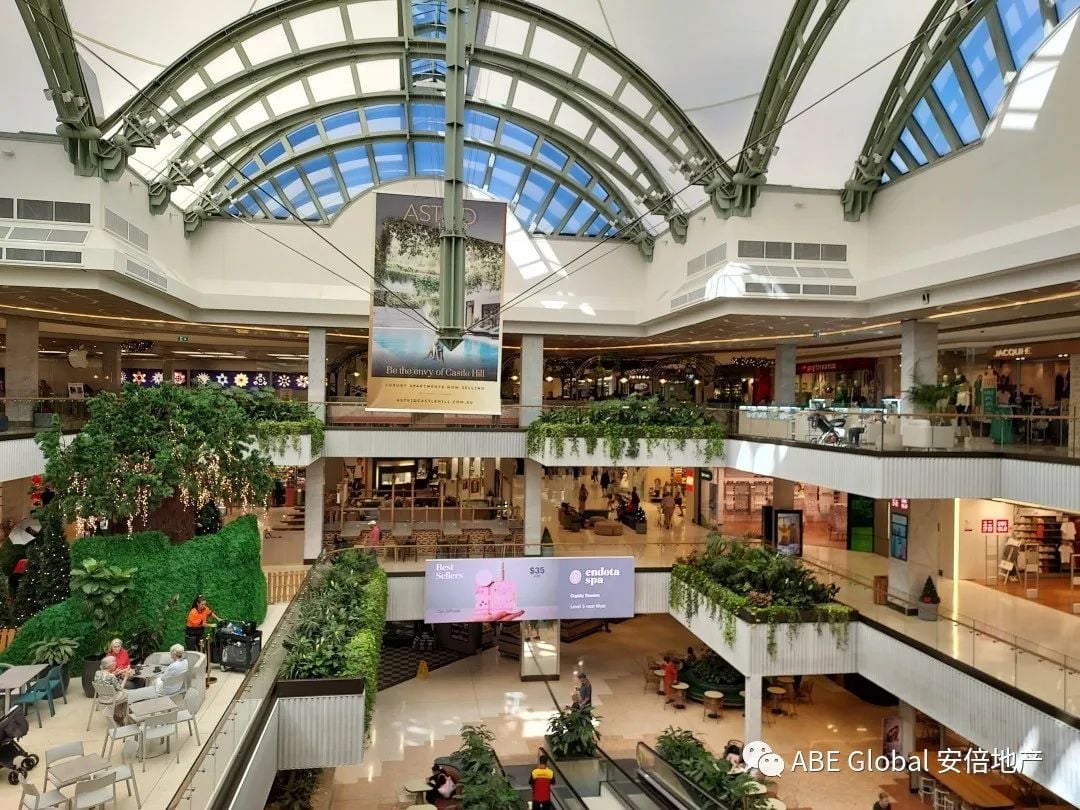
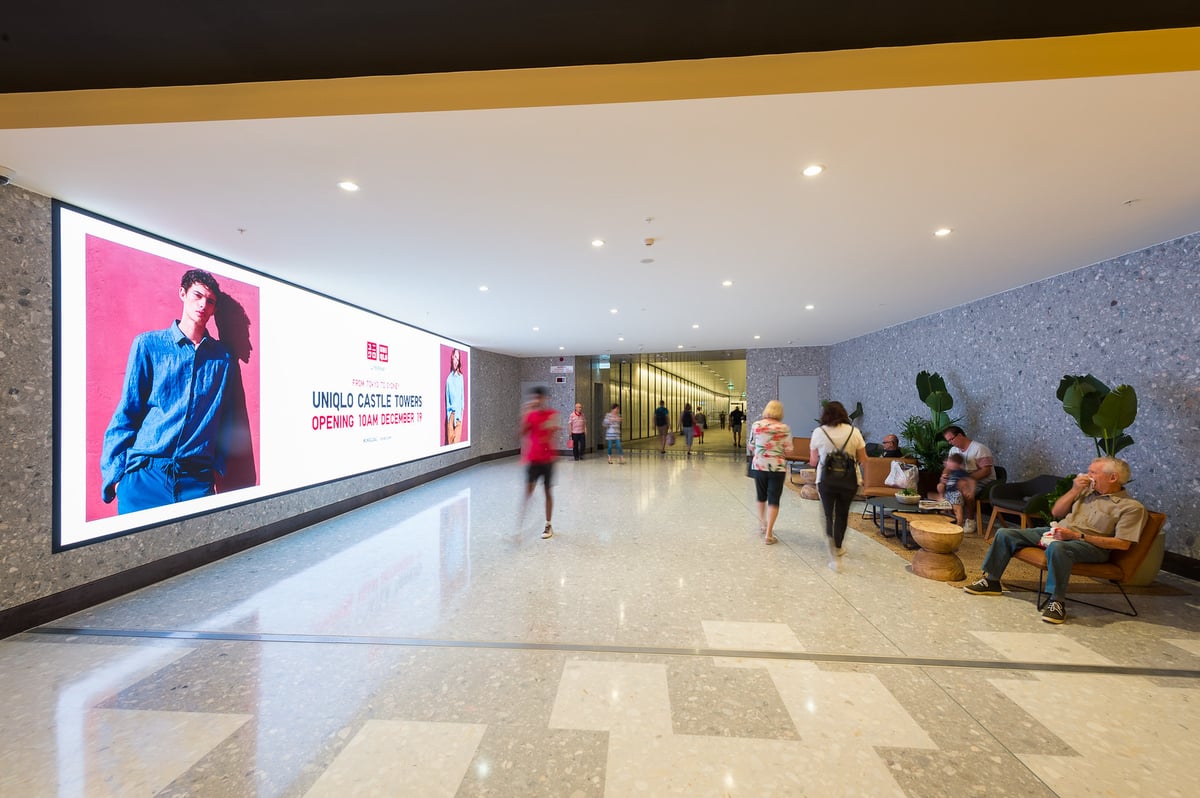
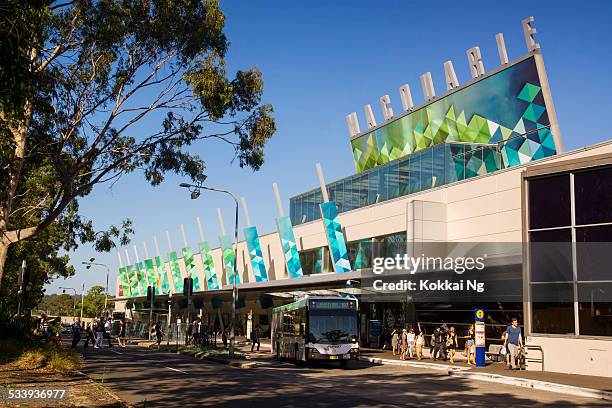
Castle Towers is a major regional shopping centre located in Castle Hill, approximately 30 km northwest of Sydney CBD, serving the affluent and rapidly growing Hills district. Owned by Queensland Investment Corporation, it spans a net leasable area of approximately 112,000 square metres across three levels with 220 specialty stores. Key anchors include Myer, David Jones, Target, Kmart, Coles supermarket, Event Cinemas, and Dan Murphy's liquor store.
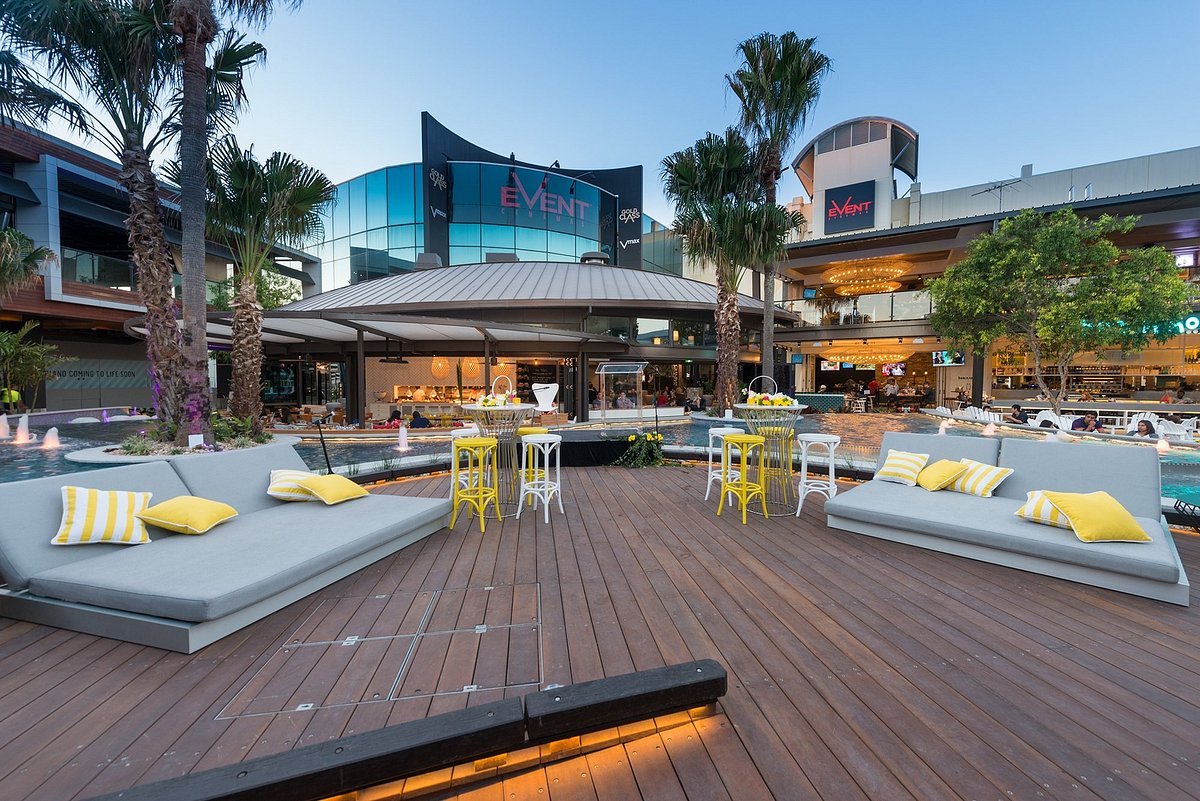
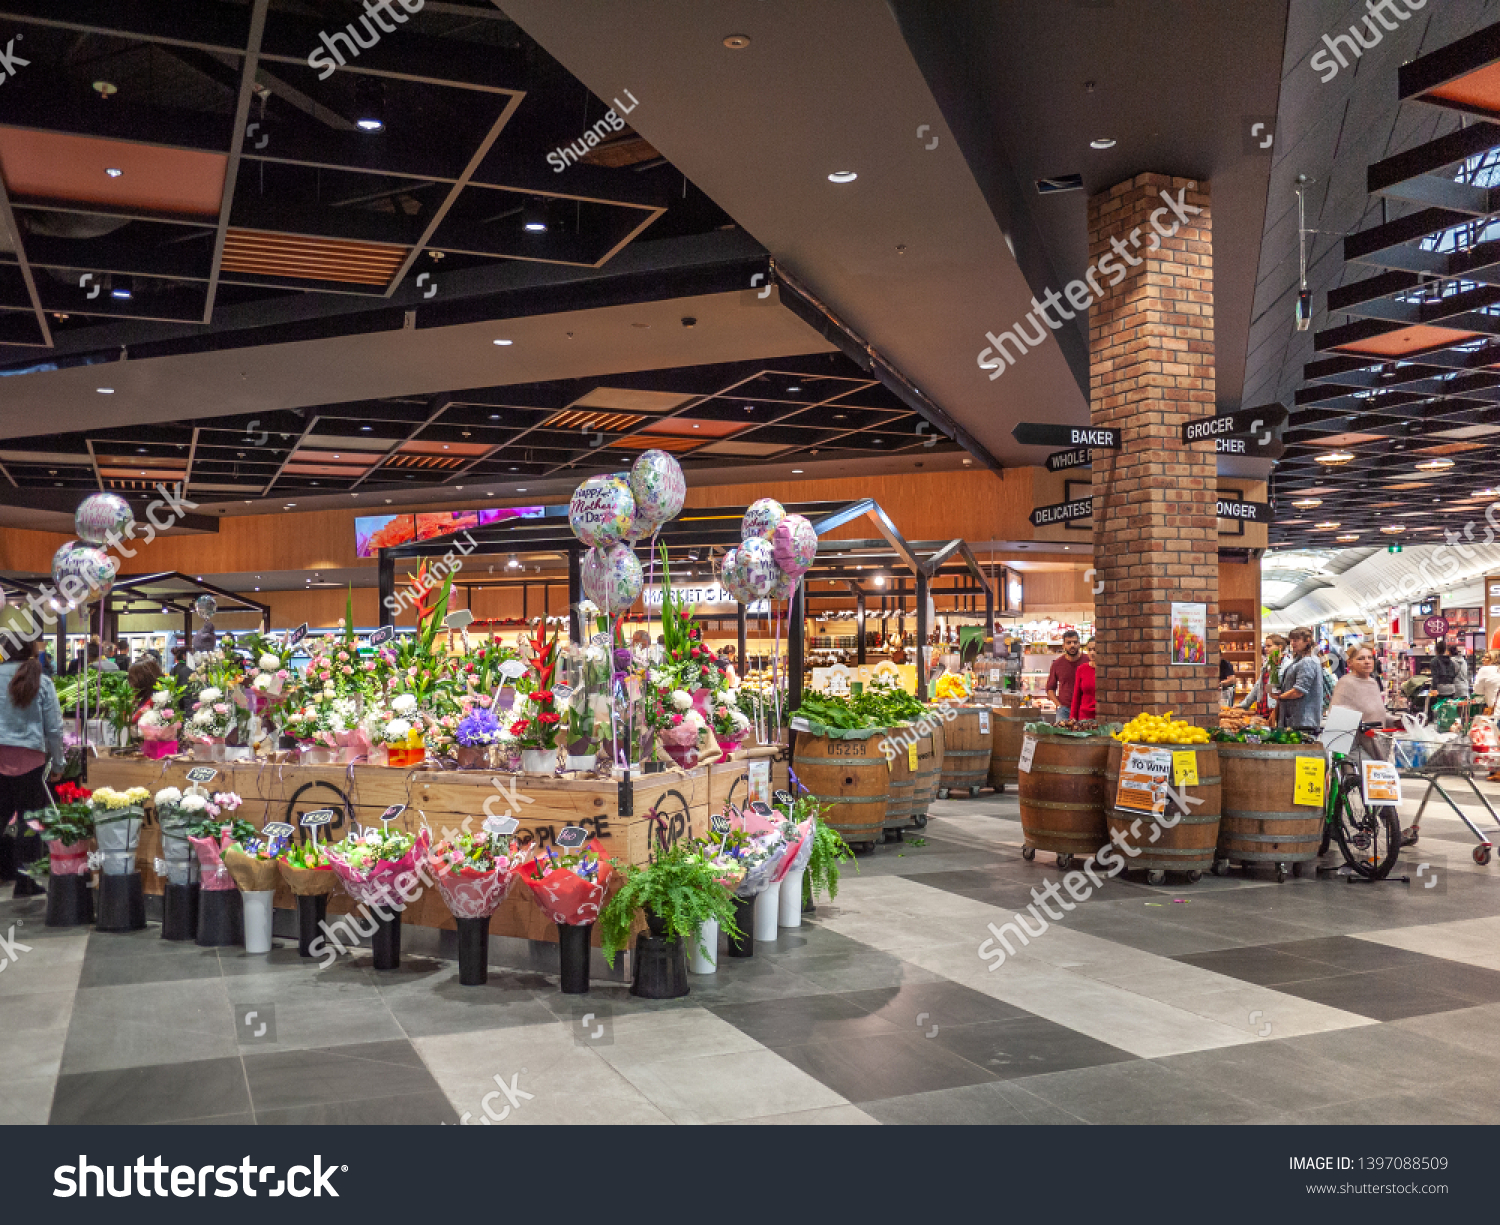
The tenant mix features a strong emphasis on fashion and apparel from international brands, beauty and homewares outlets, a fresh food marketplace with top Sydney providores, and a vibrant alfresco dining precinct known as The Piazza. Entertainment options include a premium cinema complex. The centre attracts 18.7 million annual visitors, benefiting from exceptional accessibility via an on-site Northwest Metro line station with direct pedestrian tunnel link (opened 2019), bus interchange, and 5,387 parking spaces, plus strong road connections to the city and Blue Mountains.
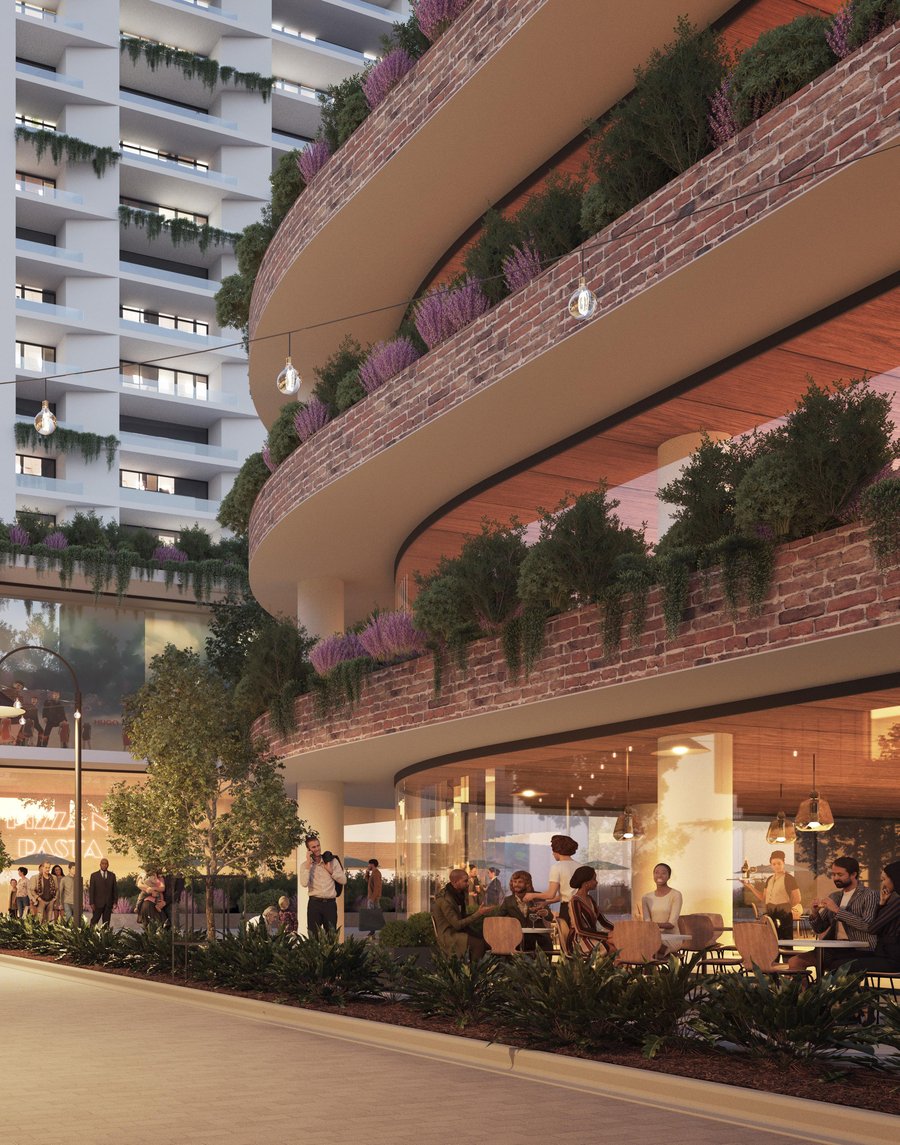
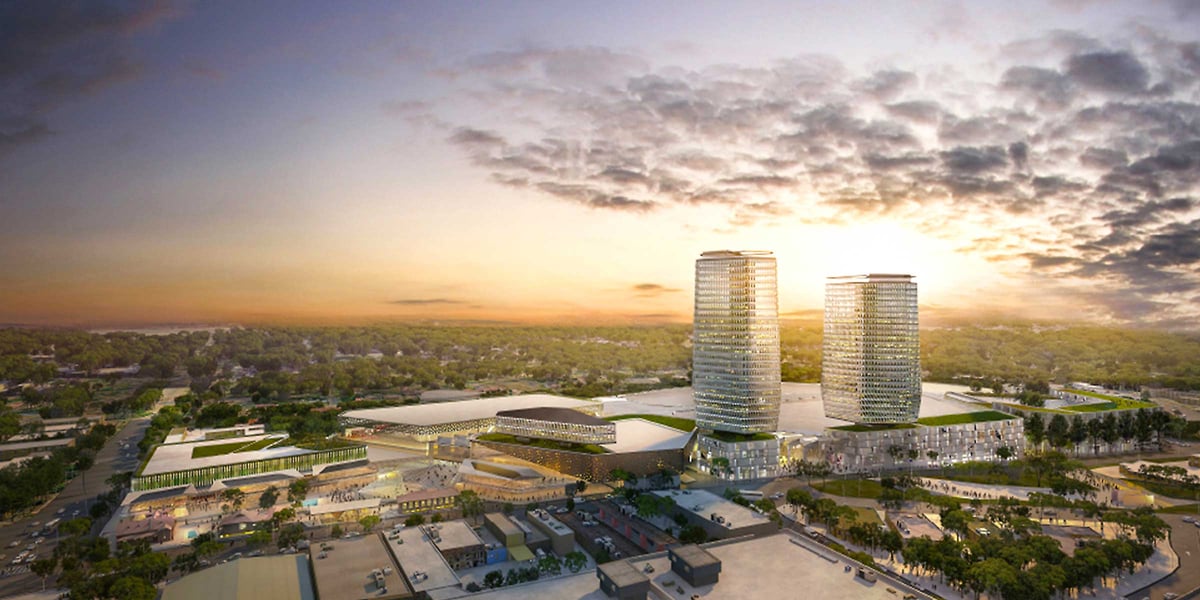
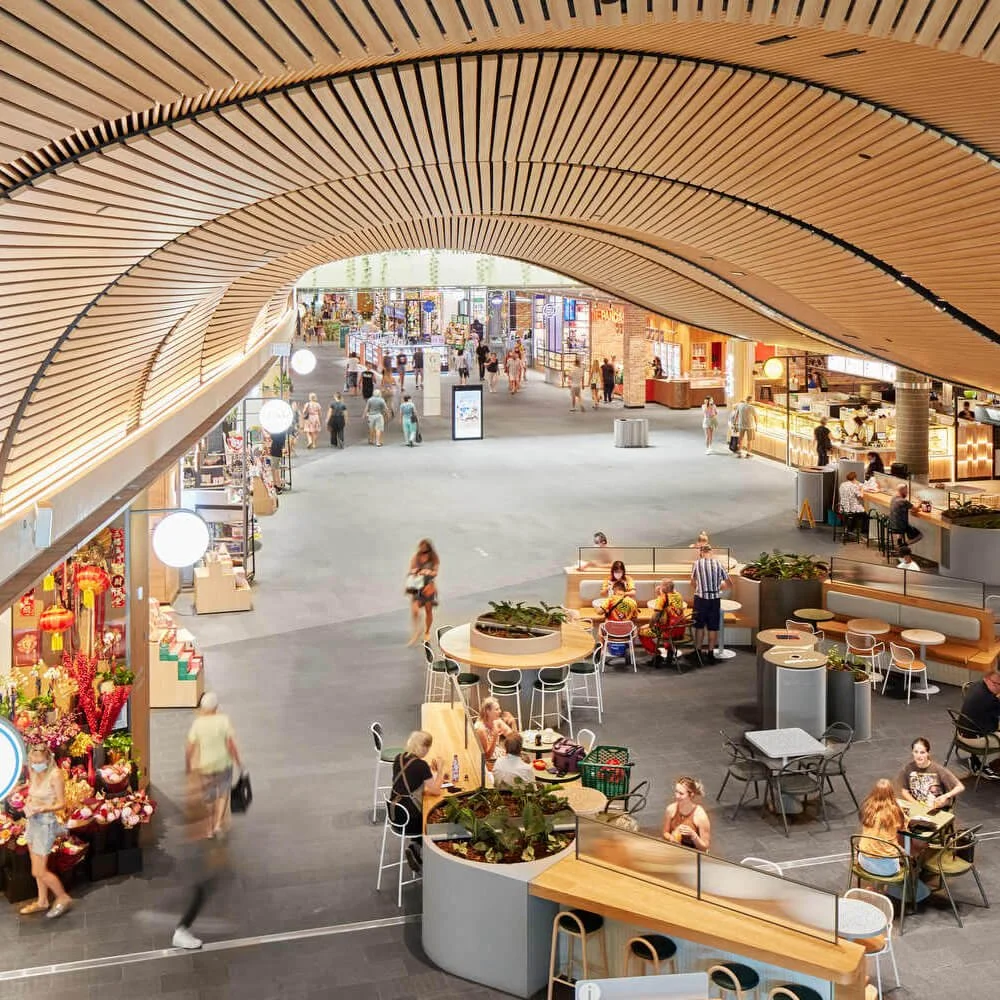
Market position as one of Australia busiest centres is bolstered by ongoing expansions, including a 2019 180 million dollar level 1 addition with new food court and retailers, and future plans for a 900 million dollar upgrade to become New South Wales largest mall by 2030, incorporating hotel, office, and residential elements.
Leasing advantages include high footfall driving sales potential in a demographic of affluent families with median household incomes above national average, supported by urban regeneration in the area. However, challenges involve competition from nearby power centres like Rouse Hill Town Centre and Norwest Business Park retail, potential market saturation in fashion categories, and impacts from e-commerce growth on physical retail.
Operational quality is high with recent refurbishments, though pre-2019 infrastructure in some areas shows signs of aging. Occupancy remains robust at around 95 percent based on regional benchmarks, with specialty rents typically ranging from 600 to 900 dollars per square metre annually in comparable Sydney suburban malls.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 05:30 PM |
| Tuesday | 09:00 AM — 05:30 PM |
| Wednesday | 09:00 AM — 05:30 PM |
| Thursday | 09:00 AM — 09:00 PM |
| Friday | 09:00 AM — 05:30 PM |
| Saturday | 09:00 AM — 05:00 PM |
| Sunday | 10:00 AM — 05:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment Area
The primary catchment encompasses the Hills district, characterized by affluent households with median incomes exceeding 120,000 dollars annually, well above the Sydney average of 95,000 dollars. Population growth is driven by new residential developments and metro connectivity, projecting a 20 percent increase in the 25 to 44 age group by 2030, favoring family-oriented retail. Footfall of 18.7 million visitors annually reflects strong local draw, with 70 percent from within a 10 km radius, supporting consistent performance in lifestyle and convenience categories. Risks include shifting preferences toward mixed-use precincts integrating residential and office spaces.
Competition and Market Risks
Castle Towers faces competition from regional rivals such as Rouse Hill Town Centre (GLA 122,000 square metres) and The Hills at Castle Hill, both offering similar anchor mixes and drawing from overlapping affluent suburbs. Norwest Business Park retail adds weekday office worker traffic, potentially diluting weekend family visits. Broader risks encompass e-commerce penetration, which has reduced physical store sales by 5 to 10 percent annually in Australian retail reports, and economic sensitivity in discretionary spending categories like fashion, where saturation is evident with over 50 apparel outlets. Infrastructure upgrades mitigate access issues, but traffic congestion on surrounding roads remains a concern during peak hours.
Lease Terms and Operational Quality
Leasing terms feature base rents of 600 to 900 dollars per square metre for specialty spaces, with turnover rents at 8 to 12 percent of sales above thresholds, and incentives like rent-free periods of 3 to 6 months for new tenants. Occupancy hovers near 95 percent, supported by proactive asset management including recent 20 million dollar parking upgrades and digital enhancements. Operational strengths include integrated transit reducing reliance on car access, diverse tenant mix balancing anchors (40 percent of GLA) with specialties, and high cleanliness scores in industry audits. Drawbacks involve higher utility costs in older sections pre-refurbishment and seasonal footfall dips outside holiday periods, necessitating flexible lease clauses for category adjustments.
Building Details
Detailed Market Analytics
City Snapshot
Castle Hill, NSW
Comprehensive market intelligence for retail expansion in this city

Popular in Australia
Top retail destinations across Australia.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Castle Hill, NSW
Comprehensive market intelligence for retail expansion in this city