Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
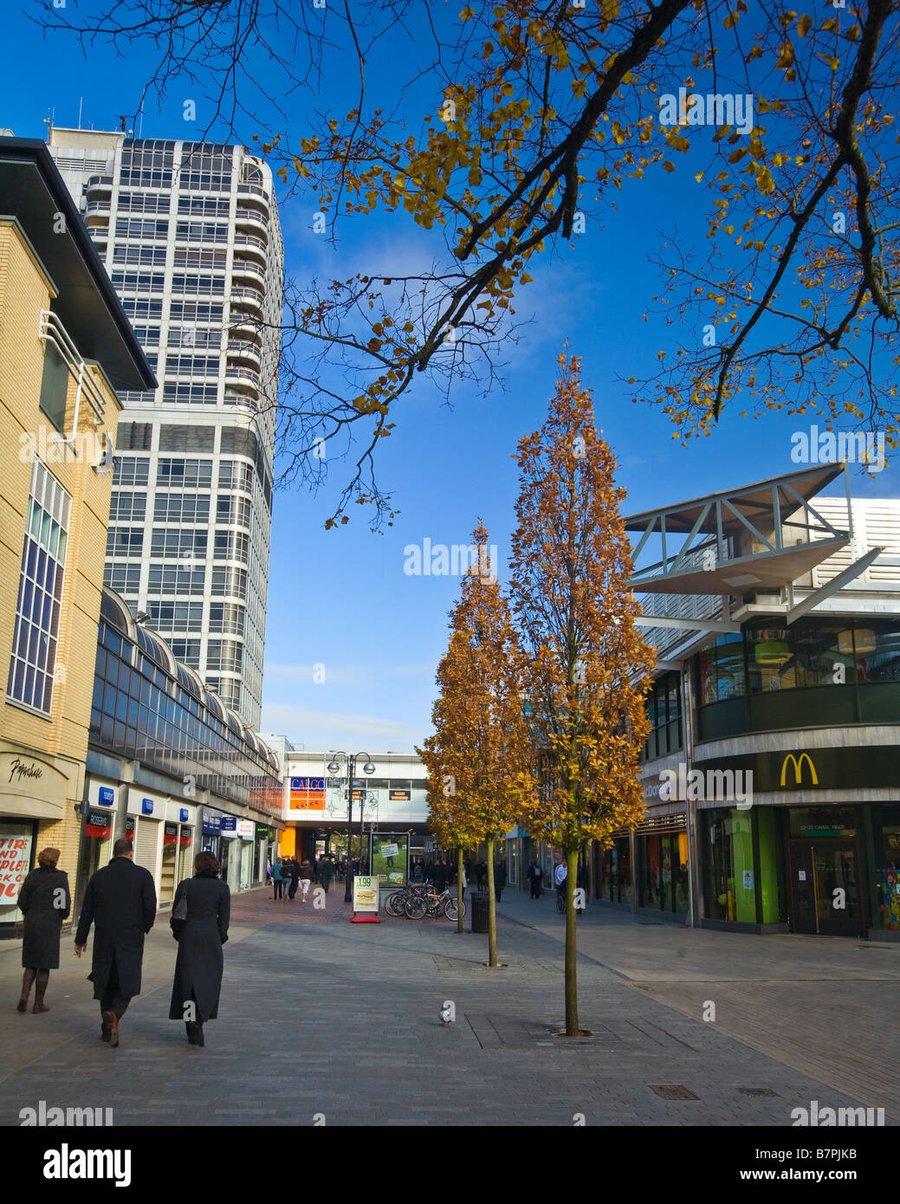
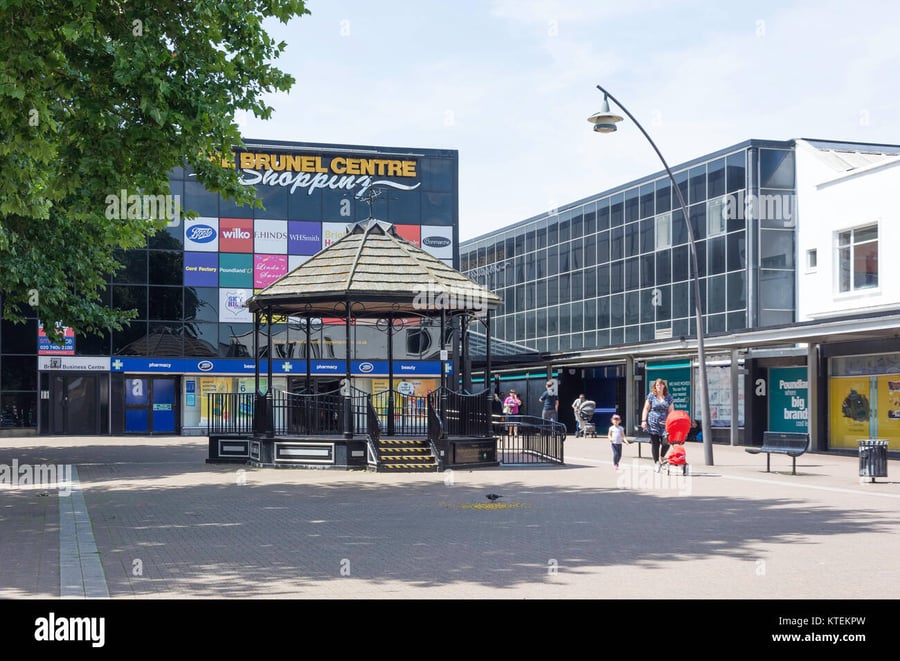
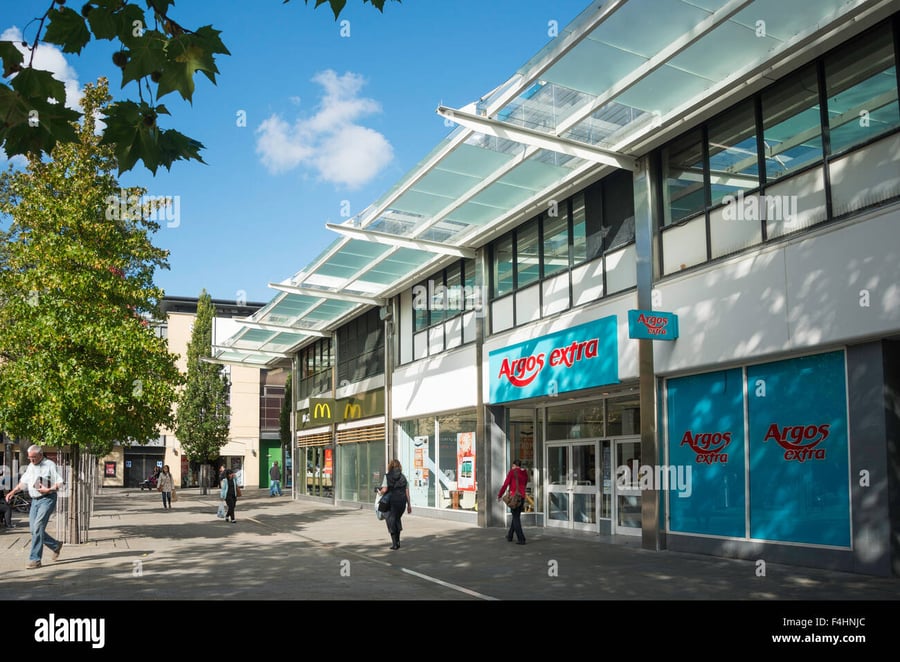
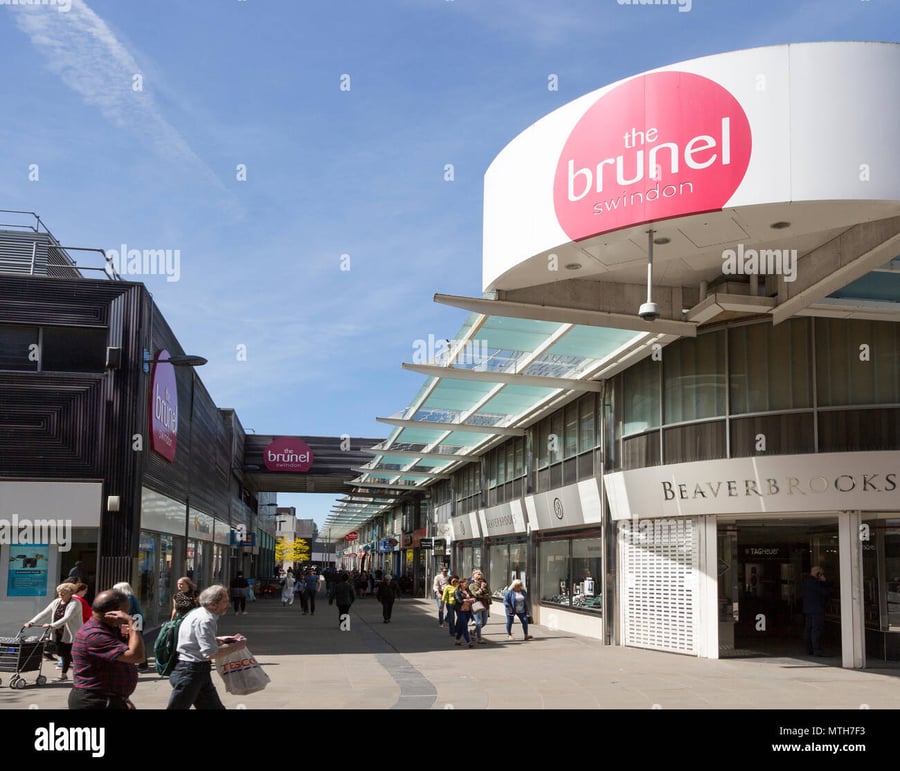
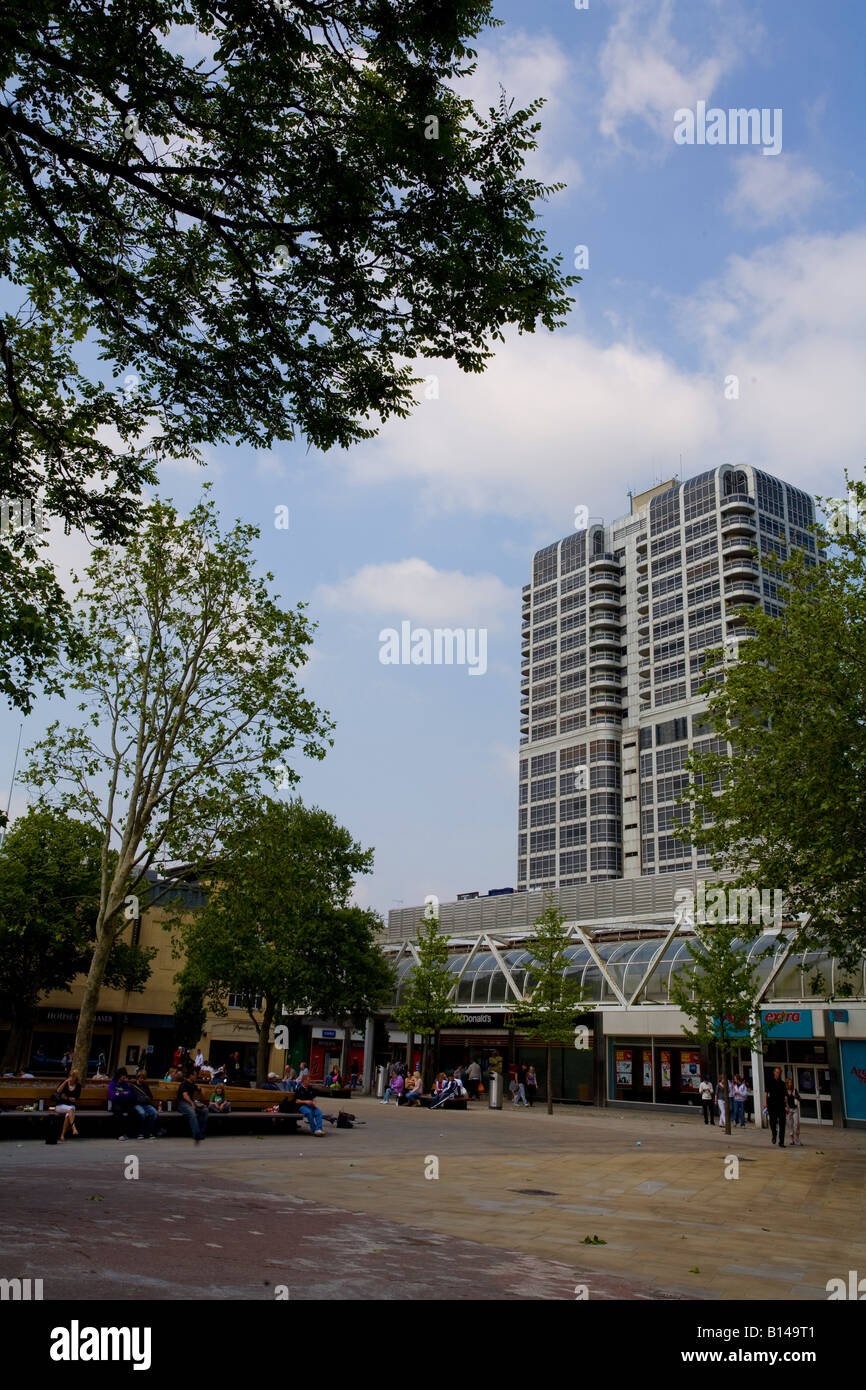
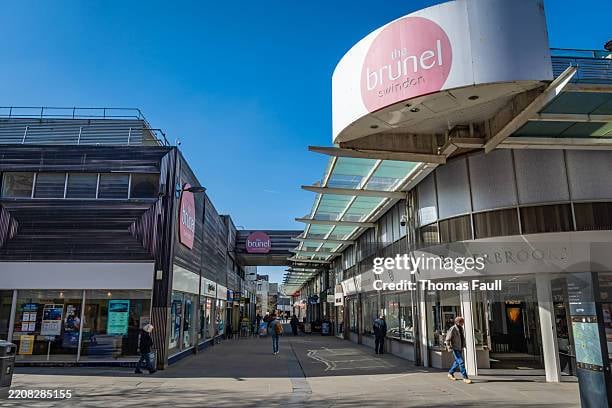
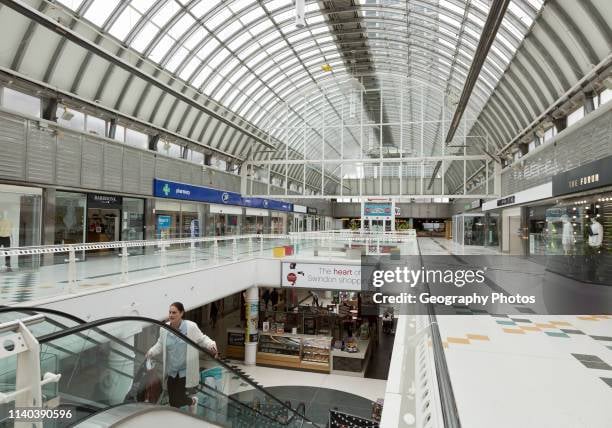
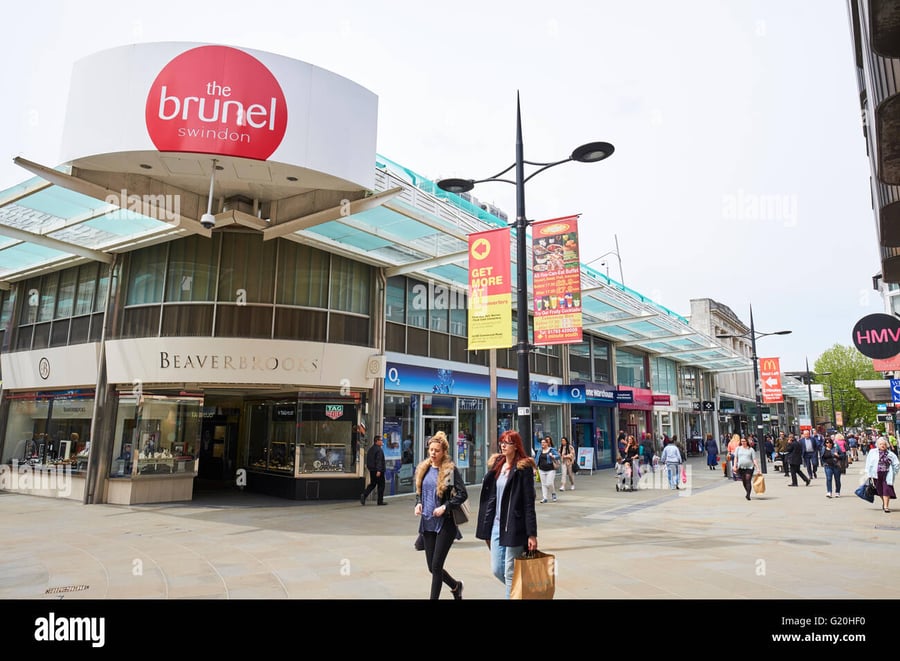
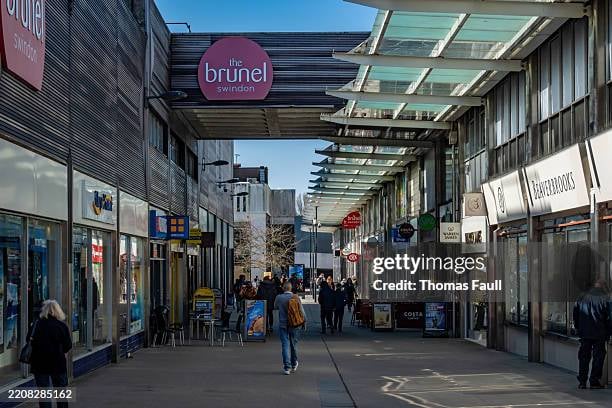
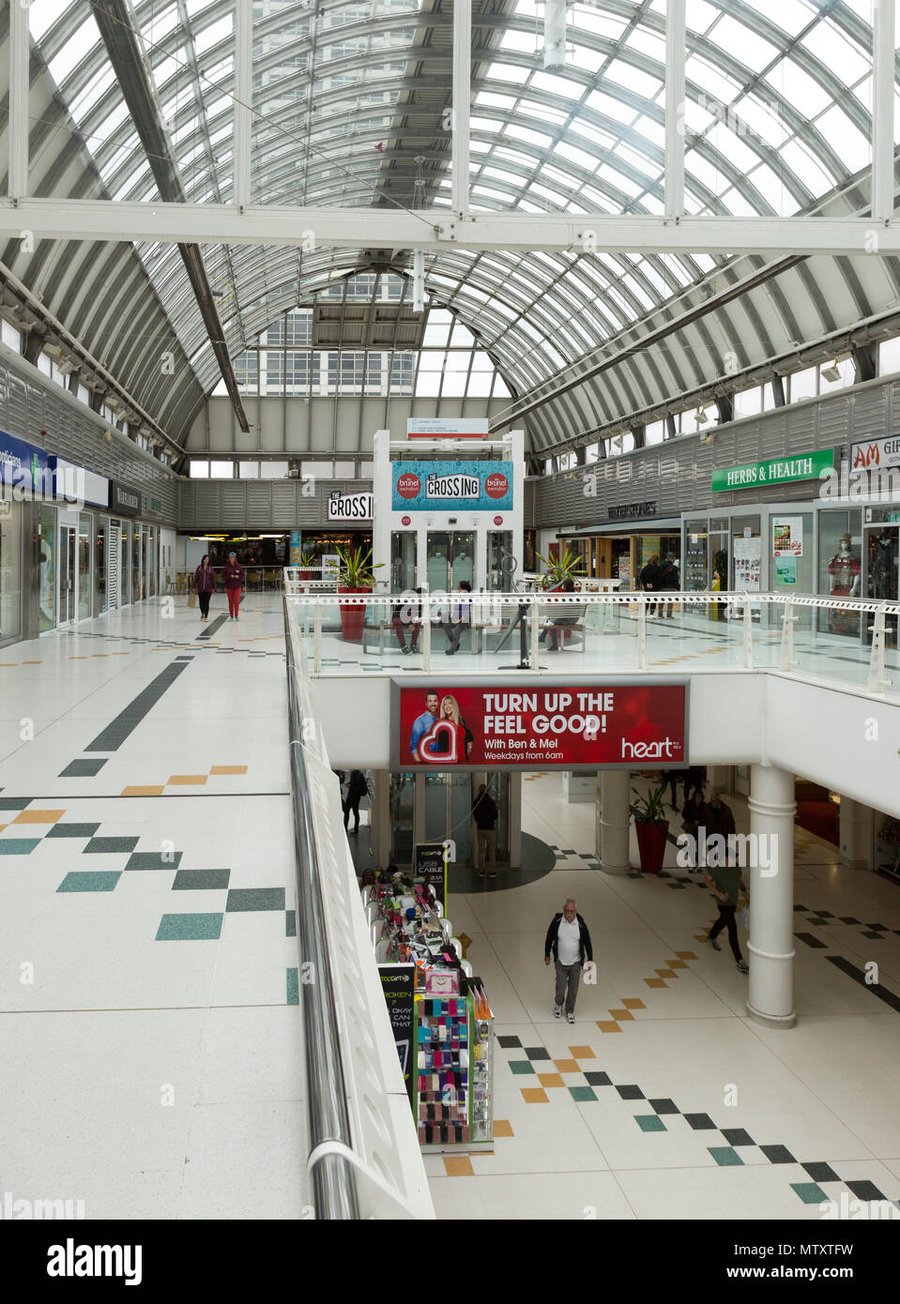
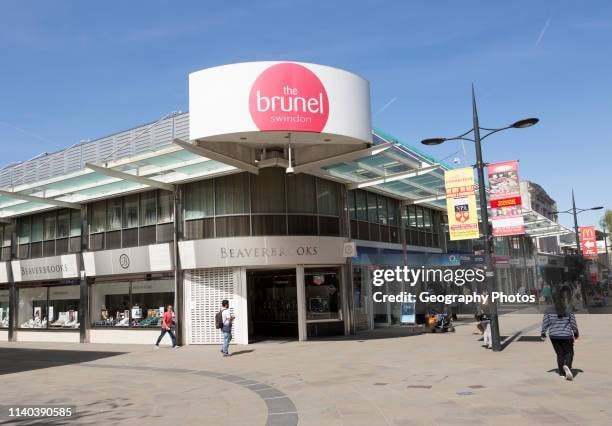
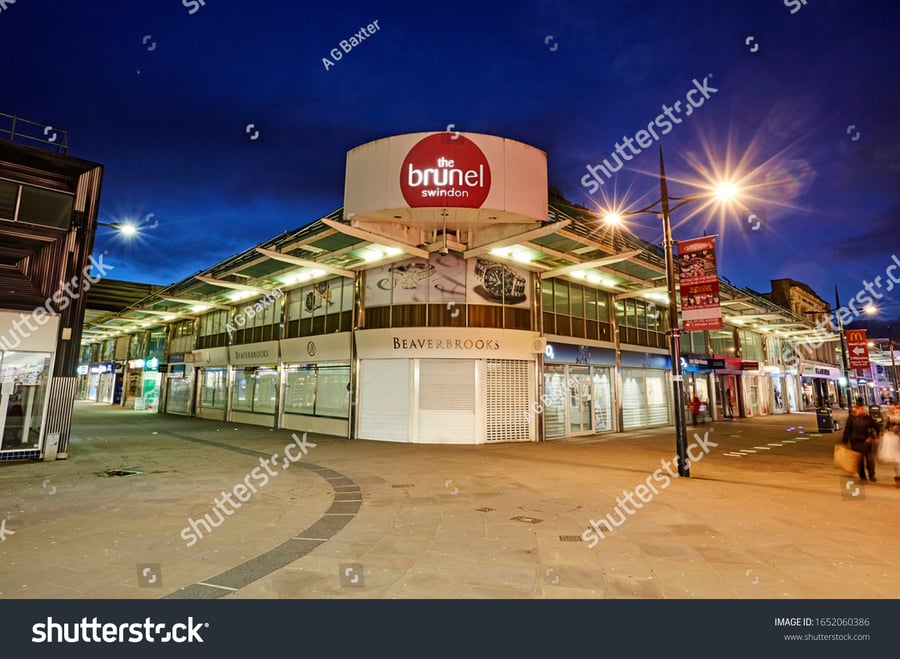
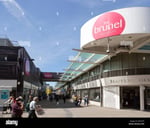
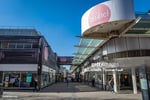
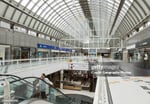
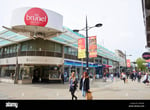
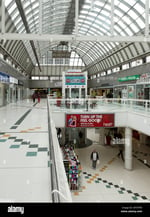
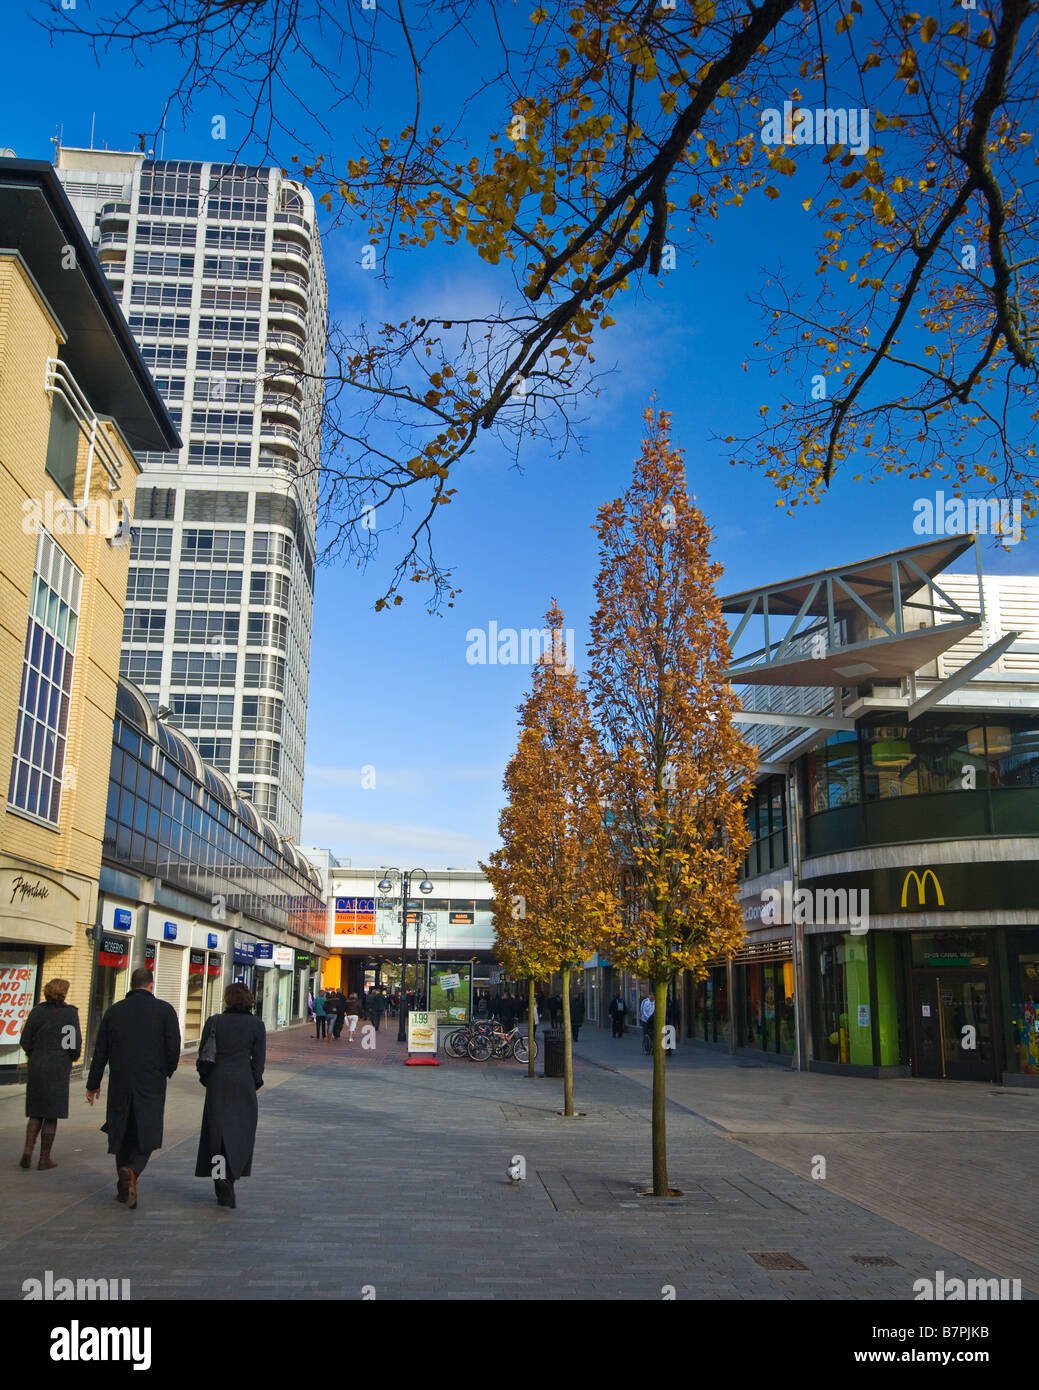
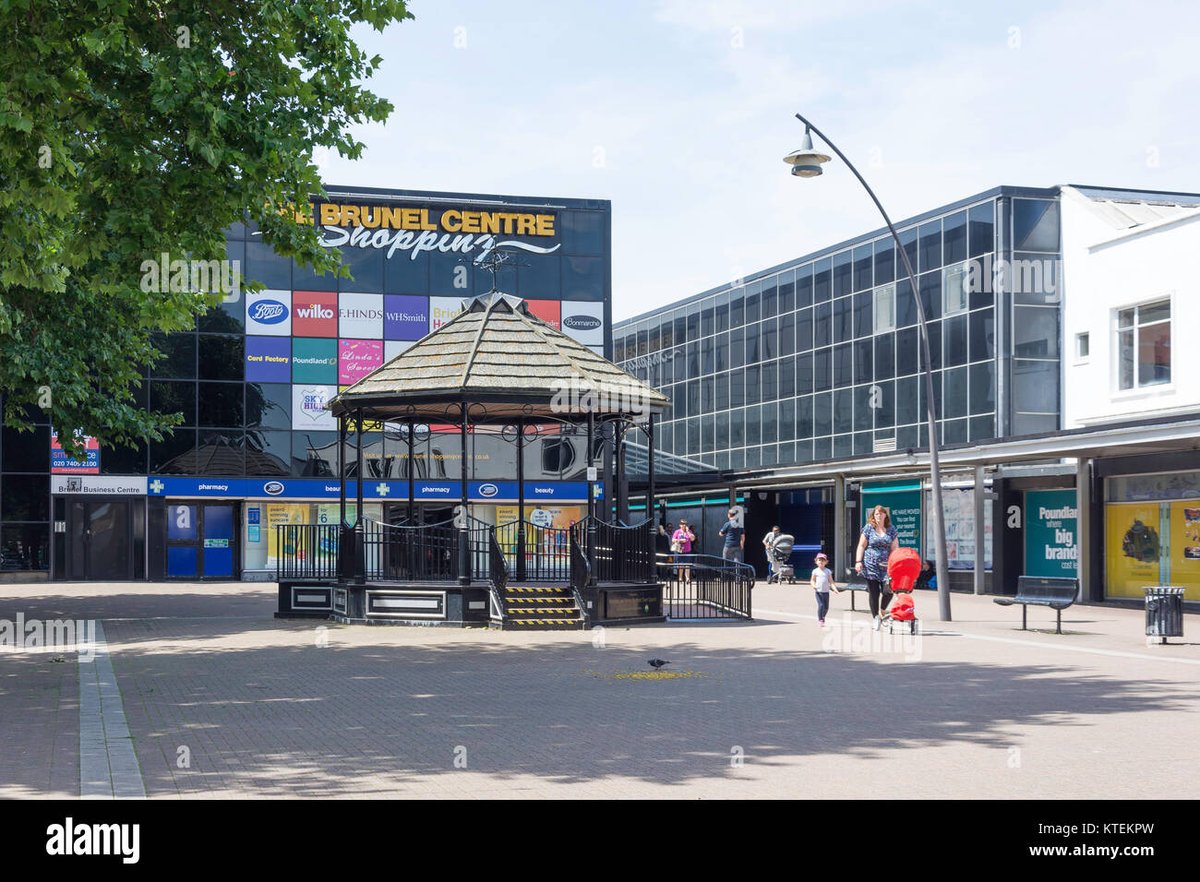
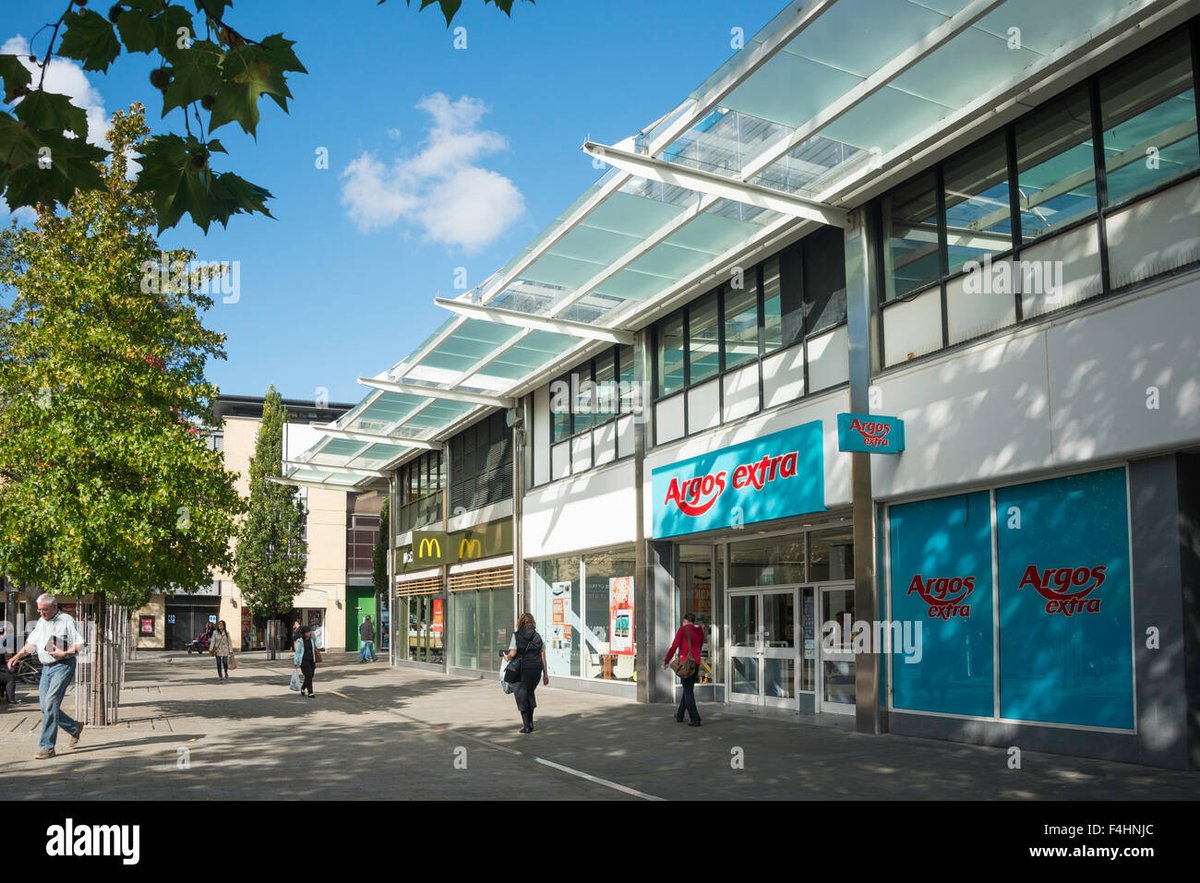
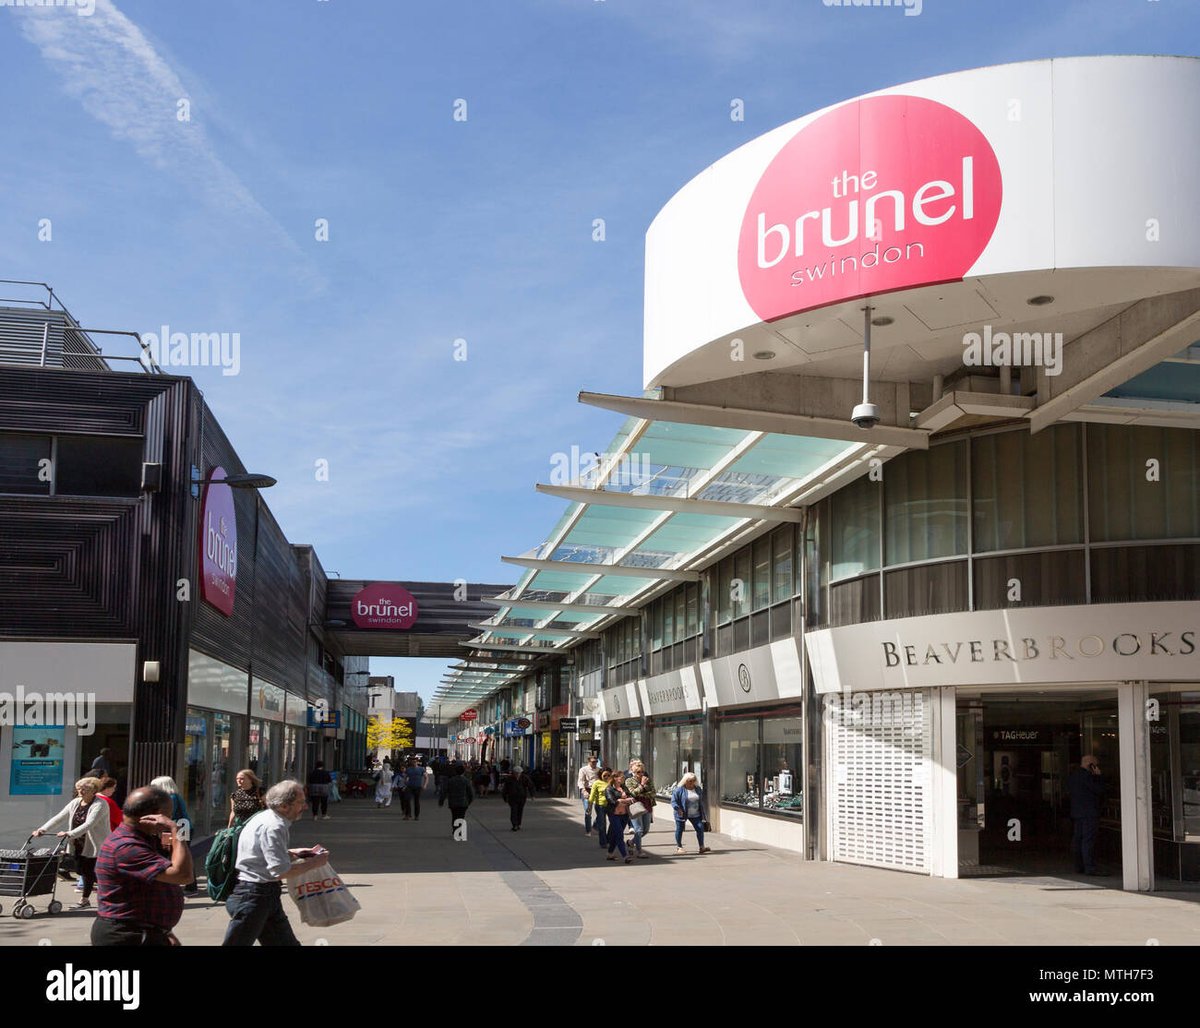
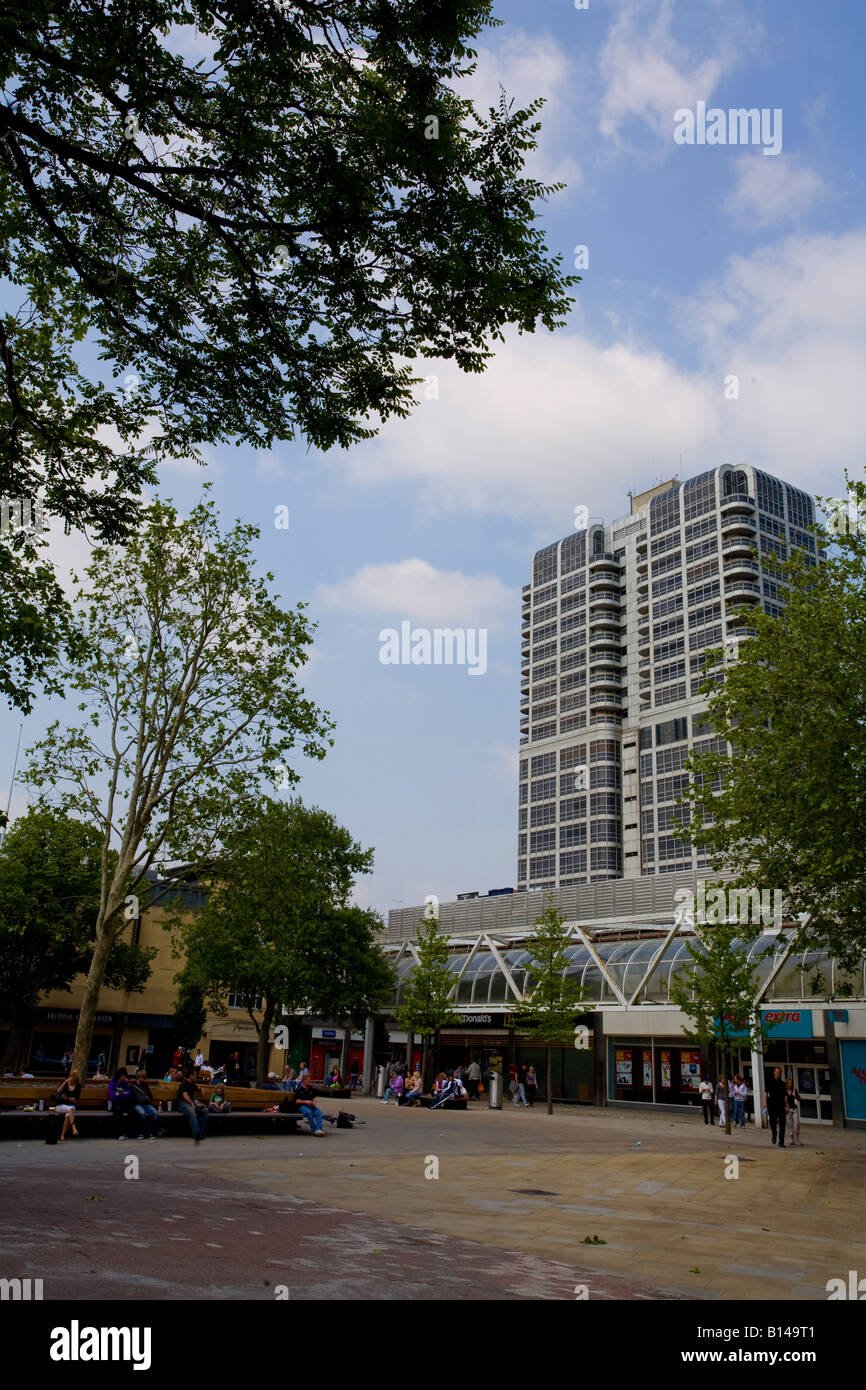
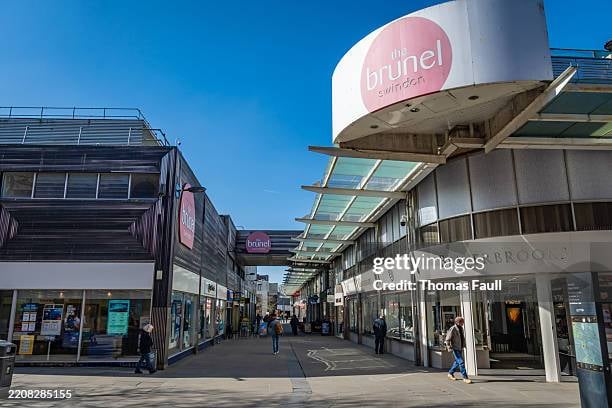
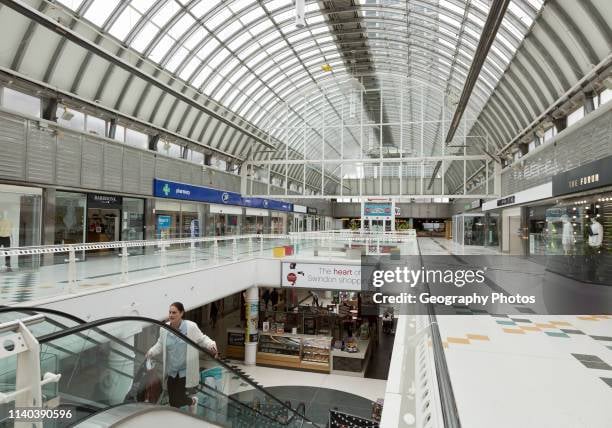
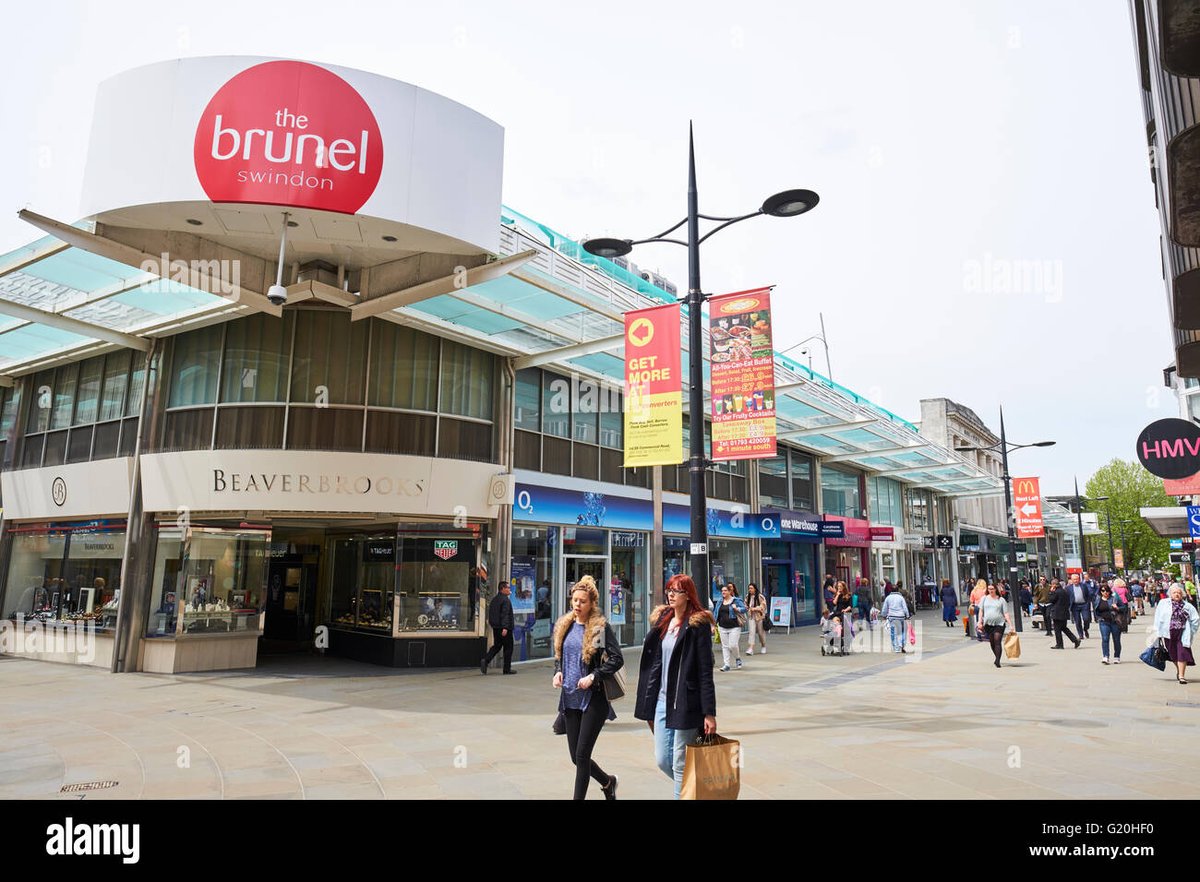
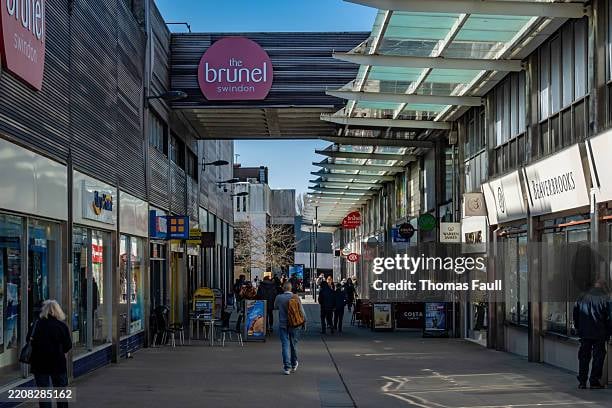
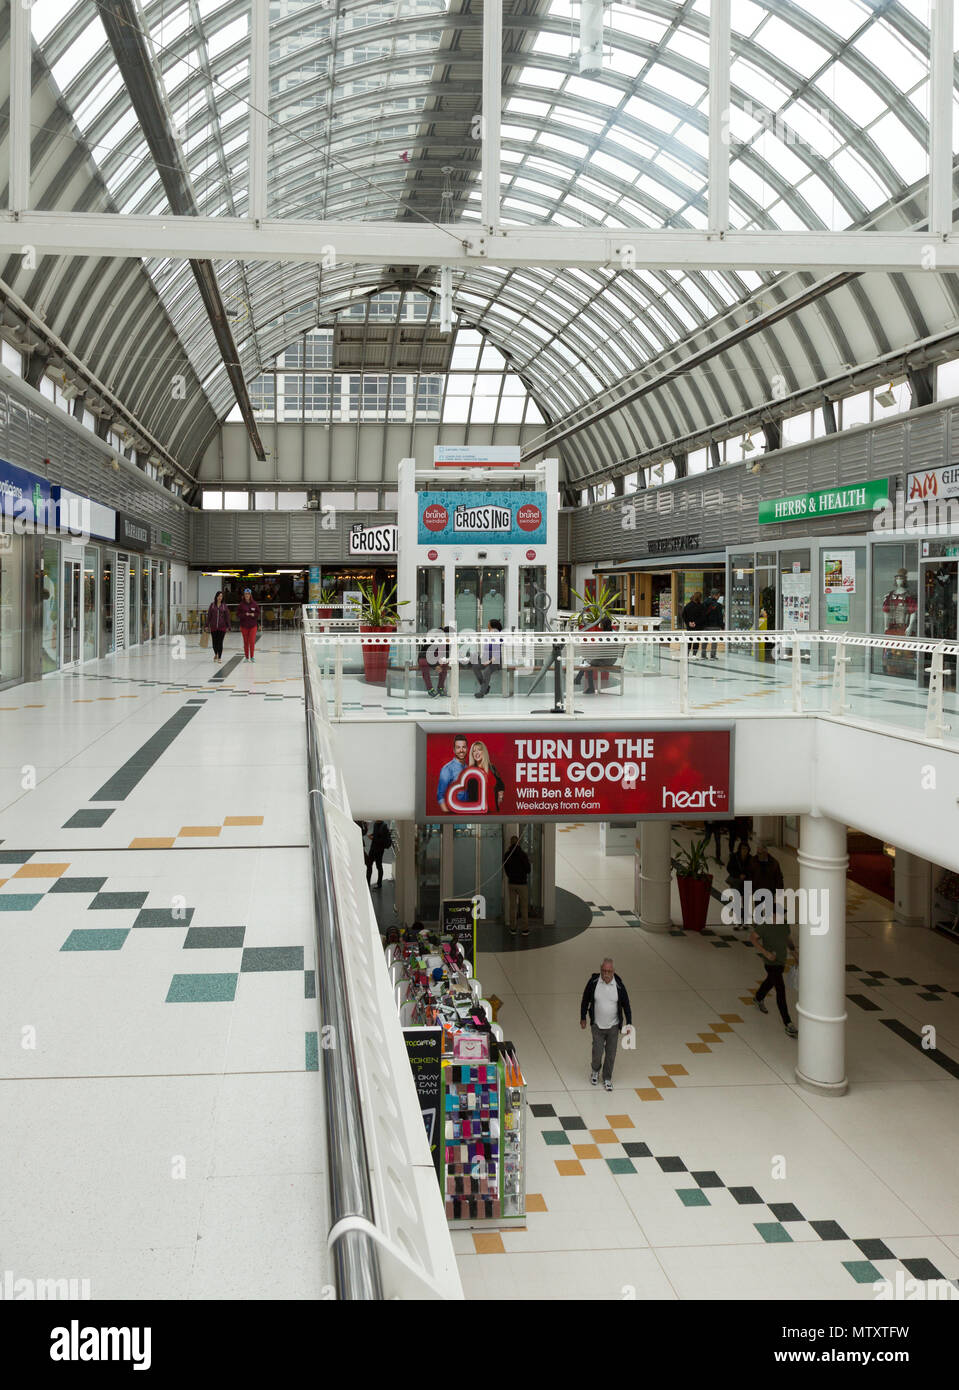
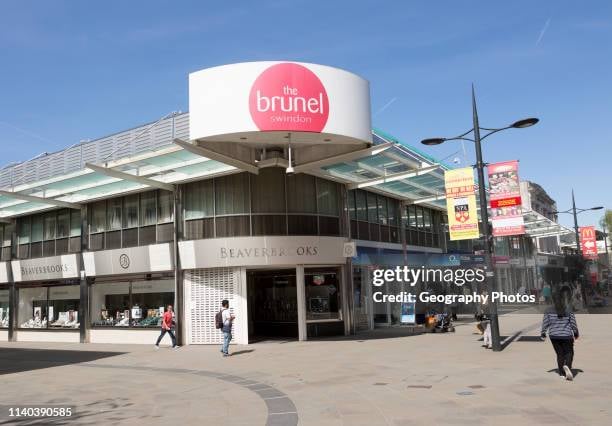
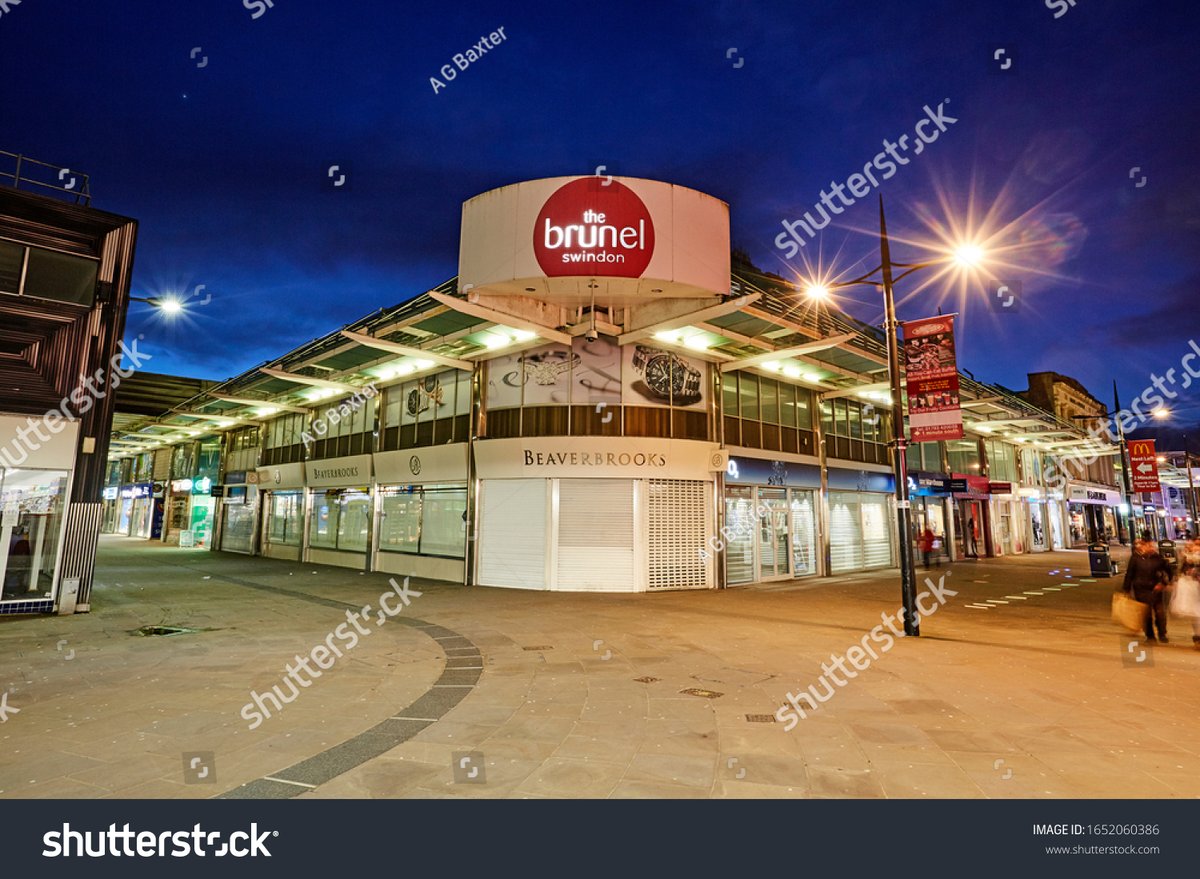
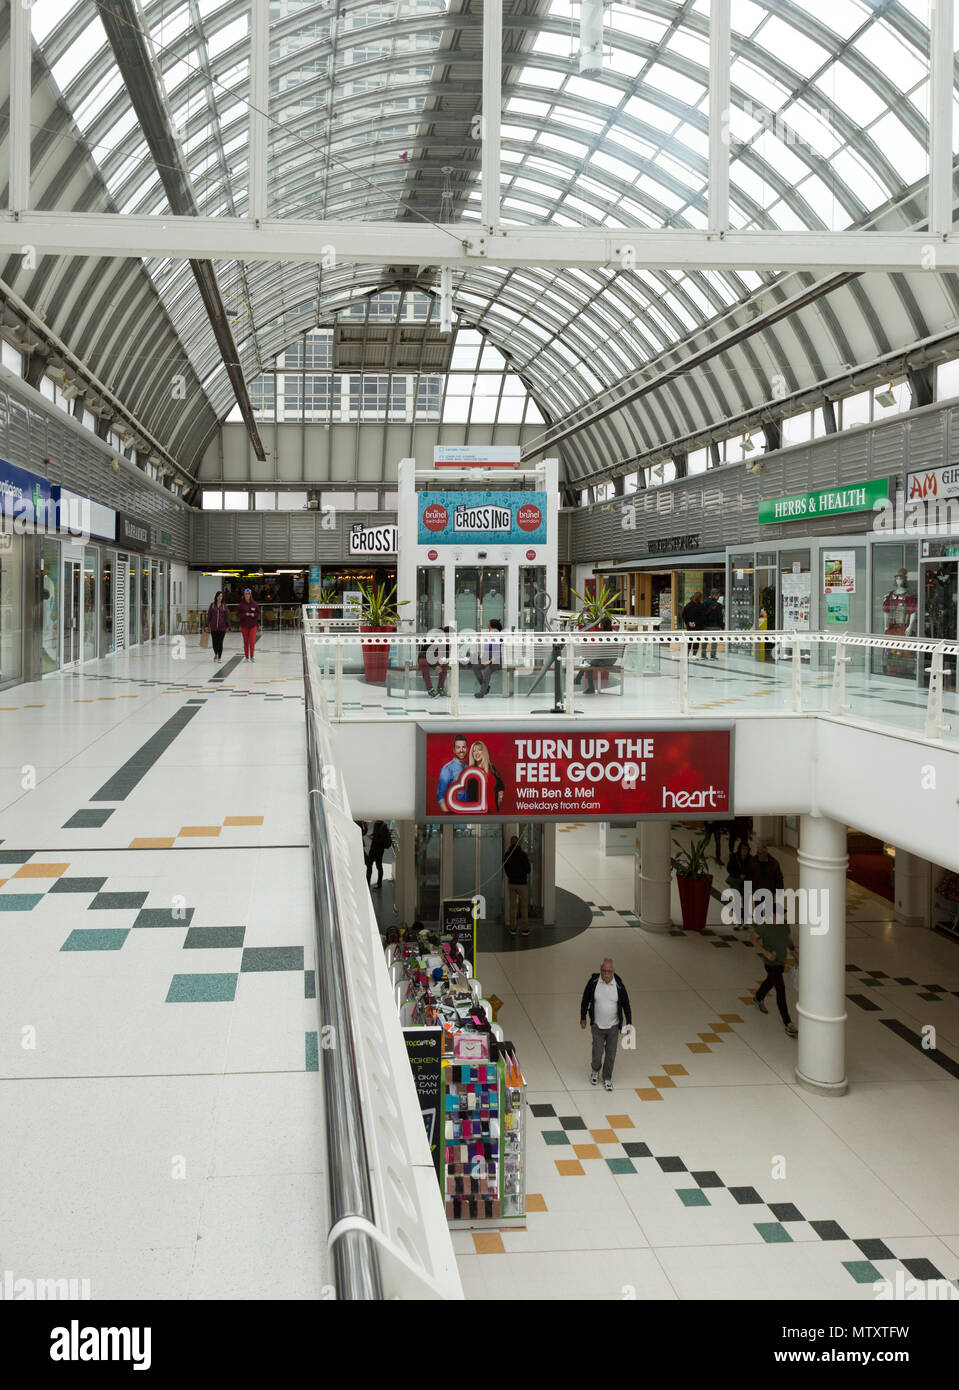
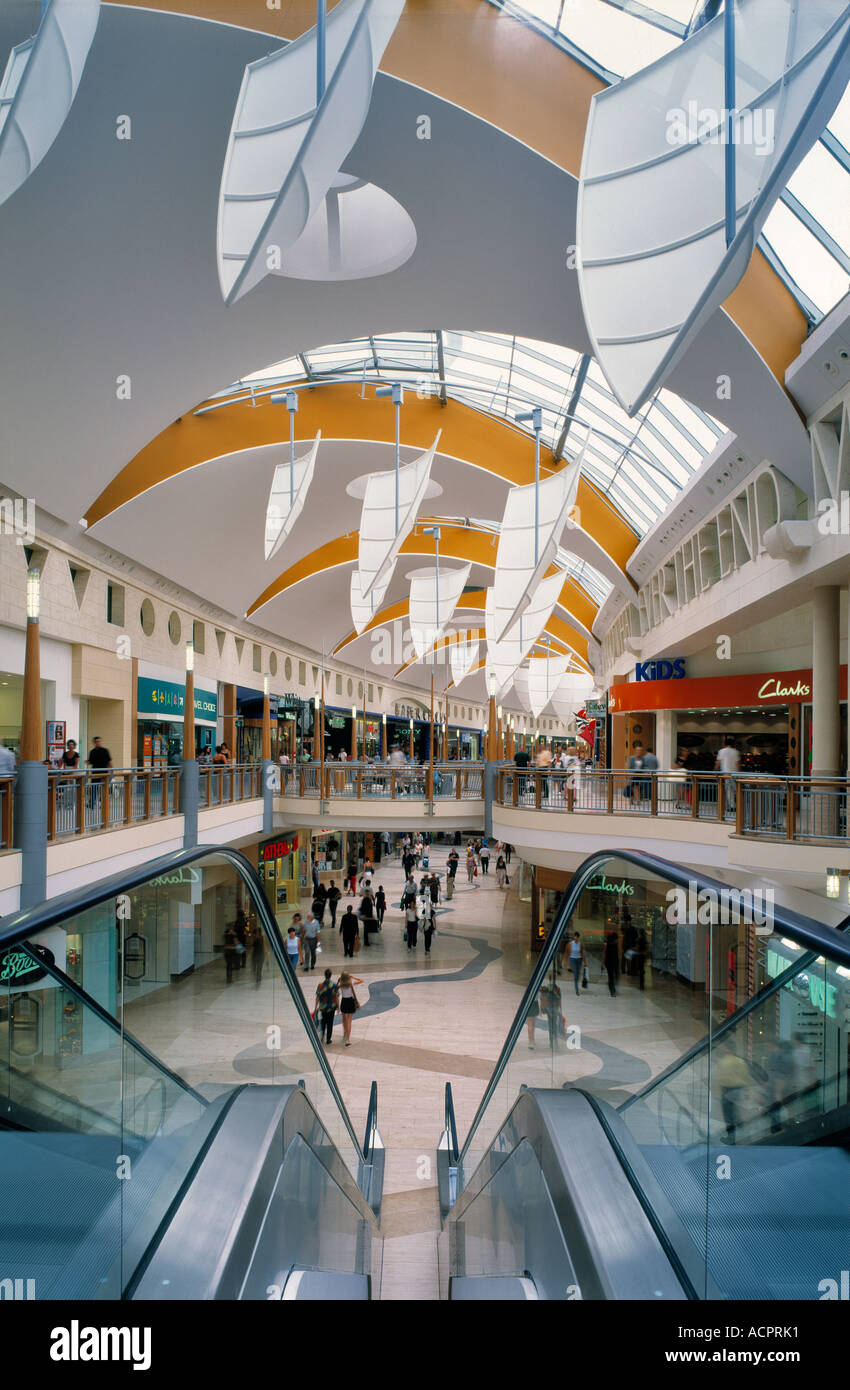
Brunel Shopping Centre serves as the main covered retail hub in Swindon town centre, spanning about 520,000 square feet in sections including Canal Walk, The Plaza, Havelock Square, and Regent Street. Managed by FI Real Estate, it hosts over 60 tenants with a mix of national chains such as Boots, Pandora, Lush, Holland & Barrett, The Fragrance Shop, and EE, plus independents and a food area called The Crossing featuring Greggs, Kadosh Sushi, and cafes.
The centre benefits from a 750-space multi-storey car park and central positioning near M4 junctions 15 and 16, Swindon railway station, and bus services. However, it grapples with elevated vacancy levels, especially in the western Arcade area closed since November 2024 to curb antisocial behaviour and consolidate operations. The 2023 closure of anchor Marks & Spencer has exacerbated challenges, with recent 2025 store shutdowns like High Scores Arcade and Sweets Galore citing low footfall and high business rates.
Footfall has stabilized around pre-COVID levels in core zones but lags in peripherals, drawing mainly daytime car-borne shoppers from Swindons middle-income demographic of 233,000 residents, projected to reach 240,000 by 2028. Market reports indicate stable Zone A rents near £29 per square foot, with 81.7% retention of local comparison goods expenditure totalling £92 million annually. Competition from Greenbridge Retail Park and Swindon Designer Outlet drives 18% leakage, while town centre regeneration via £33 million Fleming Way upgrades and paused high-rise proposals could enhance accessibility and mixed-use appeal, though aging infrastructure and category saturation present leasing risks for retailers seeking balanced performance metrics.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 06:00 PM |
| Tuesday | 09:00 AM — 06:00 PM |
| Wednesday | 09:00 AM — 06:00 PM |
| Thursday | 09:00 AM — 06:00 PM |
| Friday | 09:00 AM — 06:00 PM |
| Saturday | 09:00 AM — 06:00 PM |
| Sunday | 10:30 AM — 04:30 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Accessibility
Swindon borough population stands at approximately 233,000, with a broader study area of 552,000, growing at 2.7% to 566,000 by 2028 per ONS projections. The demographic profile features middle-income households with per capita comparison spend of £3,609 and convenience spend of £2,234, primarily families and commuters from surrounding Wiltshire and Gloucestershire. Accessibility supports retail viability through proximity to M4 (15 minutes from junctions 15/16) and A419, plus a dedicated 750-space car park; 62% of visitors arrive by car, 15% by bus. Swindon station offers frequent services to London (under 1 hour) and Bristol, but pedestrian routes are obstructed by railway barriers and Fleming Way, though £33 million improvements since 2023 include a new bus interchange and level crossings, potentially boosting footfall by 2025 end. Challenges include poor evening access and perceptions of unsafety in northern areas, limiting non-retail draws.
Tenant Mix and Occupancy
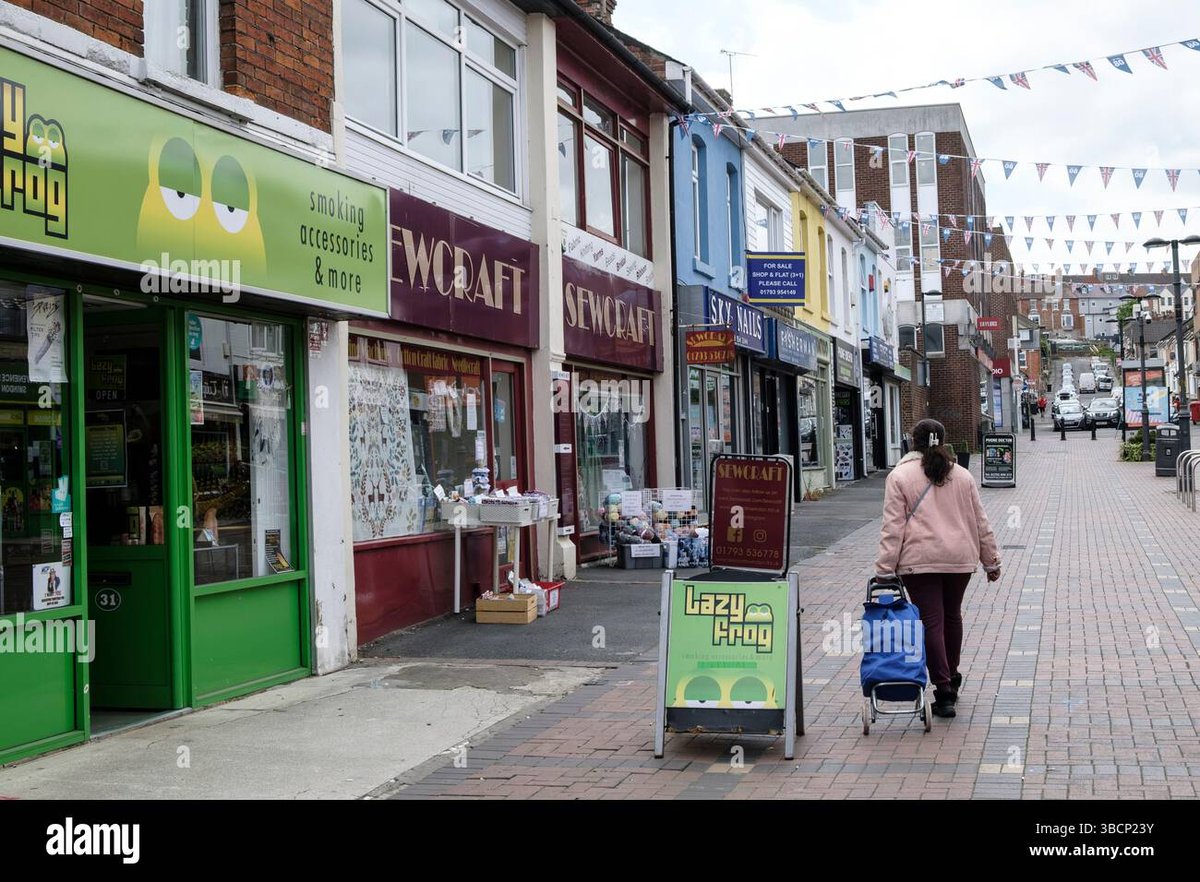
Tenant mix emphasises comparison retail with nationals like Boots (anchor), Pandora, Lush, Card Factory, Claire’s, and Vision Express, complemented by independents in fashion, health, and accessories; food and beverage is modest via The Crossing with quick-service options like Greggs and takeaways, lacking robust evening variety. Occupancy suffers from high vacancies, with western sections nearly empty and cordoned since late 2024, contributing to town centre rates doubling since 2015 and exceeding UK averages; 2024 reports note 25% of visitors disliking empty units. Post-M&S closure in 2023, consolidation targets The Plaza and high street, with recent 2025 exits of arcades and sweet shops due to footfall dips and rate pressures. Opportunities exist for leases in prime 60+ units, but require addressing dated facades and security to sustain 55% annual visitor rate focused on non-food shopping 3-4 times yearly.
Competition and Market Risks
Brunel faces stiff competition from out-of-centre sites like Greenbridge Retail Park (14.1% market share, £194 million turnover), Swindon Designer Outlet (4.7%, fashion-focused), Orbital Shopping Park (4%), and Saint Margarets (3.9%), plus 18.3% leakage to Bristol Cribbs Causeway and Bath. As Swindon town centres top-tier destination, it captures 6.6% of area comparison spend (£92.1 million in 2023), but oversupply signals negative floorspace need of -25,000 square metres by 2041, amid 41% shift to online and special trading. Risks include low peripheral footfall, poor evening economy (ghost town post-6pm), and infrastructure aging, with stable rents at £29 per square foot but yields rising to 8% in 2023. Regeneration plans, including paused 2025 high-rise towers for residential/gym integration, aim to diversify, yet market saturation in clothing and weak categories like department stores heighten challenges for new entrants, alongside business rate burdens and post-COVID vitality declines noted in 25% survey feedback on empty shops.
Building Details
Detailed Market Analytics
City Snapshot
Swindon, WIL
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Swindon
Discover more shopping centers in Swindon.
Popular in United Kingdom
Top retail destinations across United Kingdom.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Swindon, WIL
Comprehensive market intelligence for retail expansion in this city