Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
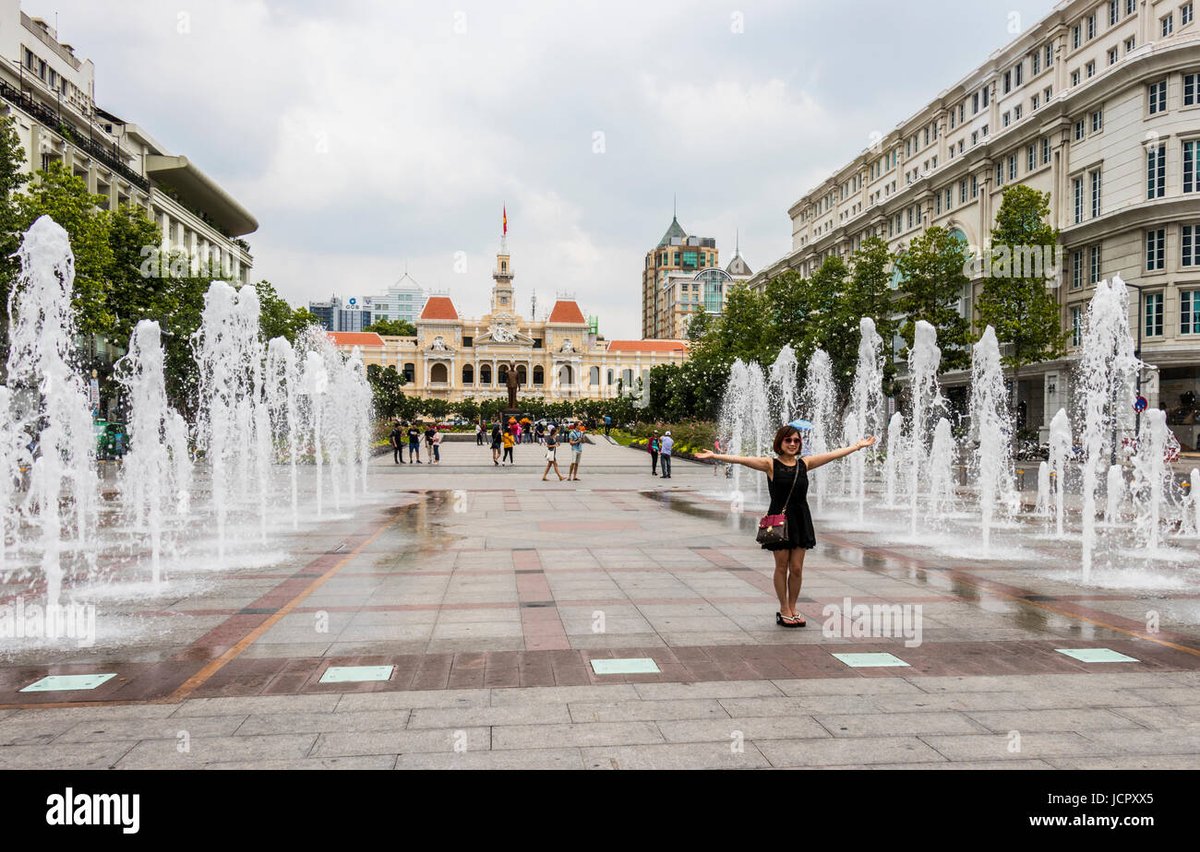
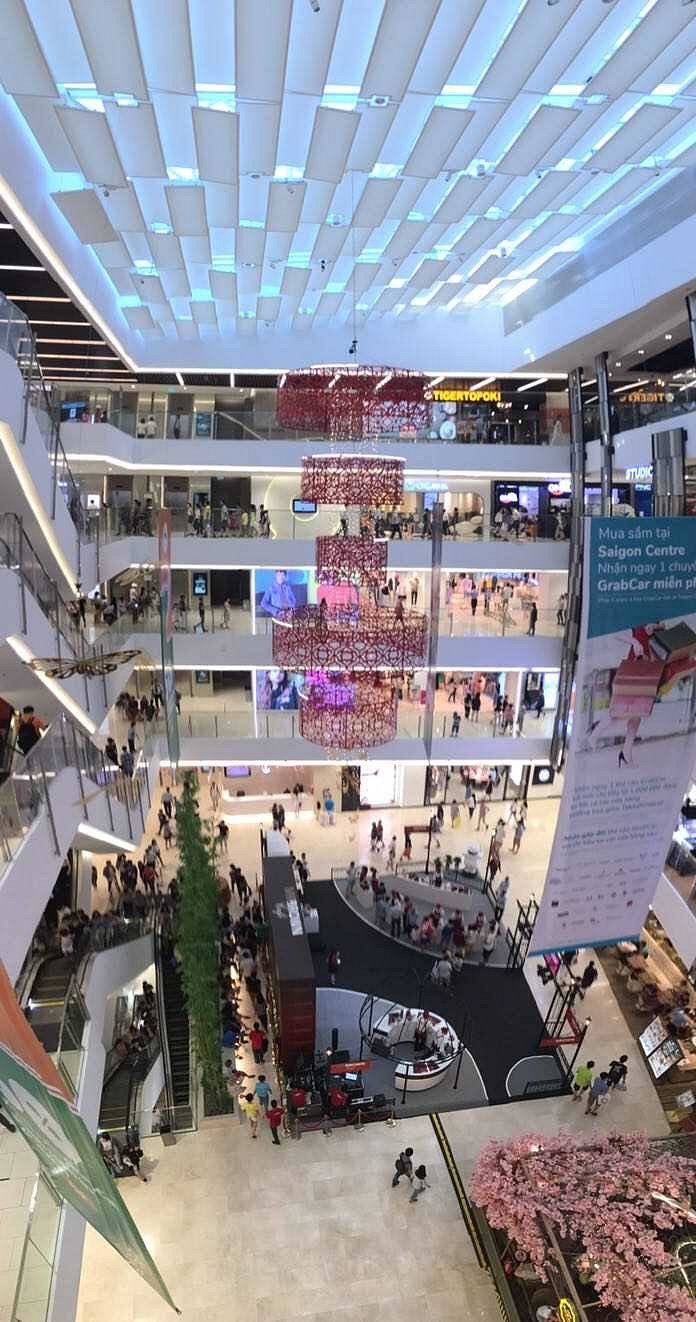
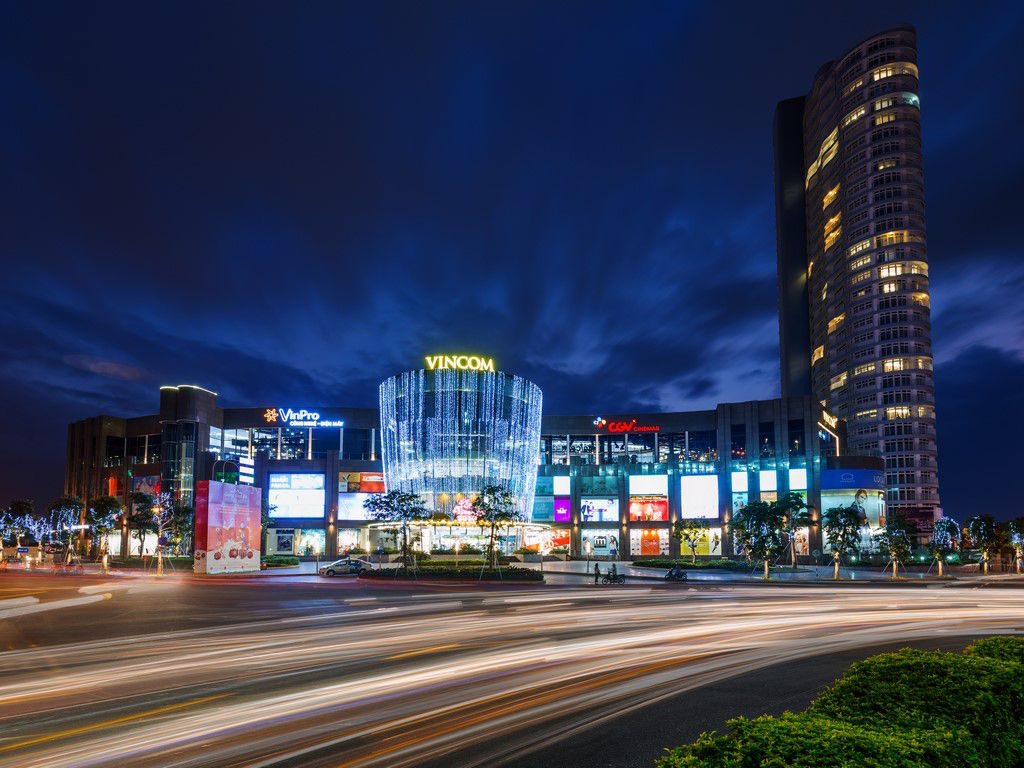
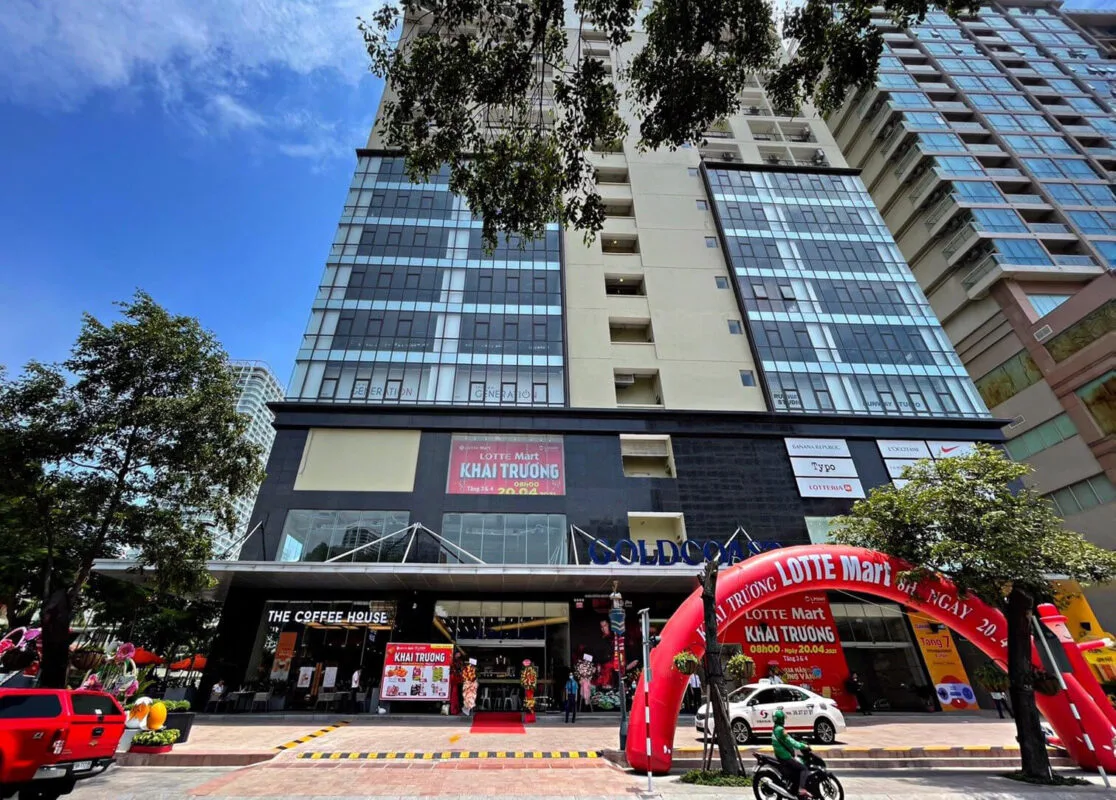
An Khang Plaza is a neighborhood shopping center in District 7, Ho Chi Minh City, situated in the upscale Phu My Hung urban area developed by Korean investors in the late 1990s.
Spanning about 8,000 square meters of gross leasable area, it caters primarily to local residents, expatriates, and nearby office workers with a focus on daily necessities and convenience services. The tenant mix comprises a central supermarket anchor (Co.op Food), several F&B outlets including coffee shops and fast-casual eateries, apparel and accessory stores, a pharmacy, and small electronics retailers, representing roughly 35% grocery, 30% dining, 20% fashion, and 15% other services.
In the competitive Ho Chi Minh City retail landscape, where total supply exceeds 1.2 million sqm with 93% average occupancy as per Q2 2025 Cushman & Wakefield reports, An Khang Plaza holds a niche position serving the affluent District 7 community, characterized by high household incomes averaging VND 40-60 million monthly and a demographic of young professionals, families, and 25% foreign residents.
Footfall averages 4,000-5,500 visitors daily, bolstered by proximity to residential towers and international schools, though it lags behind mega-malls like Crescent Mall.
Rent levels range from VND 35-55 per sqm per month for prime spaces, competitive for suburban locations but pressured by nearby competitors.
Accessibility via major roads like Nguyen Van Linh is adequate, with parking for 200 vehicles, yet traffic congestion and seasonal flooding pose challenges.
Operational quality is moderate, with some aging infrastructure evident in HVAC systems and facades, potentially increasing maintenance costs for tenants.
Leasing advantages include flexible space configurations from 50-500 sqm, short lead times for fit-outs, and a loyal local customer base reducing marketing needs; however, drawbacks encompass category saturation in F&B, limited draw for tourist traffic, and vulnerability to economic fluctuations impacting discretionary retail.
Overall, it suits established local brands seeking stable, low-competition exposure rather than high-volume national chains.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 11:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
District 7s population exceeds 350,000, with Phu My Hung featuring a affluent profile: 60% aged 25-45, median income VND 50 million monthly, and 30% expatriates from Korea, Japan, and Europe per local market data. This supports consistent demand for convenience and lifestyle retail. Daily footfall at An Khang Plaza is approximately 5,000 visitors, higher on weekends due to family outings, but constrained by suburban setting compared to central HCMC malls averaging 20,000+. Proximity to offices and schools enhances weekday traffic, though public transport options remain limited, relying on private vehicles.
Tenant Mix and Occupancy
The tenant mix emphasizes everyday essentials with Co.op Food as anchor drawing 40% of traffic, complemented by 25 F&B units (cafes, bakeries), 15 fashion/accessory shops, and service providers like clinics. Occupancy hovers at 82-85% as of mid-2025, stable but below city average of 93%, reflecting selective leasing amid post-pandemic recovery. Strengths include low tenant turnover (under 10% annually) and diverse categories reducing risk concentration; weaknesses involve vacancies in upper floors due to lower visibility and competition from e-commerce eroding non-essential sales.
Competition and Lease Terms
Intense local competition from Crescent Mall (50,000 sqm, 95% occupancy) and SC VivoCity (120,000 sqm) in District 7 fragments market share, particularly in entertainment and dining, leading to 5-7% sales pressure per Savills reports. Lease terms are 3-5 years with 8% annual escalations, turnover rents optional at 5-10% of sales, and incentives like 1-2 months free rent for long commitments. Risks include infrastructure upgrades needed for the 20-year-old building, potential rent hikes amid inflation, and access issues from urban traffic, advising tenants to negotiate capex contributions and review egress clauses for flood-prone seasons.
Building Details
Detailed Market Analytics
City Snapshot
Ho Chi Minh City
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Ho Chi Minh City
Discover more shopping centers in Ho Chi Minh City.


Popular in Vietnam
Top retail destinations across Vietnam.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Ho Chi Minh City
Comprehensive market intelligence for retail expansion in this city