Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
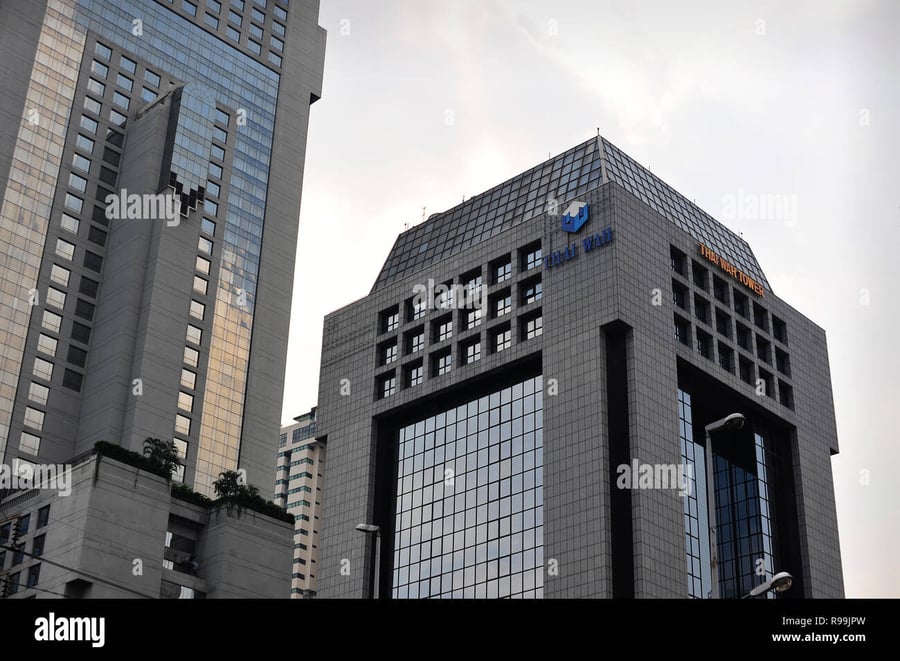
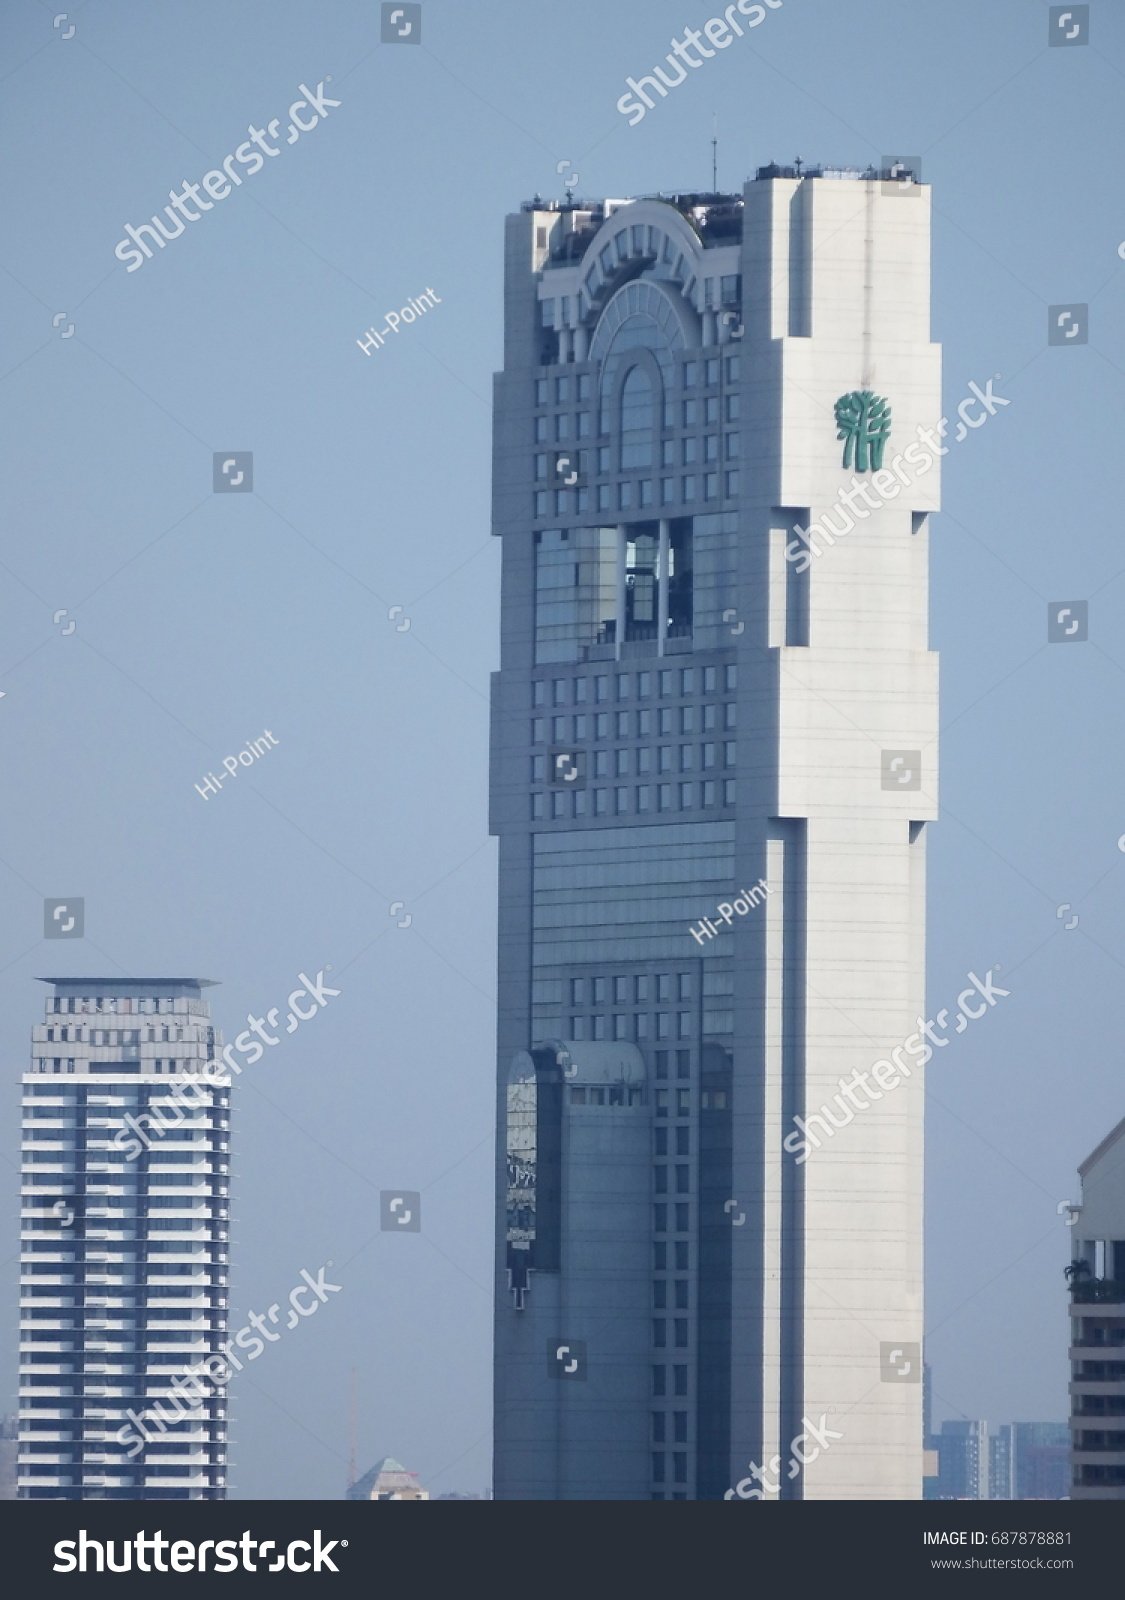
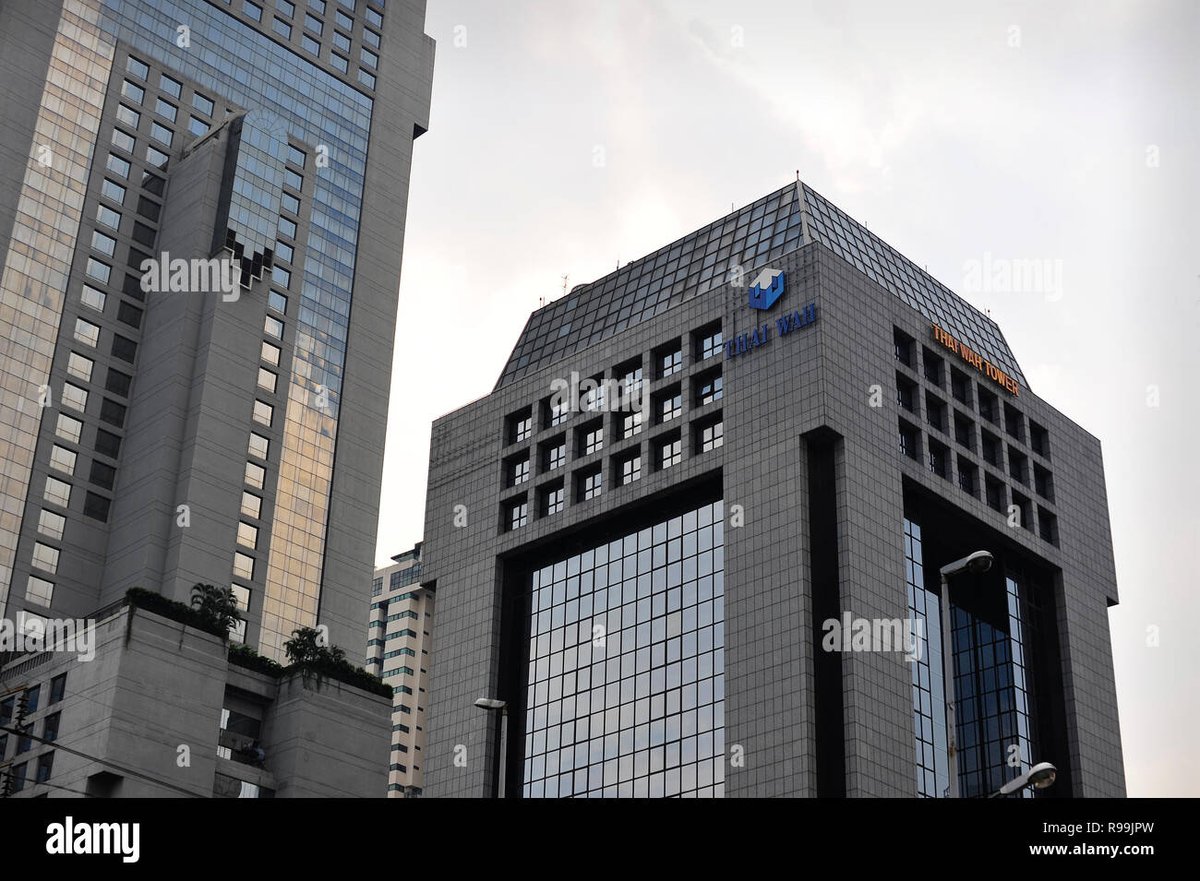
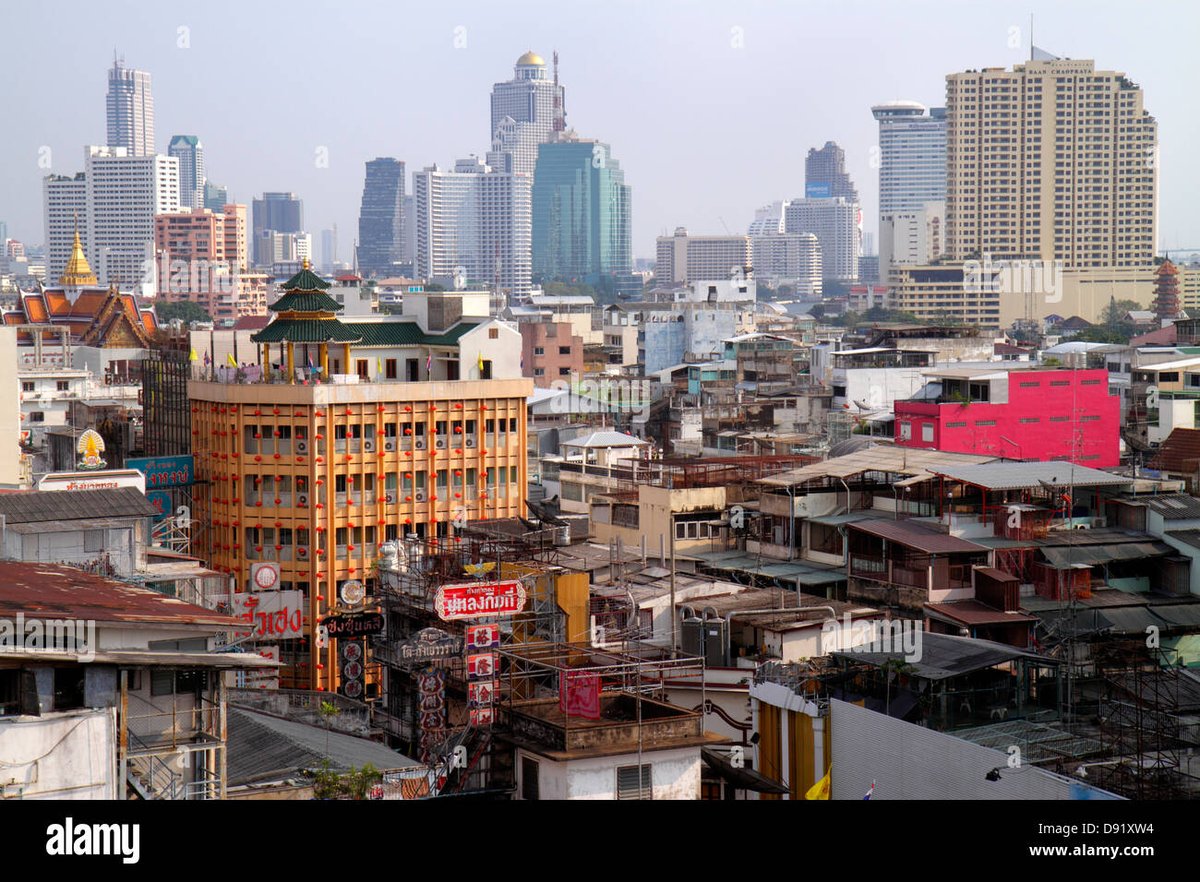
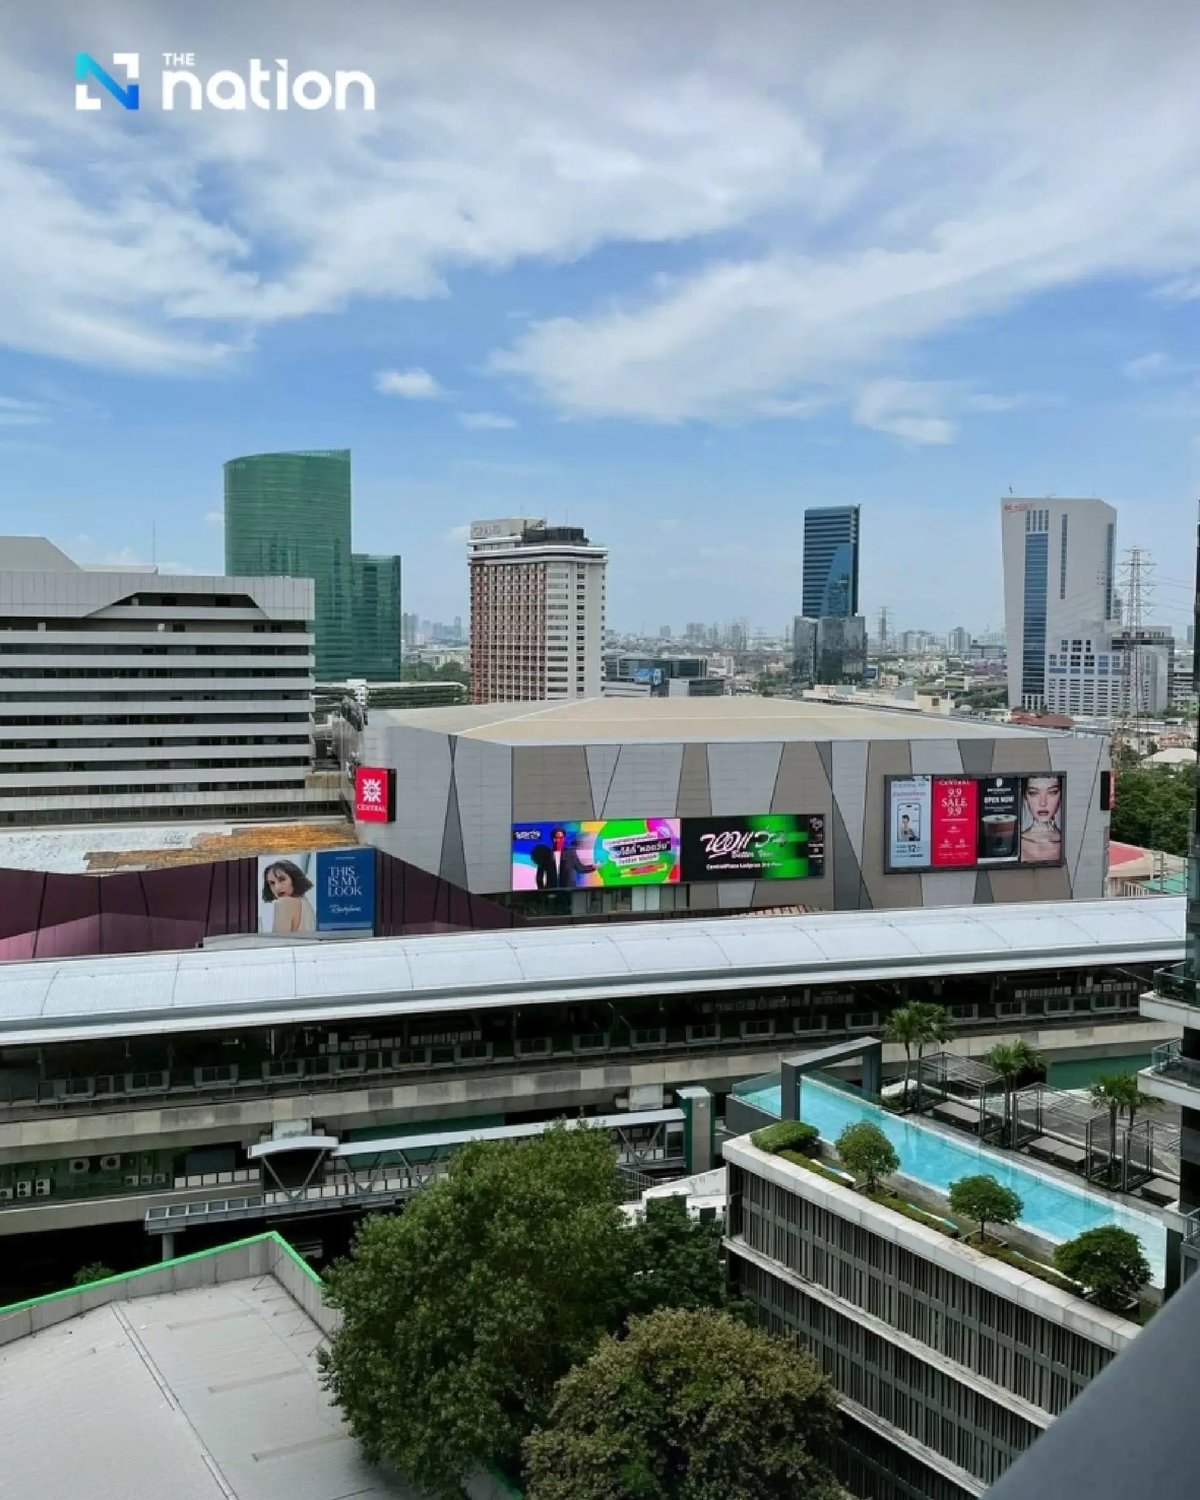
Thai Wah Tower is a 24-storey Grade A office building situated at 21 South Sathorn Road in Bangkok Central Business District, developed by Thai Wah Public Company Limited. It encompasses roughly 20,000 sq m of net leasable office area, complemented by ground-floor retail spaces totaling about 2,000 sq m designed for office tenants and local foot traffic.
Accessibility is a key strength, with proximity to MRT Lumpini Station (400 meters) and BTS Saladaeng Station (800 meters), enabling efficient commuter access and contributing to estimated daily footfall of 15,000-20,000 from professionals and transit users. The surrounding Sathorn area serves a demographic primarily of white-collar workers, expatriates, and government employees, featuring households with average monthly incomes exceeding THB 100,000, according to Cushman and Wakefield market data.
Retail tenant mix focuses on convenience-oriented outlets, including FandB establishments (approximately 40%), services like banks and pharmacies (30%), and essential retail such as convenience stores (30%), fostering a supportive environment for daily needs without heavy emphasis on luxury or entertainment. In the competitive Sathorn submarket, the property holds a solid position amid prime office rents averaging THB 700-800 per sq m per month and retail rents at THB 1,000-1,500 per sq m, with overall occupancy rates around 85% for offices and 90% for retail as of Q3 2025 per JLL reports.
Leasing advantages include flexible terms with potential rent abatements of 3-6 months, ample parking at THB 2,000 per car per month, and modern facilities like high-speed elevators and security systems. However, drawbacks encompass competition from adjacent mixed-use projects such as Empire Tower and The PARQ, which offer more diverse retail experiences; traffic congestion impacting accessibility during peak hours; and an aging structure (constructed in 1988) that may necessitate infrastructure investments.
Market factors like Bangkok retail sectors gradual recovery, with new supply adding 142,100 sq m in Q3 2025, introduce risks of rent pressure and category saturation, particularly in FandB, while strengths lie in its captive office audience ensuring steady performance for aligned retailers.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 09:00 AM — 06:00 PM |
| Tuesday | 09:00 AM — 06:00 PM |
| Wednesday | 09:00 AM — 06:00 PM |
| Thursday | 09:00 AM — 06:00 PM |
| Friday | 09:00 AM — 06:00 PM |
| Saturday | Closed |
| Sunday | Closed |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
Sathorn districts demographic profile centers on affluent professionals aged 25-44, comprising over 60% of the local population with high disposable incomes averaging above THB 100,000 monthly, as detailed in Colliers Thailand reports. Footfall is bolstered by proximity to mass transit, drawing approximately 50,000 office workers and 20,000 daily commuters, supporting consistent retail traffic. However, dependency on office sector vitality poses risks, with CBAs vacancy at 15-20% potentially reducing spillover if remote work persists; seasonal tourism fluctuations also affect non-office visitors.
Tenant Mix and Occupancy
The retail podiums tenant composition prioritizes practicality, with 40% allocated to FandB outlets like cafes and quick-service restaurants, 30% to financial and health services, and 30% to convenience retail including minimarts. Occupancy remains robust at 90-95%, surpassing Bangkok prime retail average of 92% per Cushman and Wakefield Q3 2025 data, aided by low tenant churn and anchors such as 7-Eleven. Leasing structures provide incentives like stepped rents and fit-out contributions, though saturation in FandB limits expansion opportunities for similar categories.
Competition and Market Risks
Intense rivalry stems from nearby properties like Sathorn Square and Empire Towers retail components, which aggregate over 10,000 sq m of competing space focused on similar convenience and dining options. JLL insights highlight an influx of 215,000 sq m prime retail supply through 2025, exerting downward pressure on rents and occupancy in saturated segments. Additional challenges include the buildings 1988 construction leading to potential maintenance costs and traffic bottlenecks on Sathorn Road reducing impulse visits, though strategic transit links partially offset these factors.
Building Details
Detailed Market Analytics
City Snapshot
Bangkok
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Bangkok
Discover more shopping centers in Bangkok.
Popular in Thailand
Top retail destinations across Thailand.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Bangkok
Comprehensive market intelligence for retail expansion in this city