Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
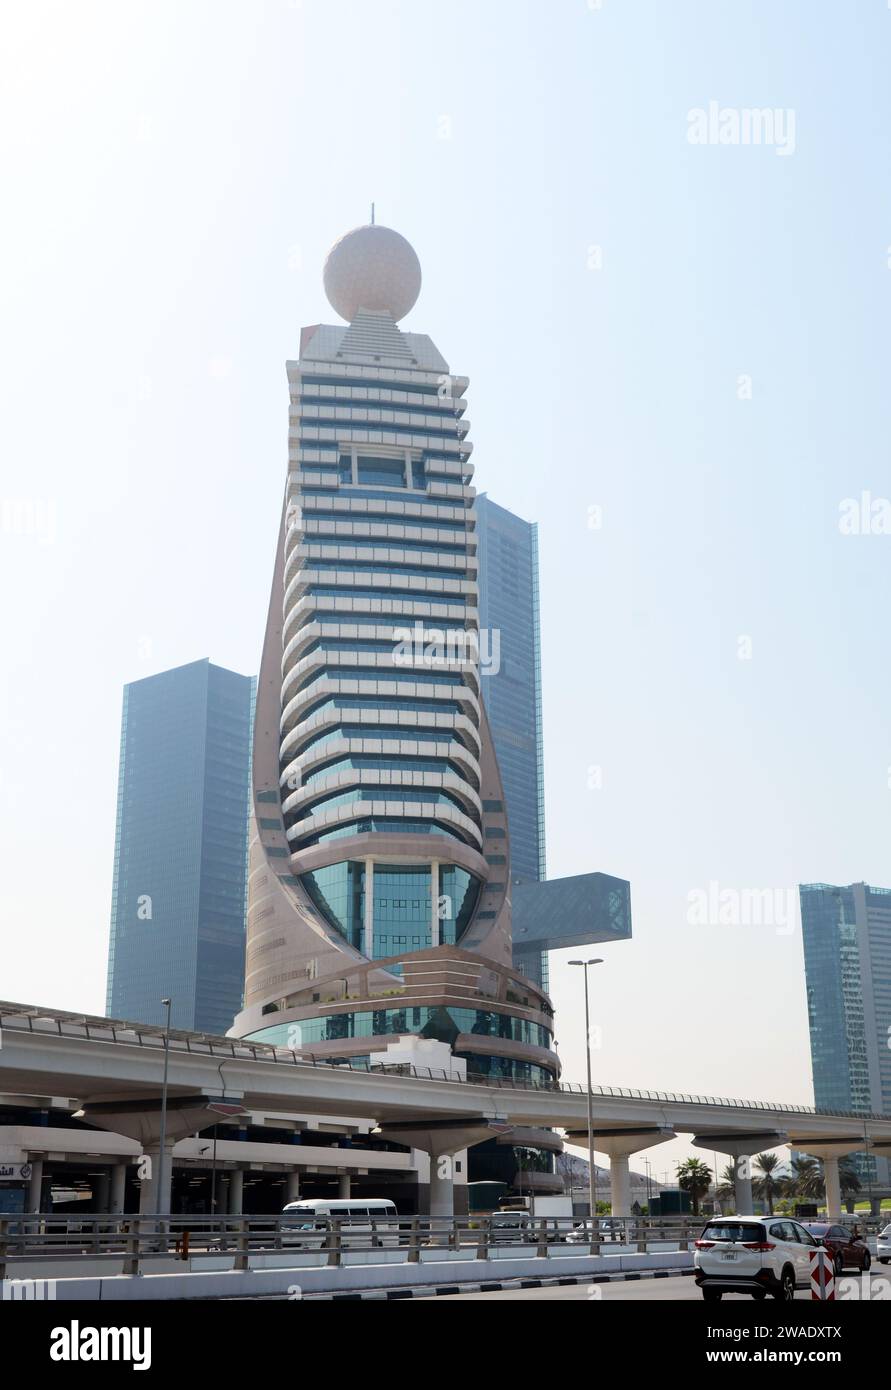
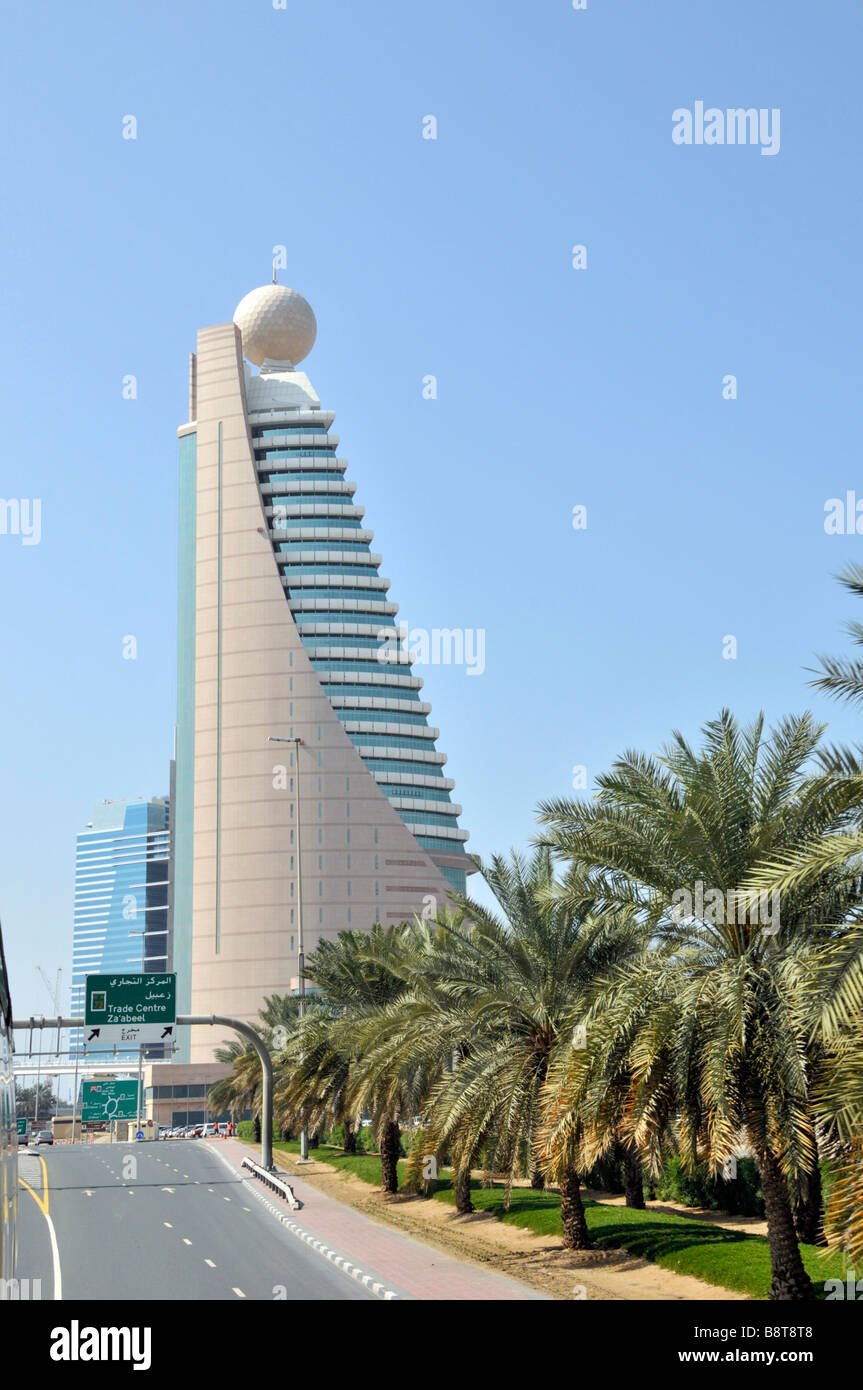
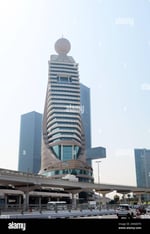
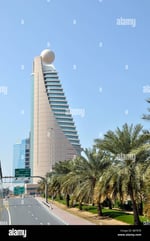
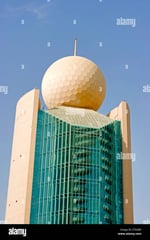
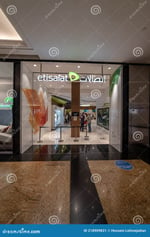
Etisalat Town Centre in Sharjah, UAE, on King Abdul Aziz Street, offers 40,000 sqm GLA in a 2005-built, two-level community mall targeting 1.8 million residents in a 10 km radius, mainly middle-income families and expatriates aged 25-40. With 100 stores anchored by Carrefour and Etisalat, the mix focuses on mid-range fashion, electronics, casual dining, and essentials (15% unique). Occupancy: 85-90%; footfall: 416,667 monthly, 5 million annually (5% growth); sales: AED 8,000/sqm/year.
Accessibility via 1,000-1,500 parking spots and transport, but moderate pedestrian access. Rents: AED 80-120/sqm/year, with 3-6 months free rent, fit-outs. In a market with 3 malls/100k residents and 5-7% growth, it provides value positioning vs Dubai's higher costs, stable essentials demand. However, aging infrastructure, e-commerce (5-7% erosion), competition from Sahara Centre and Dubai malls pose challenges; limited luxury viability due to demographics.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 09:00 PM |
| Tuesday | 10:00 AM — 09:00 PM |
| Wednesday | 10:00 AM — 09:00 PM |
| Thursday | 10:00 AM — 09:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 11:00 AM — 06:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographic Profile
Primary catchment of 1.8 million with median income AED 25,000/month, family size 4.8, age 33.6. Retail spending AED 15,000/capita/year: AED 4,000 groceries, 2,500 apparel, 3,000 electronics. 40% shoppers for retail, 35% dining, 25% services. Price-sensitive, favoring value; premium underperforms. Growth 2.5% annually, 45% tertiary education, low unemployment 2.6%. Cost of living index 65 vs New York 100.
Competition and Market Factors
Competes with Sahara Centre (90,000 sqm, 800,000 monthly footfall) and City Centre Sharjah for broader mix/entertainment. Proximity to Dubai malls diverts affluent, lowering sales. Sharjah saturation moderate; UAE occupancy avg >90%, here 85-90%. E-commerce erodes non-essentials 5-7%/year; hypermarket saturation risk. Stable but competitive market with 5-7% retail growth.
Lease Terms and Operational Quality
Rents AED 80-120/sqm/year (or 100/month noted), incentives: 3-6 months free, fit-out allowances, 3-5 year terms with turnover escalations. Operational: advanced security, low crime, digital signage, 50 promotions/year, 40% loyalty uptake. Strengths in anchors; weaknesses: aging 2005 infrastructure may need upgrades, no expansion. Suits value retail; risks from disruptions.
Building Details
Detailed Market Analytics
City Snapshot
Sharjah
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in Sharjah
Discover more shopping centers in Sharjah.

Popular in United Arab Emirates
Top retail destinations across United Arab Emirates.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Sharjah
Comprehensive market intelligence for retail expansion in this city