Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
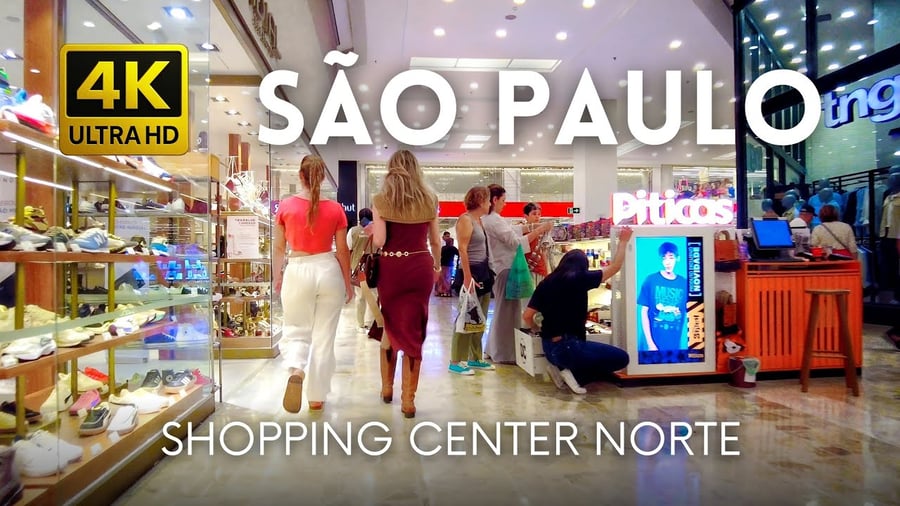
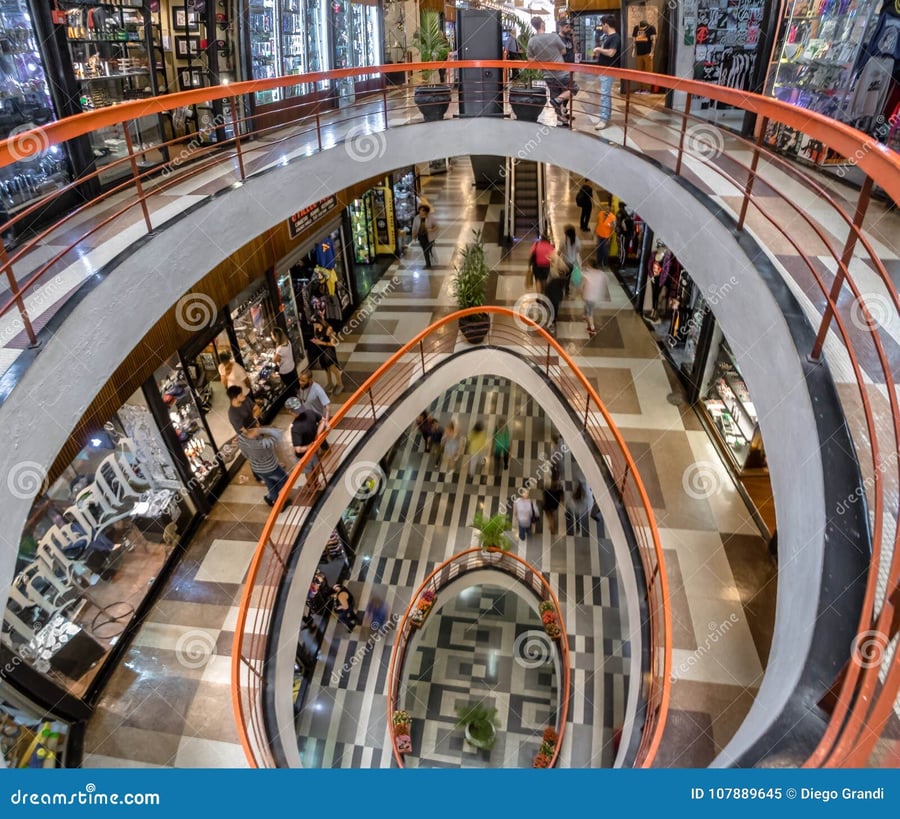
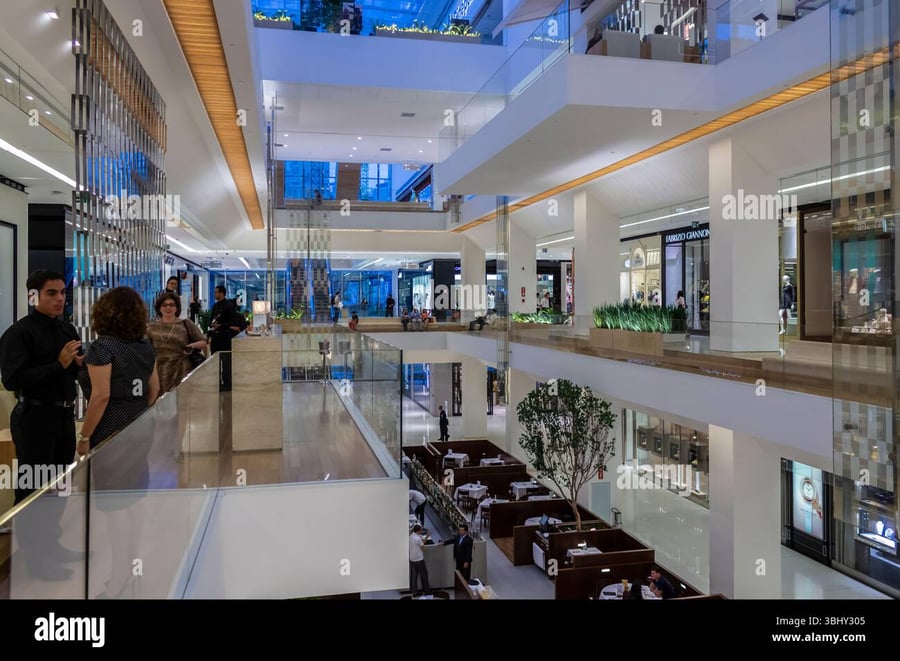
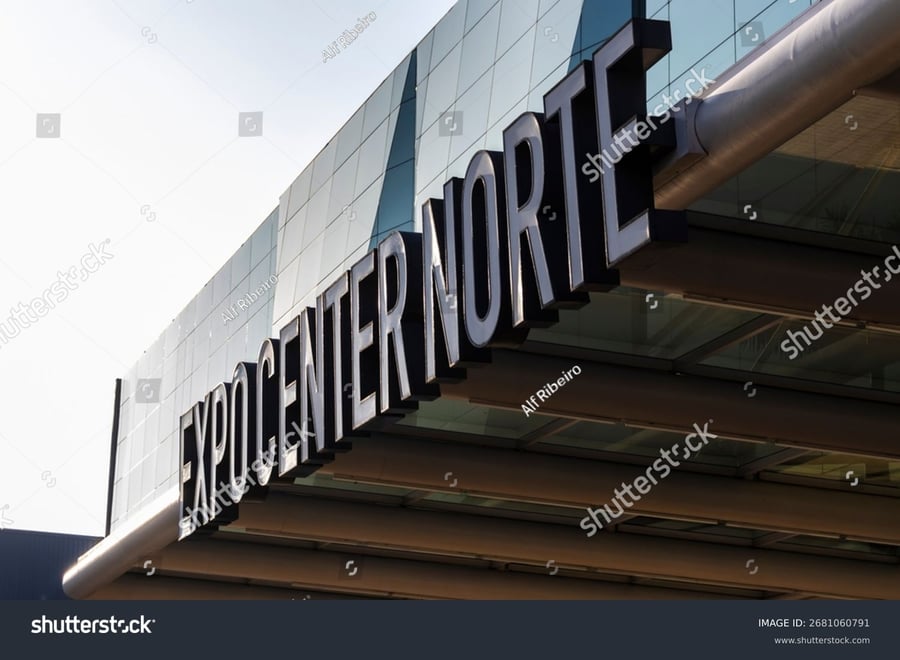
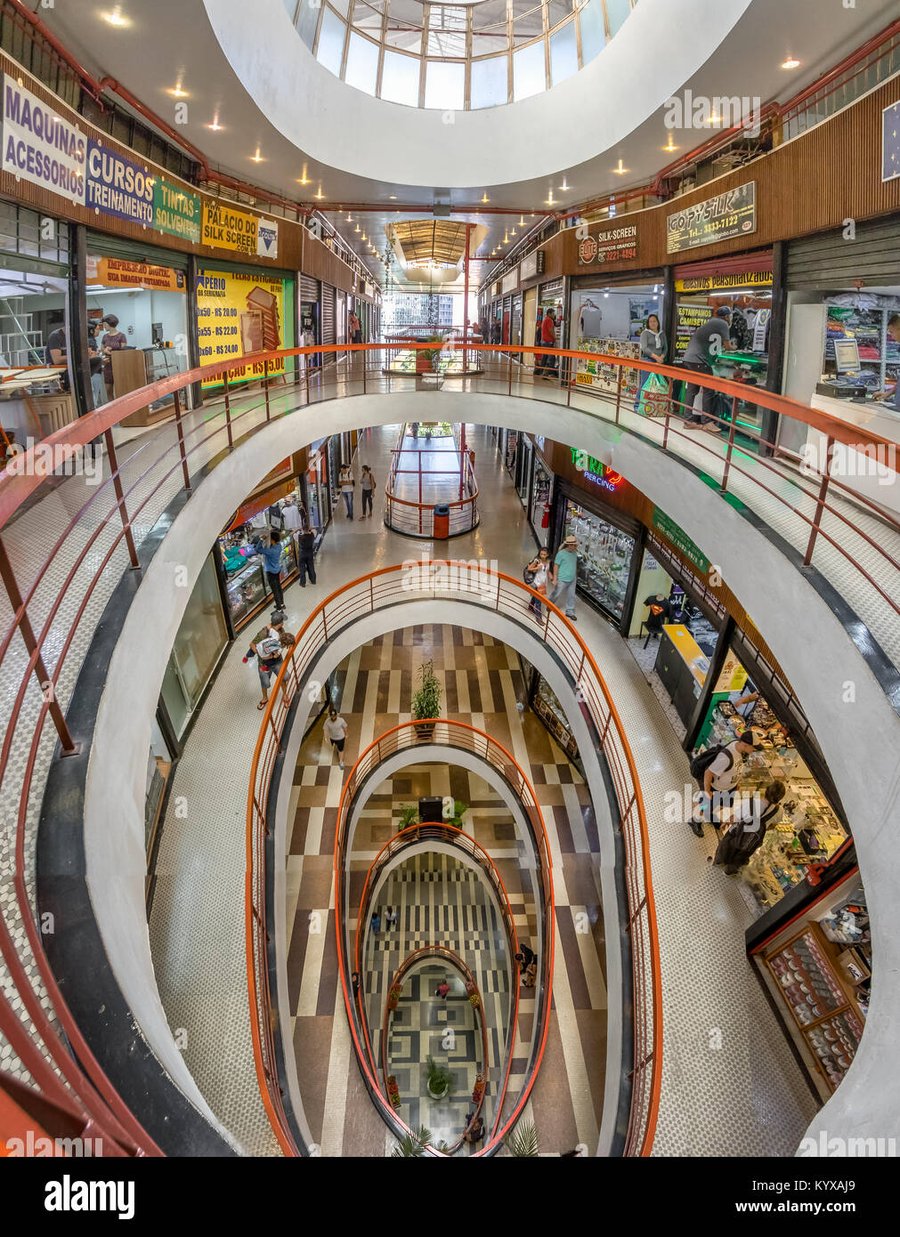
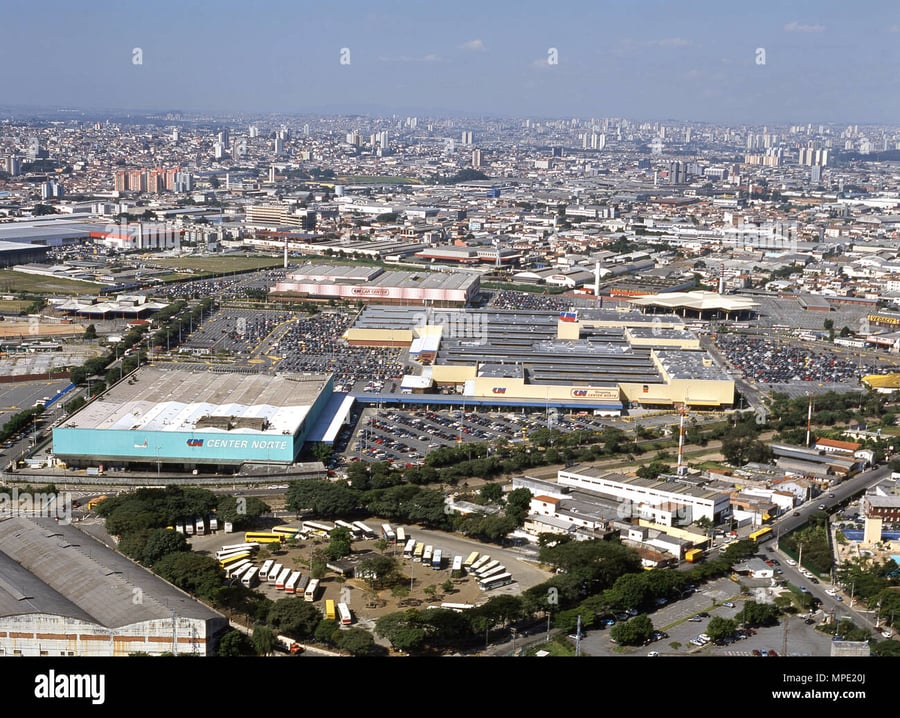
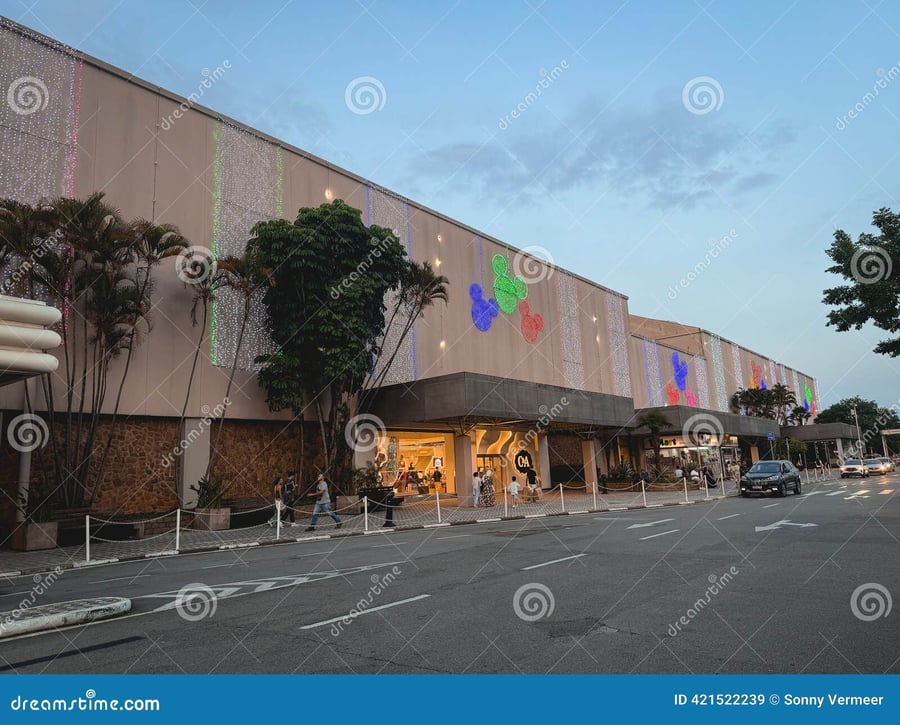
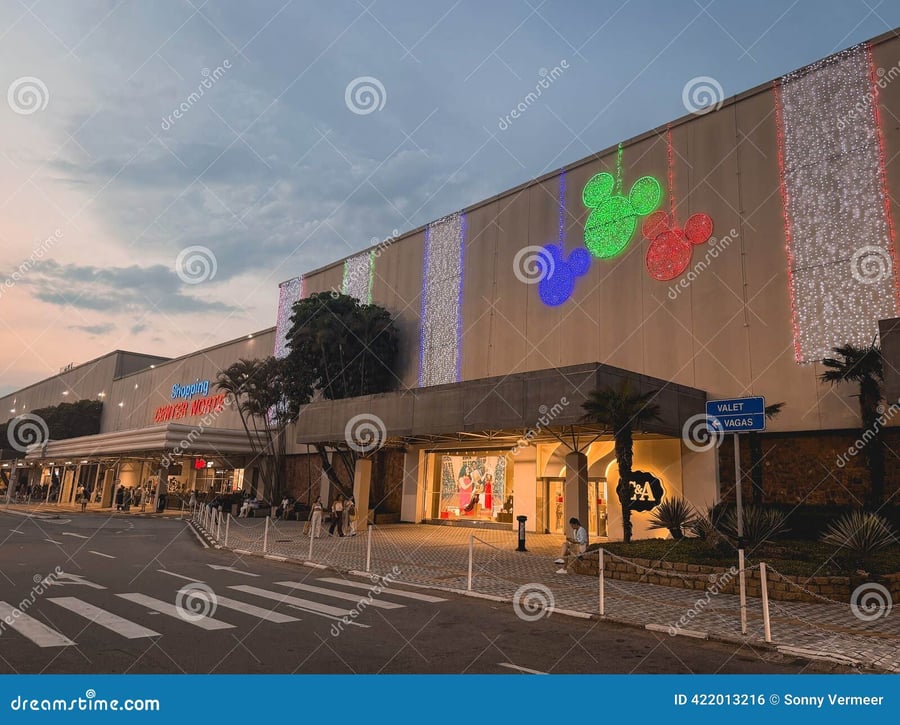
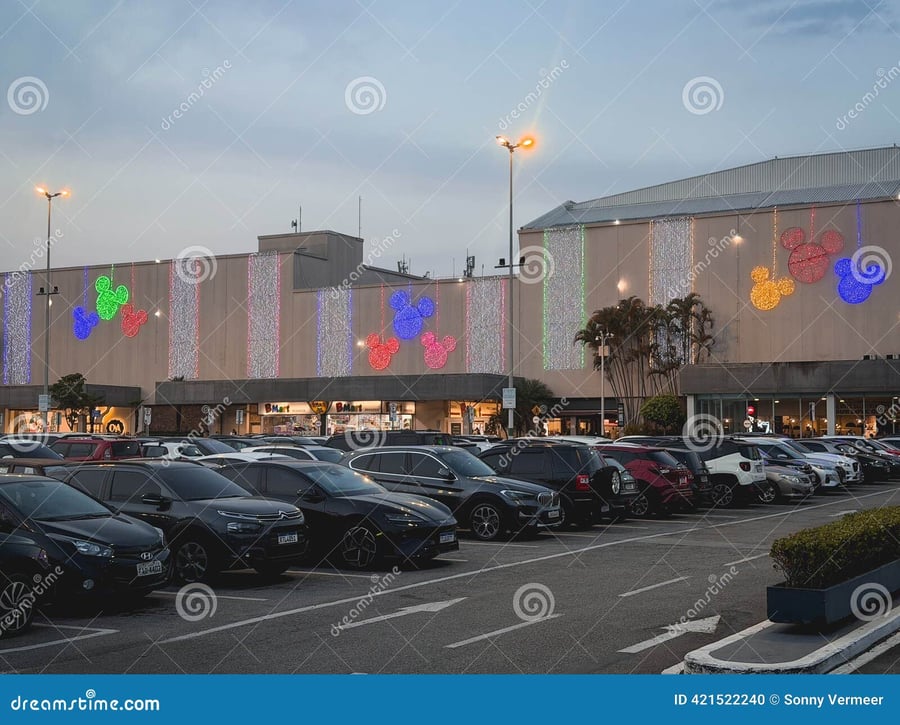
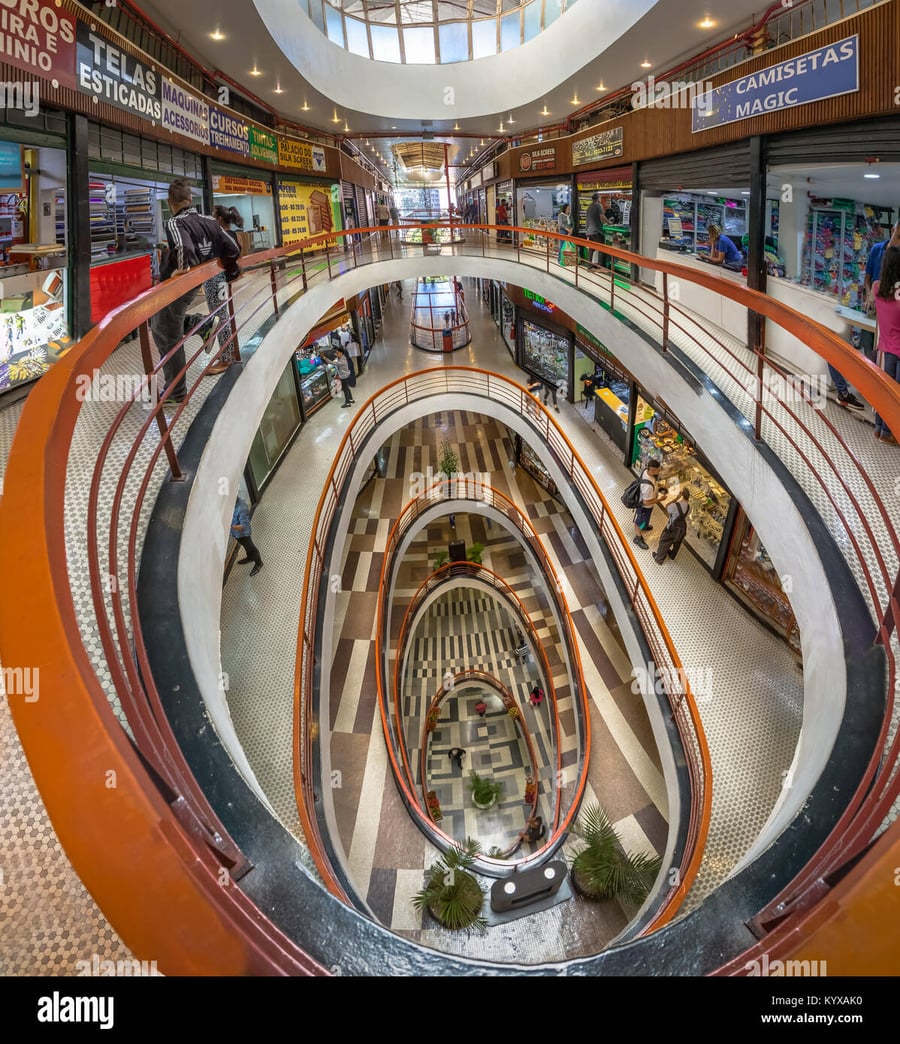
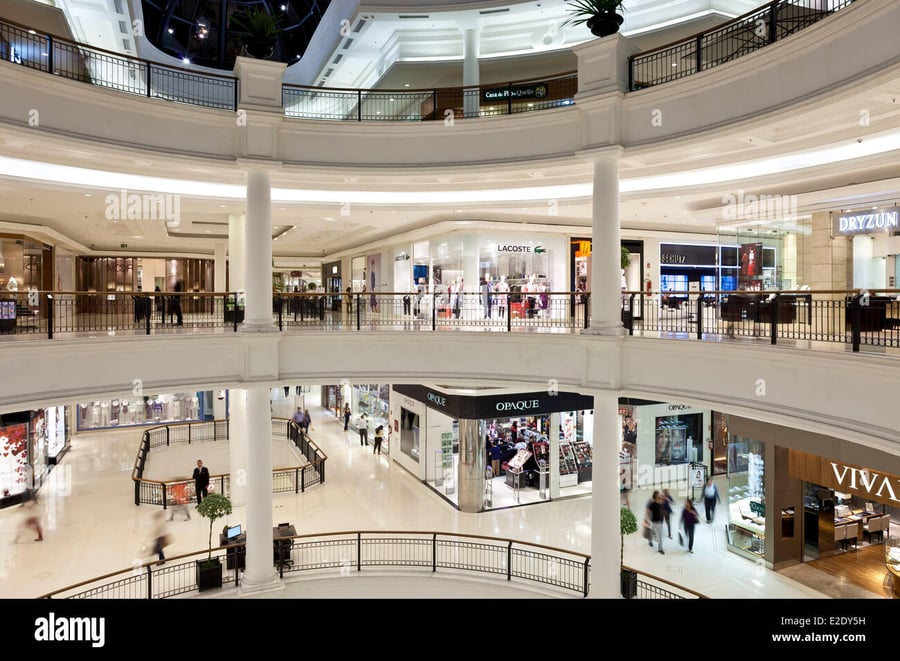
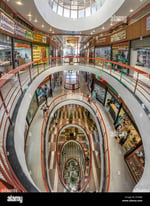
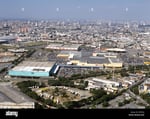
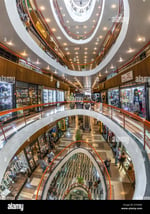
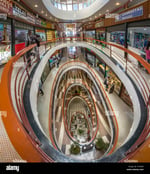
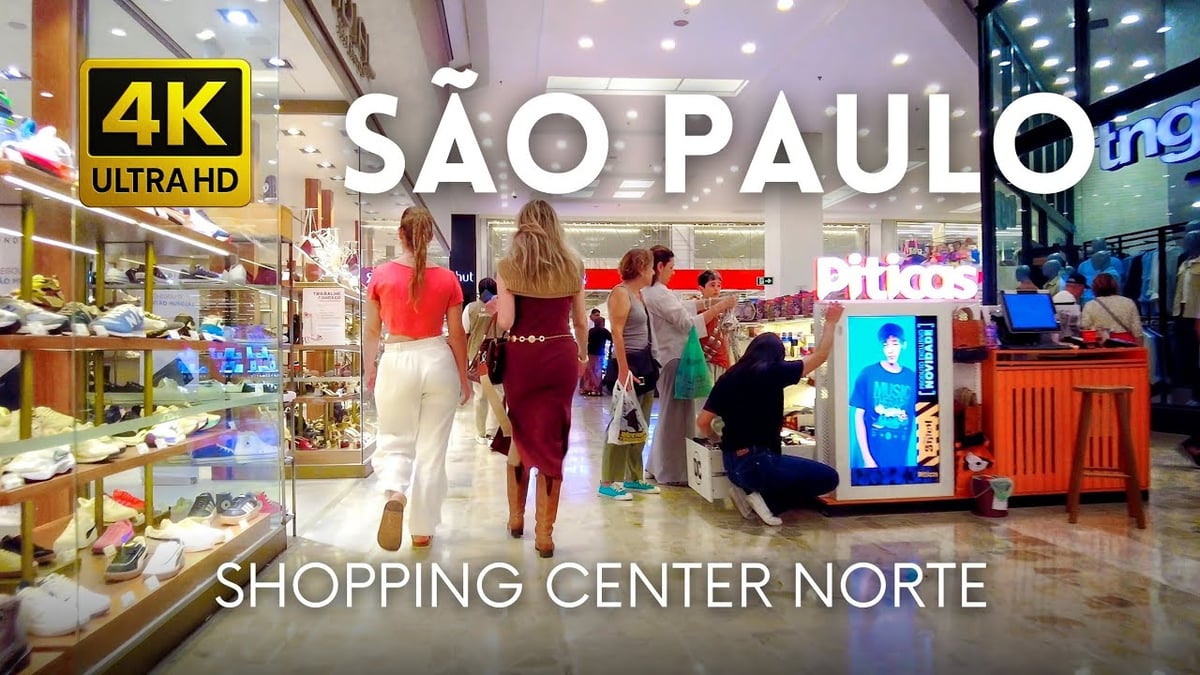
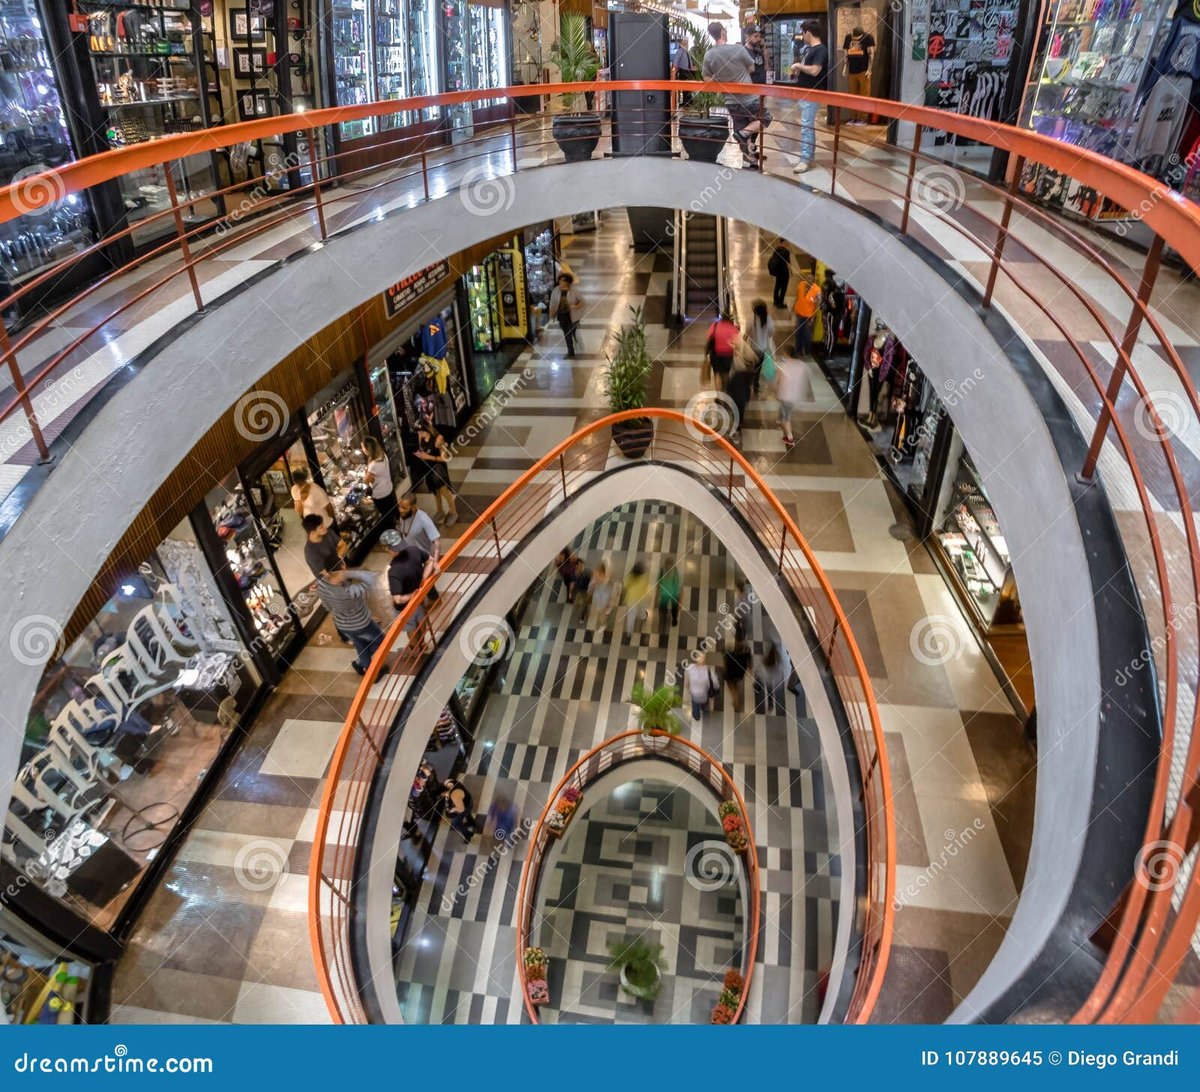
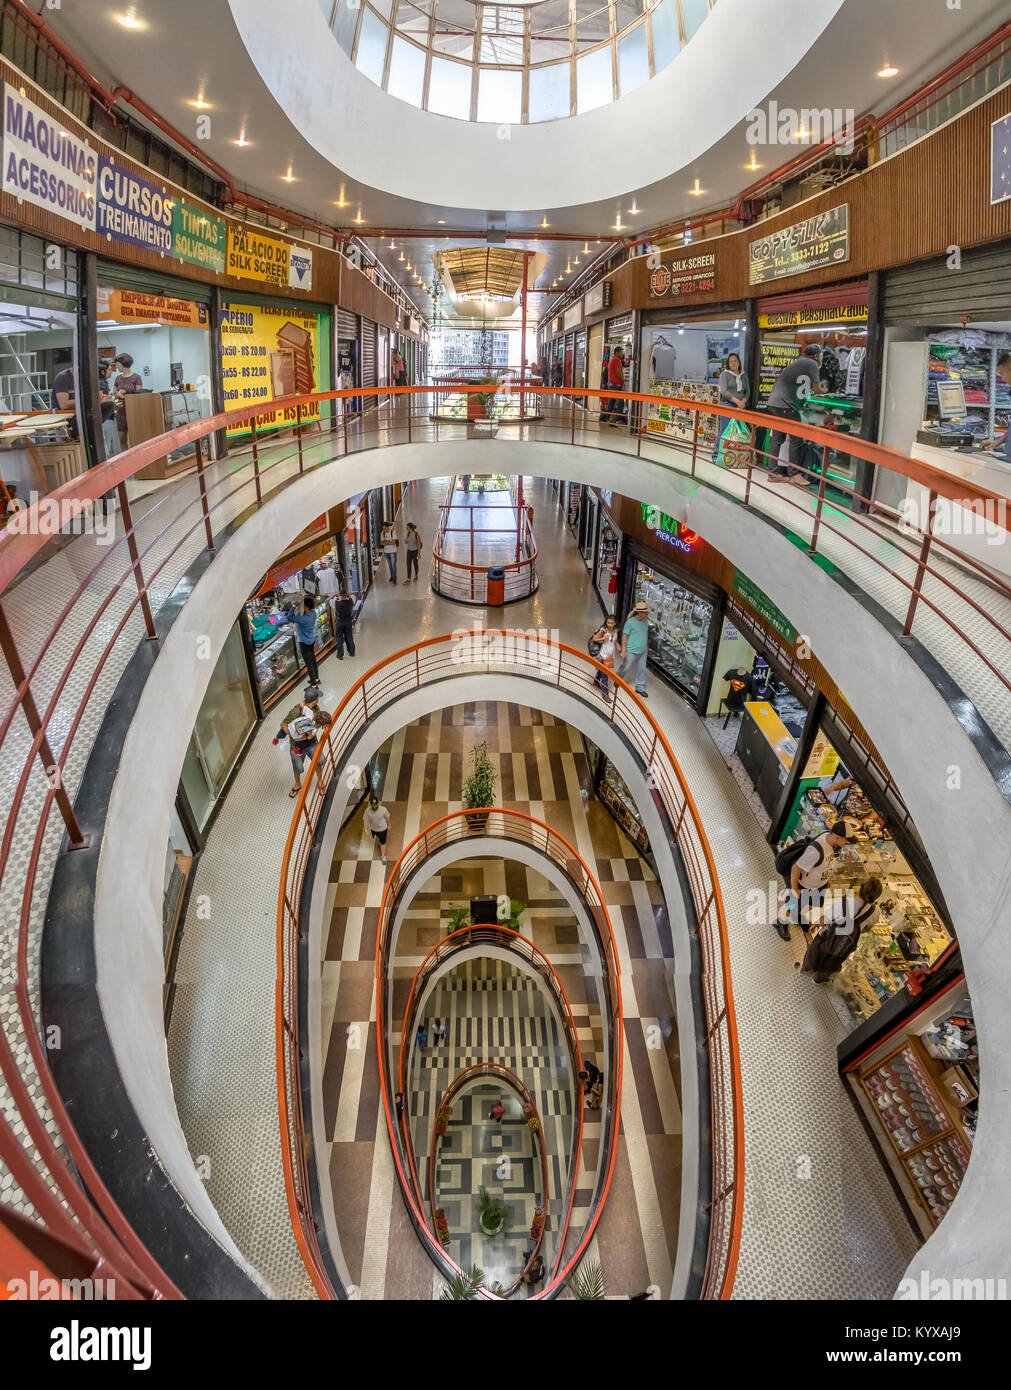
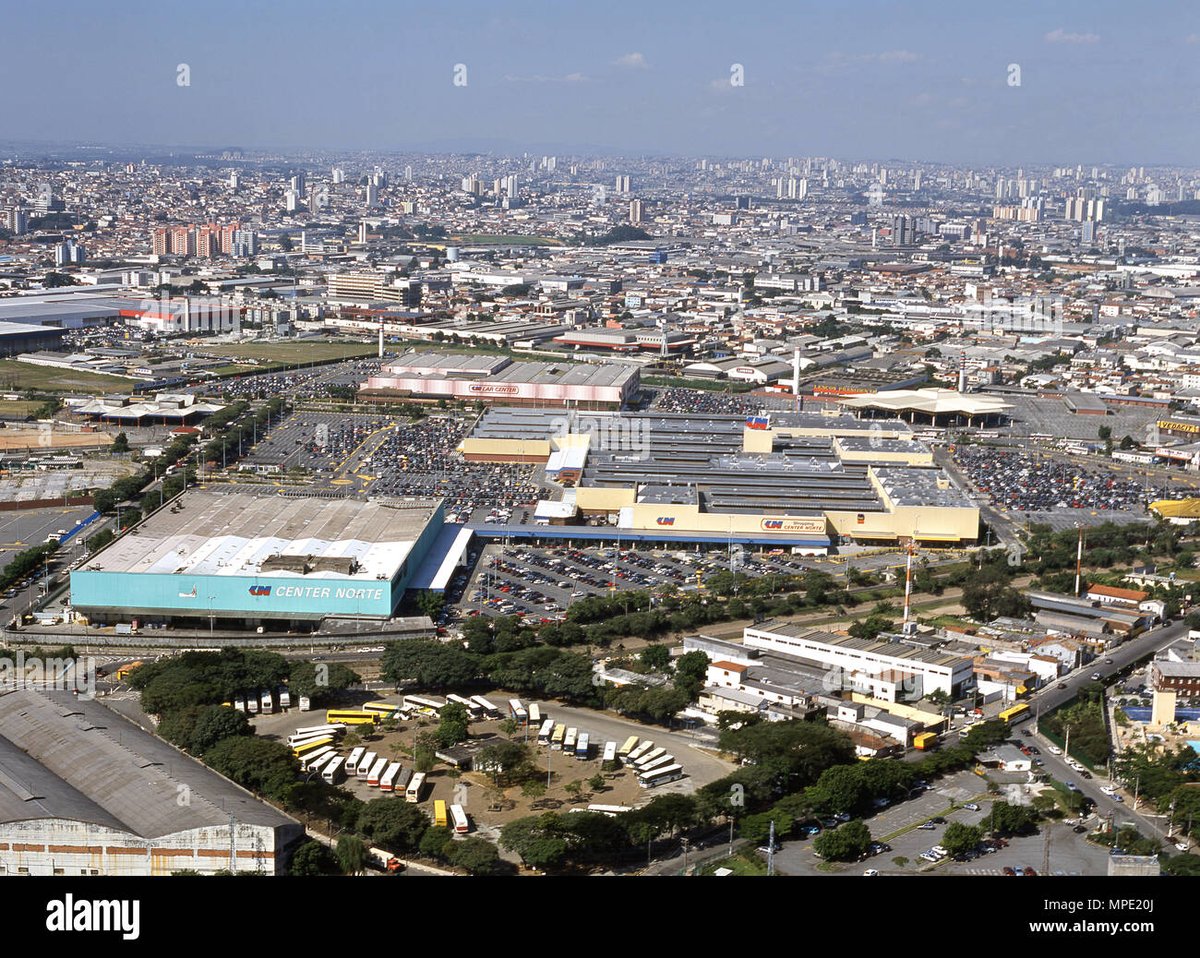
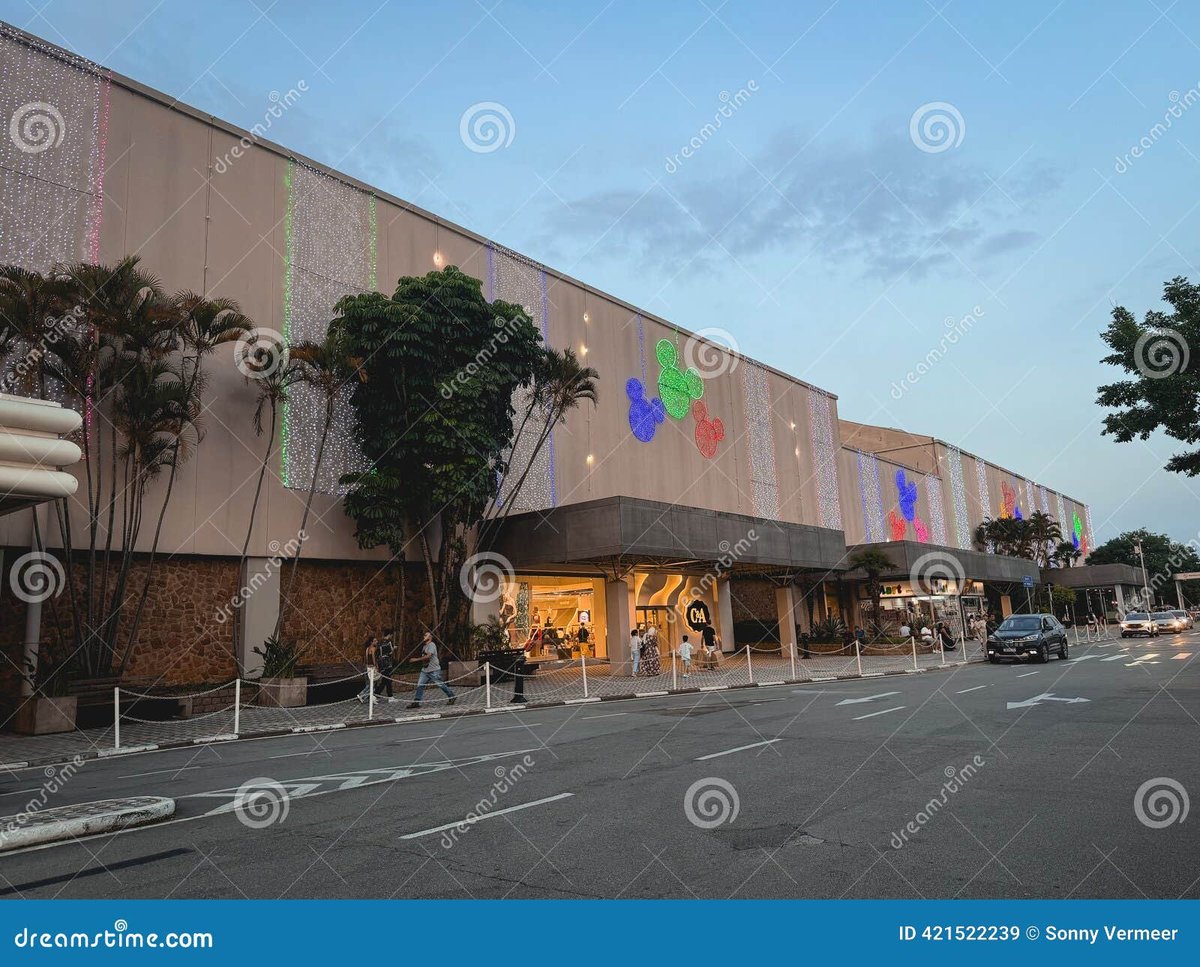
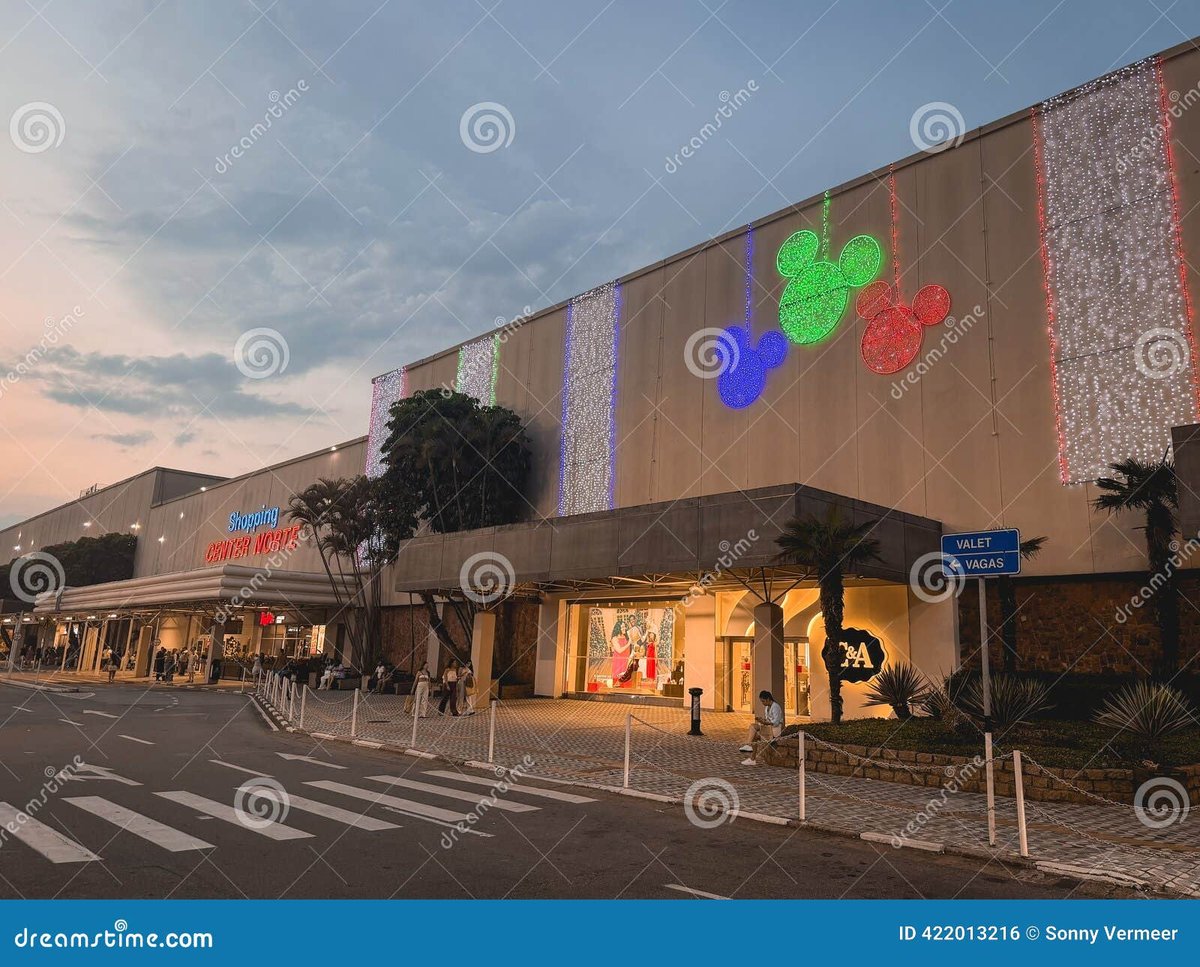
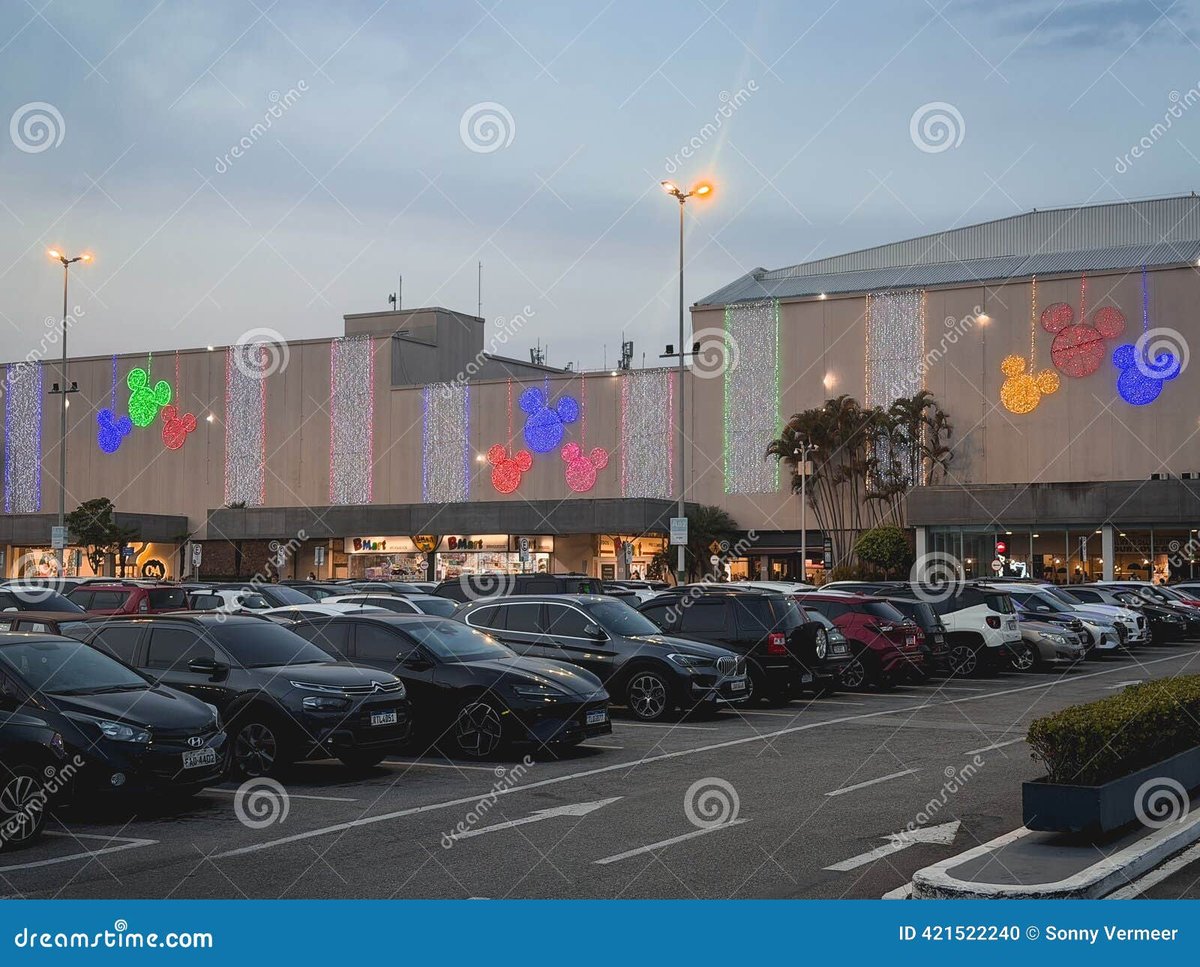
Shopping Center Norte, located in the North Zone of São Paulo along Marginal Tietê, was inaugurated in 1984 as the citys fifth mall and the first in its northern region. It forms part of the expansive Cidade Center Norte complex, encompassing over 600,000 m² with adjacent facilities like Lar Center, Expo Center Norte, and Novotel, enhancing its role as a multi-business hub. The property spans 66,095 m² of gross leasable area (GLA) and hosts 355 stores across diverse categories, including fashion anchors such as C&A, Renner, and Riachuelo; entertainment with Cinemark cinema; and over 50 dining options ranging from fast food to à la carte restaurants.
Additional offerings include sports retailers like Adidas, beauty outlets, and services.
Market position is strong, boasting the highest sales per square meter among São Paulo malls, driven by consistent footfall of approximately 80,000 visitors daily, peaking at 120,000 during special events.
Accessibility is a key strength, featuring a single-level layout without obstacles, pet-friendly policies, and 7,000 parking spaces, though proximity to a major highway can introduce traffic congestion risks. The tenant mix balances family-oriented retail with broad appeal, supporting stable occupancy rates typically above 95% in similar high-performing Brazilian malls per Abrasce reports.
Leasing advantages include high traffic from middle-class demographics in surrounding neighborhoods like Santana and Tucuruvi, proximity to public transport, and ongoing expansions—such as the 2023 10% growth adding 30 stores—which bolster long-term viability. However, retailers face challenges from intense regional competition and São Paulos volatile economic factors influencing consumer spending.
Rent levels average around BRL 150-200 per m² monthly based on commercial real estate data for prime malls, with escalations tied to IGP-M index.
Overall, it offers robust performance metrics but requires evaluation of category saturation in fashion and food sectors.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 02:00 PM — 08:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
The primary catchment area encompasses middle to upper-middle-class families from North Zone neighborhoods including Santana, Tucuruvi, Vila Maria, and Mandaqui, with a population exceeding 1 million within a 10-km radius per IBGE data. Visitor demographics skew toward families and young professionals, aged 25-54, with household incomes averaging BRL 5,000-10,000 monthly, favoring value-driven retail. Daily footfall averages 80,000, supported by the malls role as a regional landmark, though seasonal fluctuations occur with peaks during holidays. This profile drives steady traffic but exposes tenants to sensitivity from economic downturns affecting discretionary spending in São Paulo's diverse market.
Competition and Market Saturation
Shopping Center Norte competes with nearby malls like Norte Shopping (GLA 120,000 m²) and Plaza Norte, both drawing similar demographics within 5-10 km, leading to potential overlap in fashion and dining categories. Broader São Paulo retail landscape includes dominant centers like Iguatemi and JK Iguatemi in wealthier zones, intensifying pressure on mid-tier positioning. Market reports from Cushman & Wakefield indicate 2025 retail vacancy in malls at 8-10%, lower than street retail's 80%, but saturation in apparel (40% of tenant mix) poses risks for new entrants. Strengths include superior sales per m², yet tenants must differentiate to counter e-commerce growth and post-pandemic shifts reducing impulse buys by 15% per Abrasce insights.
Accessibility and Operational Quality
Prime location adjacent to Marginal Tietê provides excellent highway access for vehicular traffic, complemented by metro and bus connections via nearby Santana station, facilitating reach from central São Paulo in 20-30 minutes. The single-floor design enhances navigability, earning recognition as one of the most accessible malls, with 7,000 parking spots at BRL 15-20 per hour. Operational quality is high, with recent 2023 expansion improving flow and adding modern amenities, though aging infrastructure from 1984 origins requires ongoing maintenance investments. Challenges include peak-hour congestion on access roads and high operational costs in a flood-prone riverside area, per local environmental reports, potentially impacting logistics and customer experience during rainy seasons.
Building Details
Detailed Market Analytics
City Snapshot
São Paulo, SP
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in São Paulo
Discover more shopping centers in São Paulo.

Popular in Brazil
Top retail destinations across Brazil.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
São Paulo, SP
Comprehensive market intelligence for retail expansion in this city