

Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
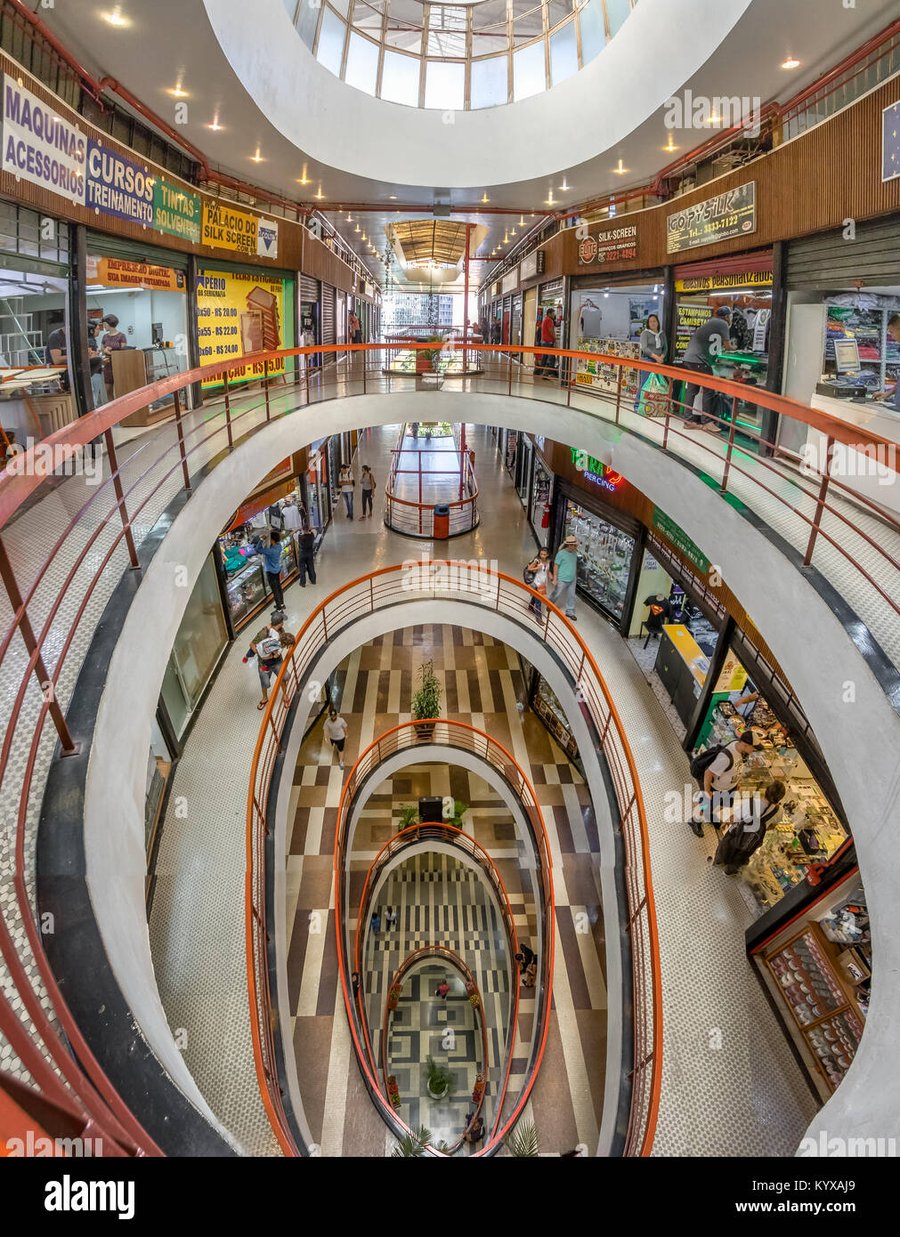
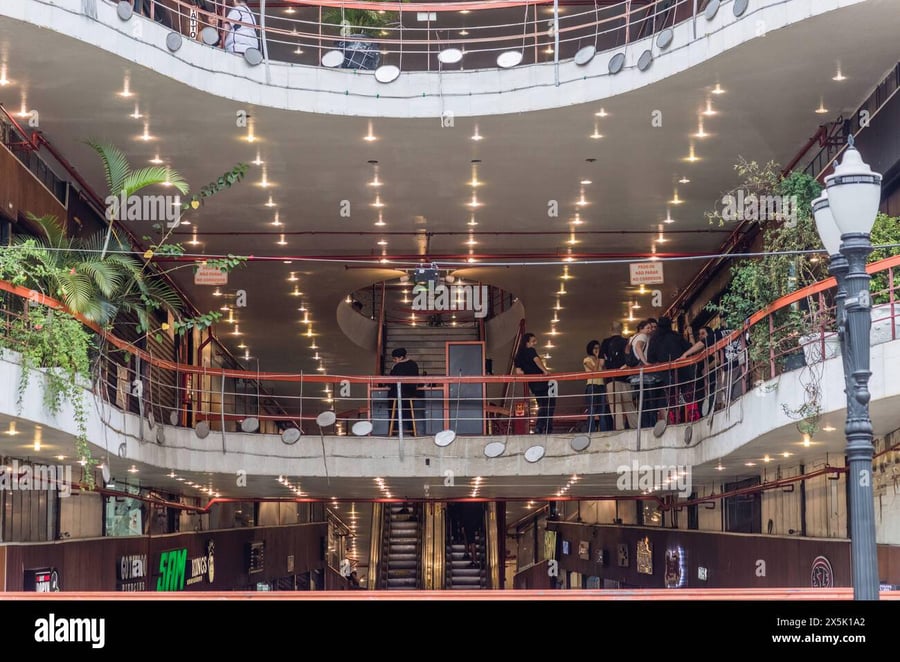
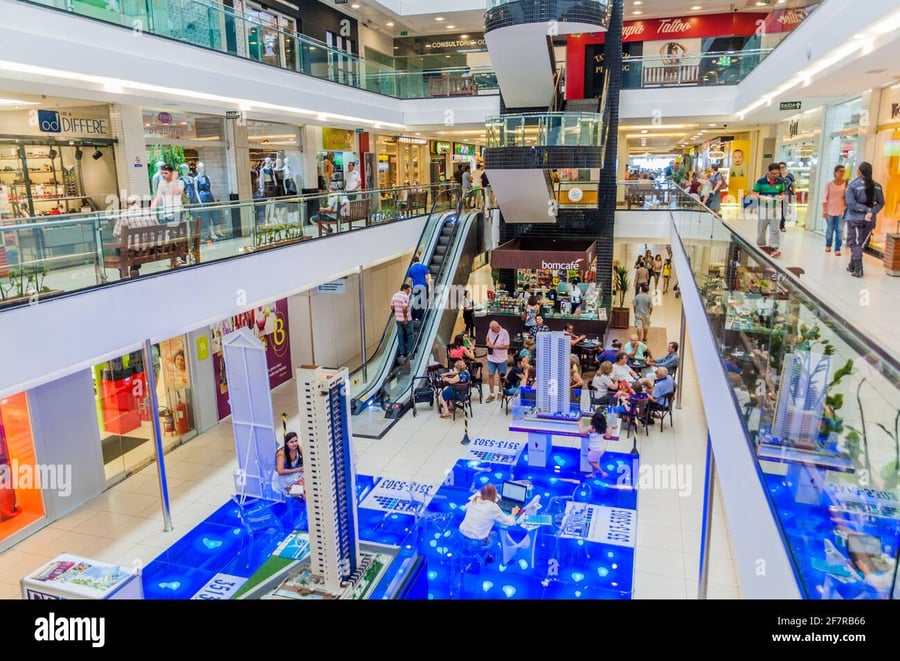
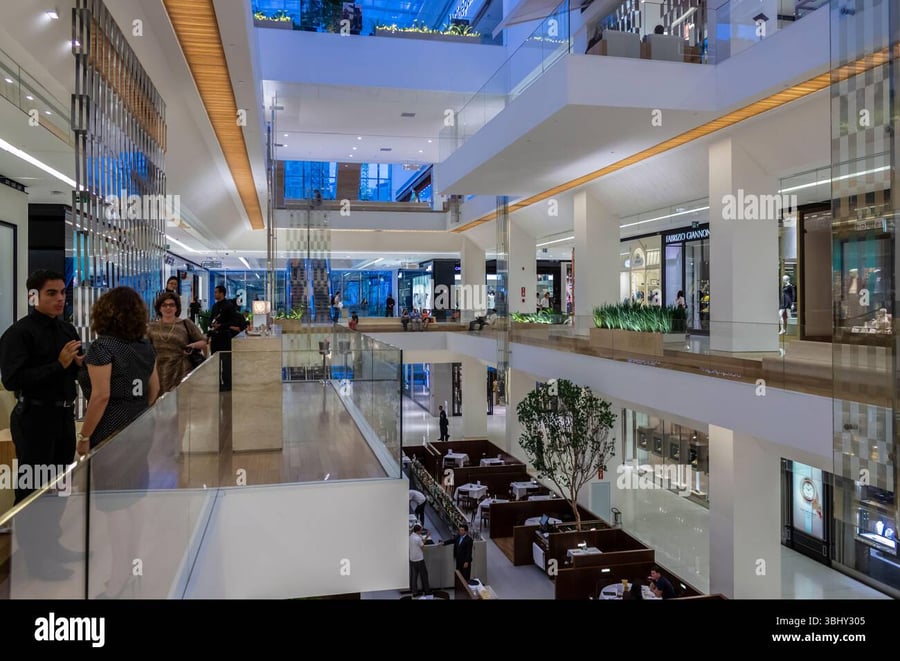
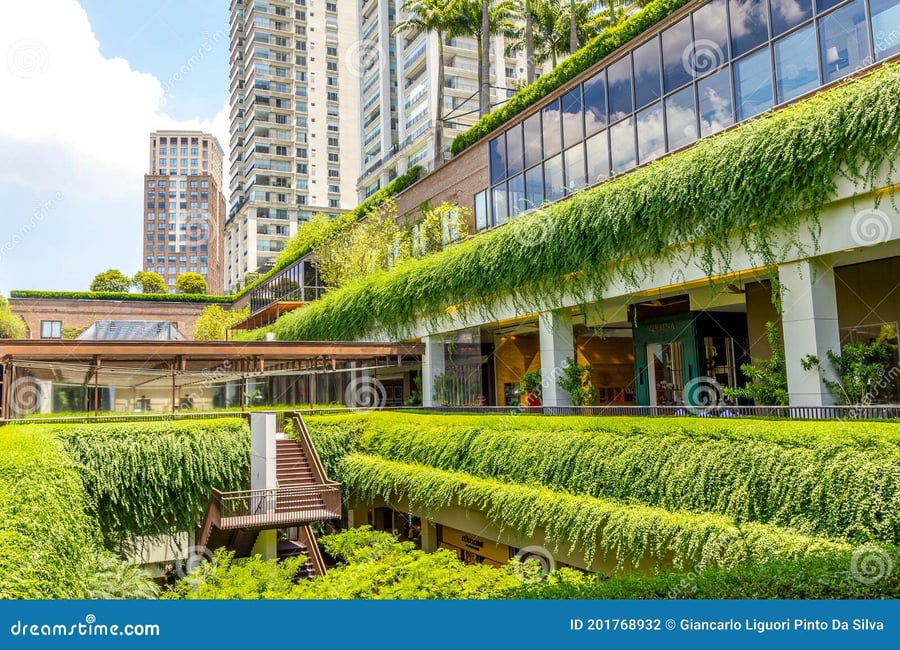
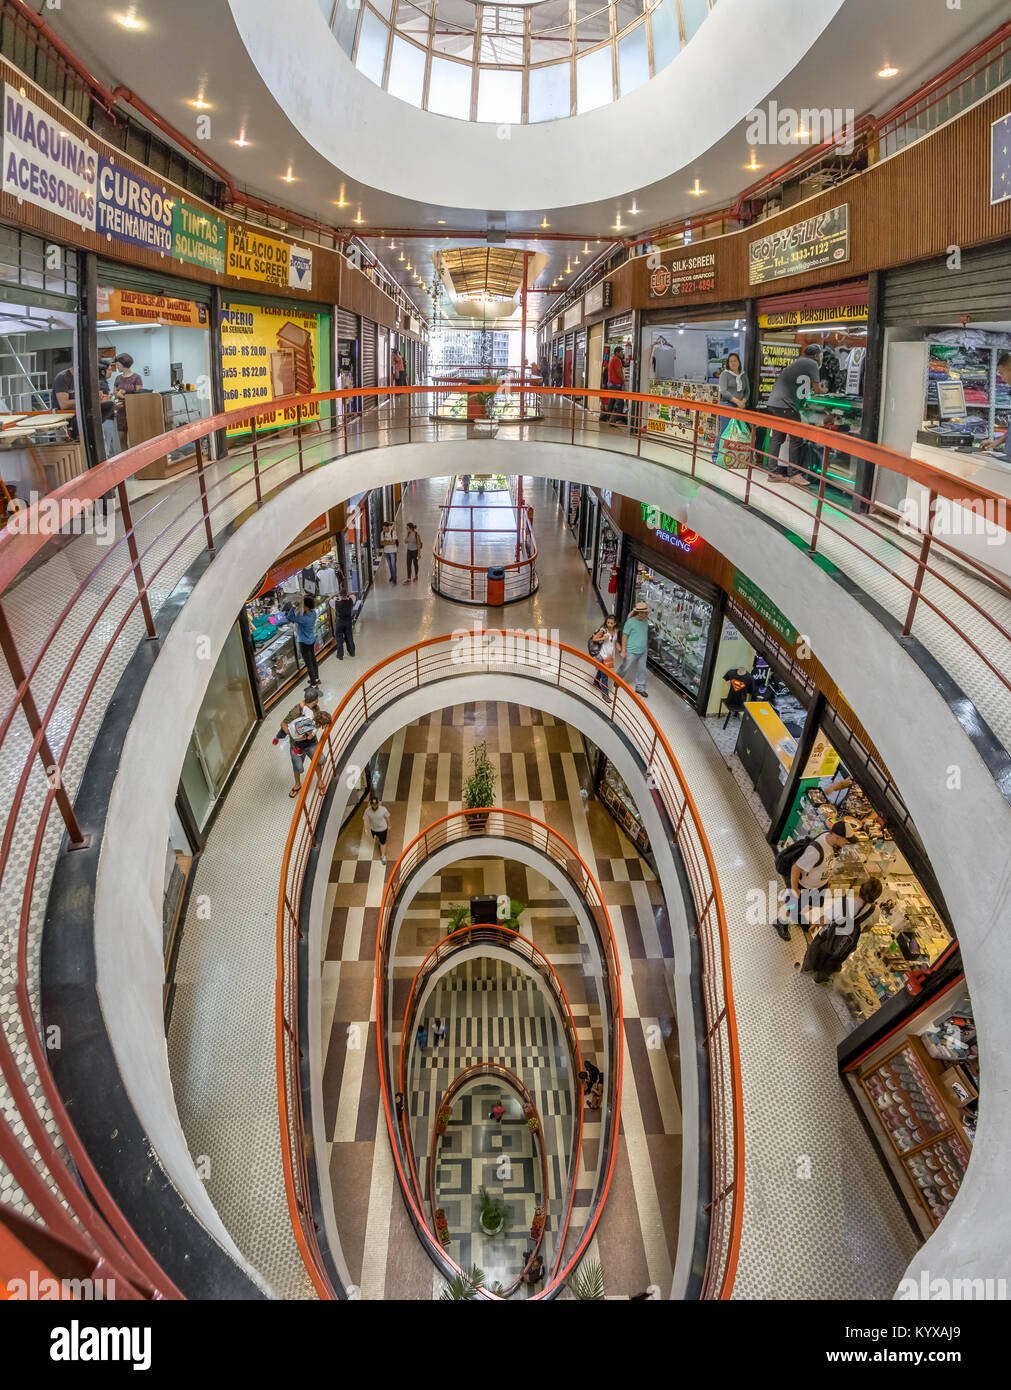
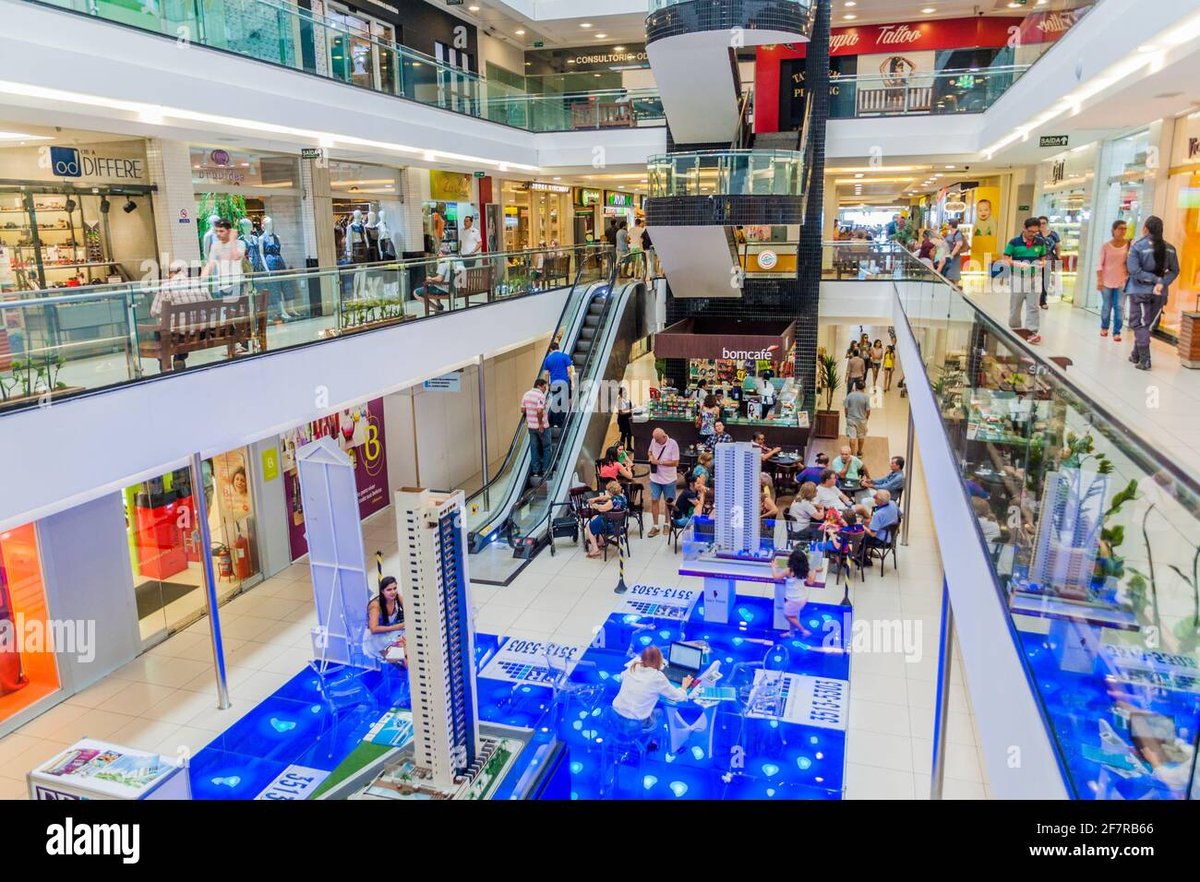
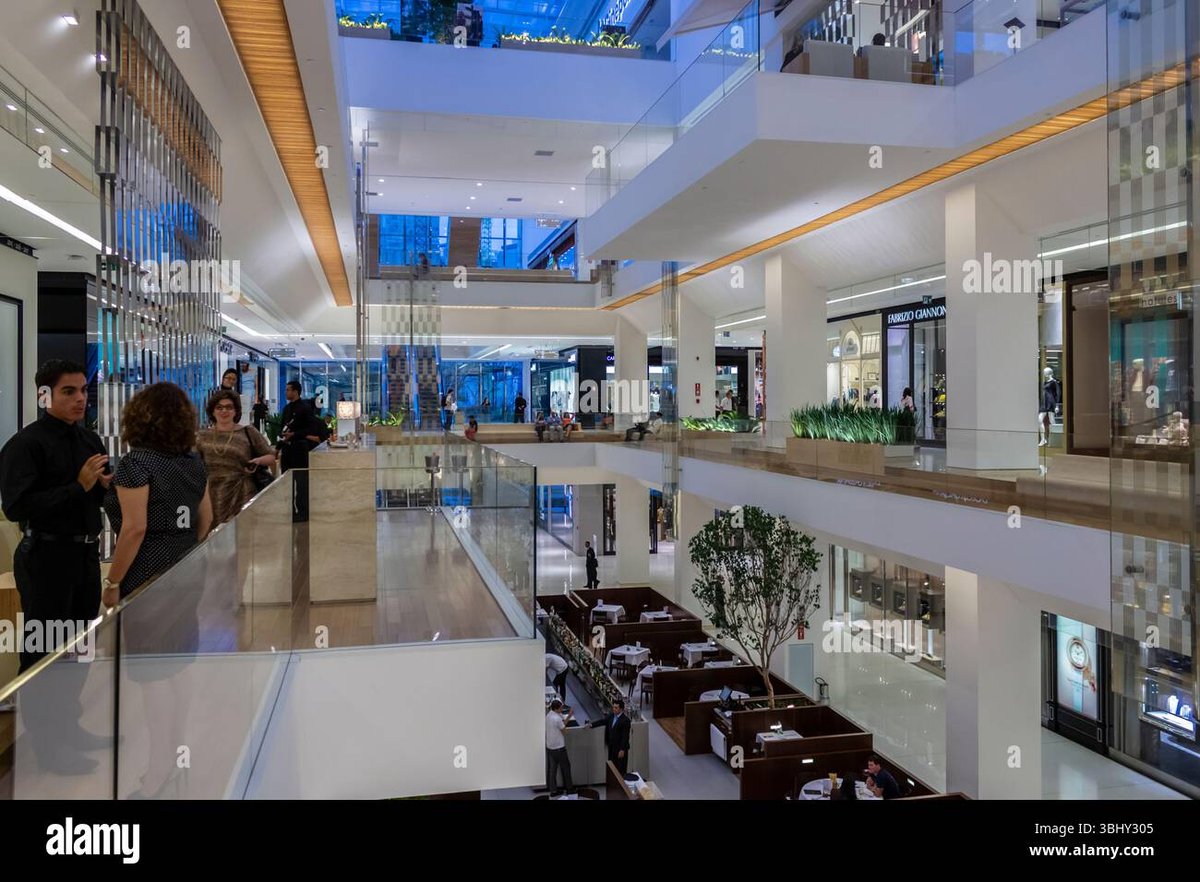
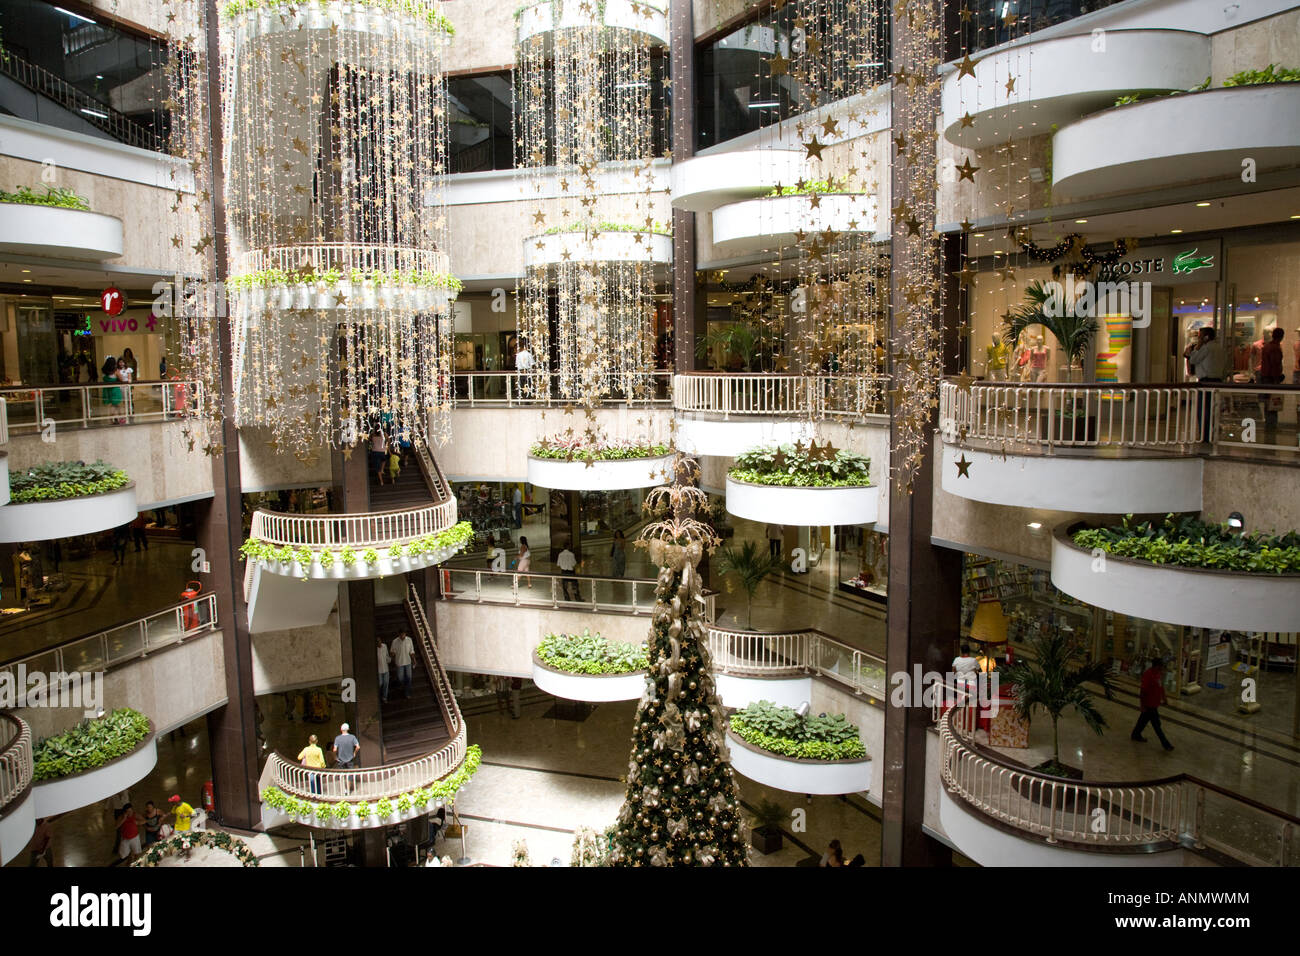
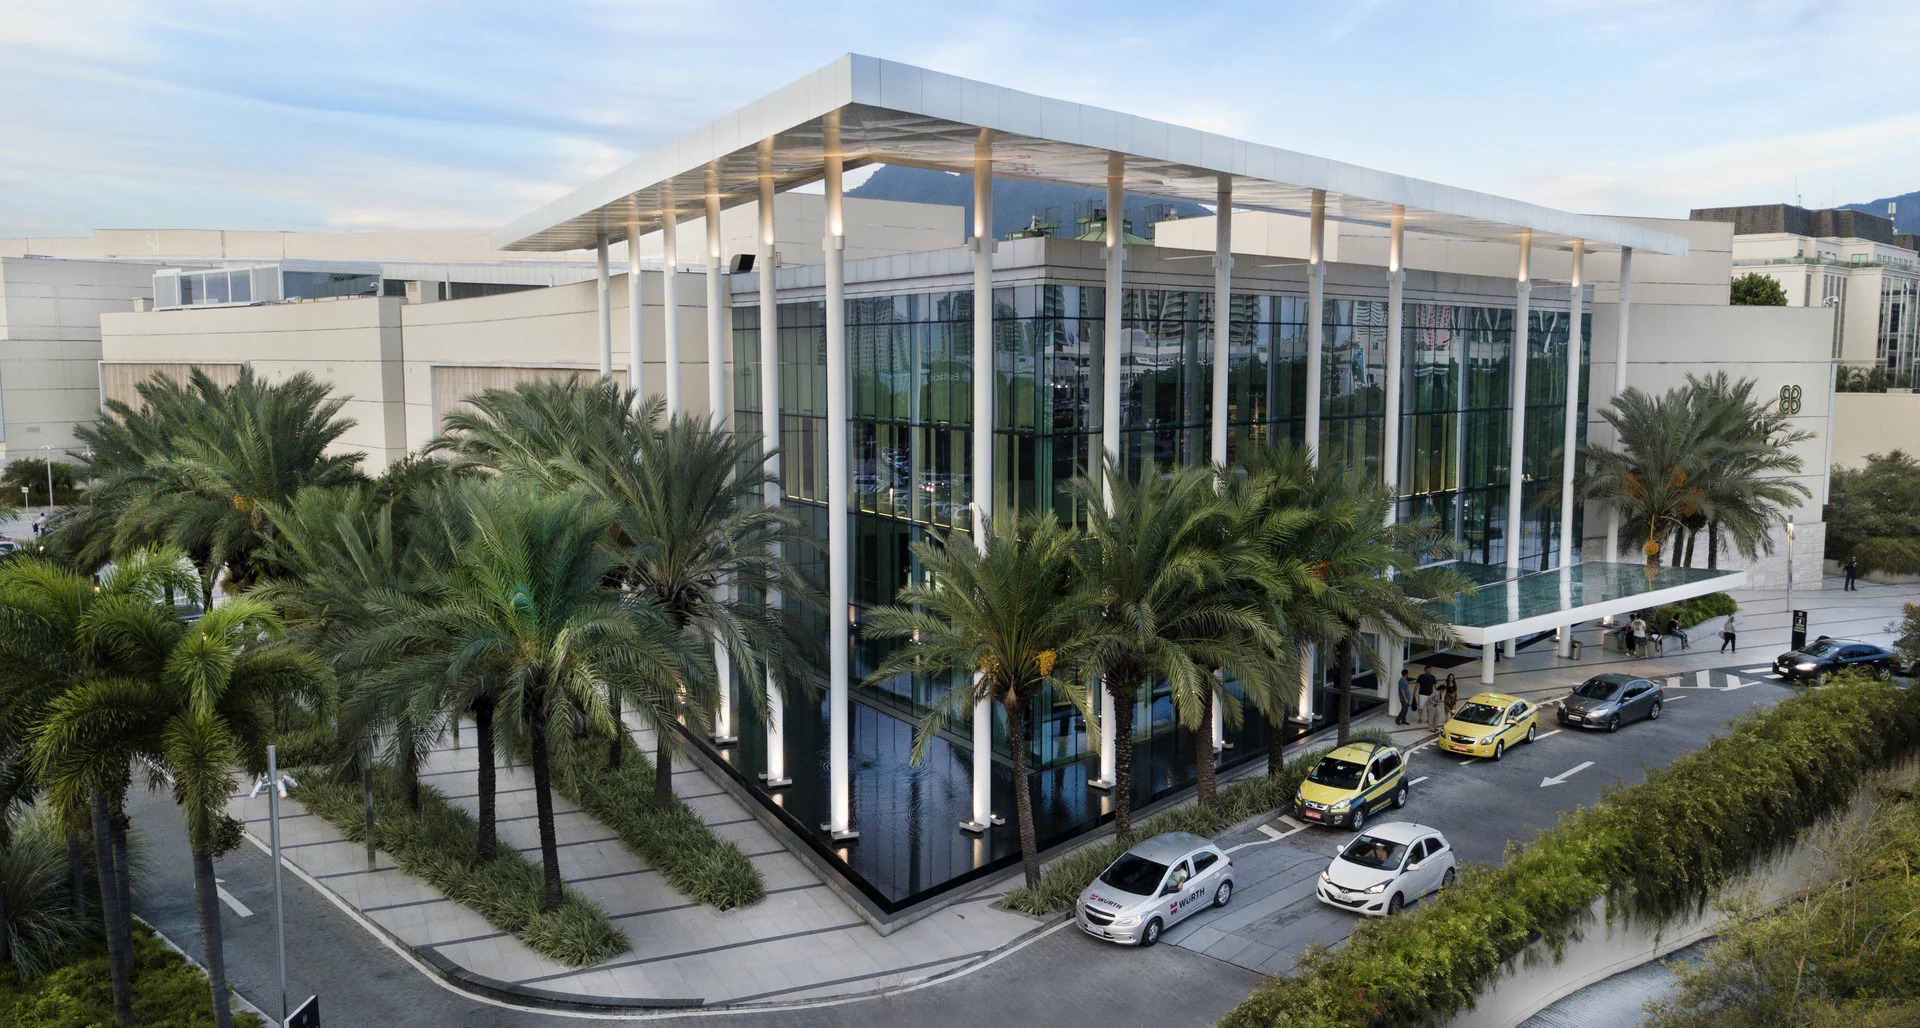
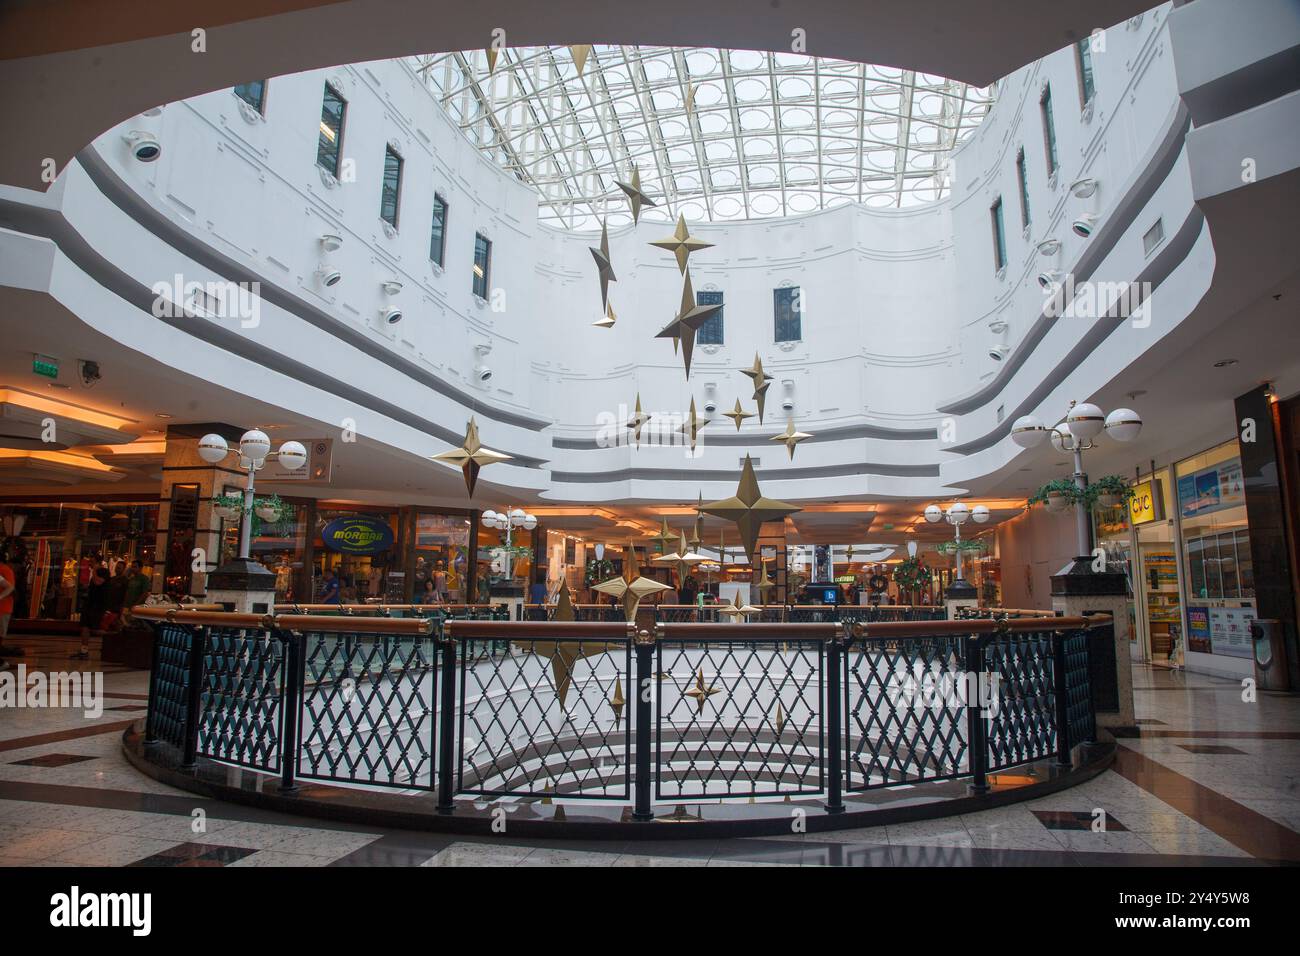
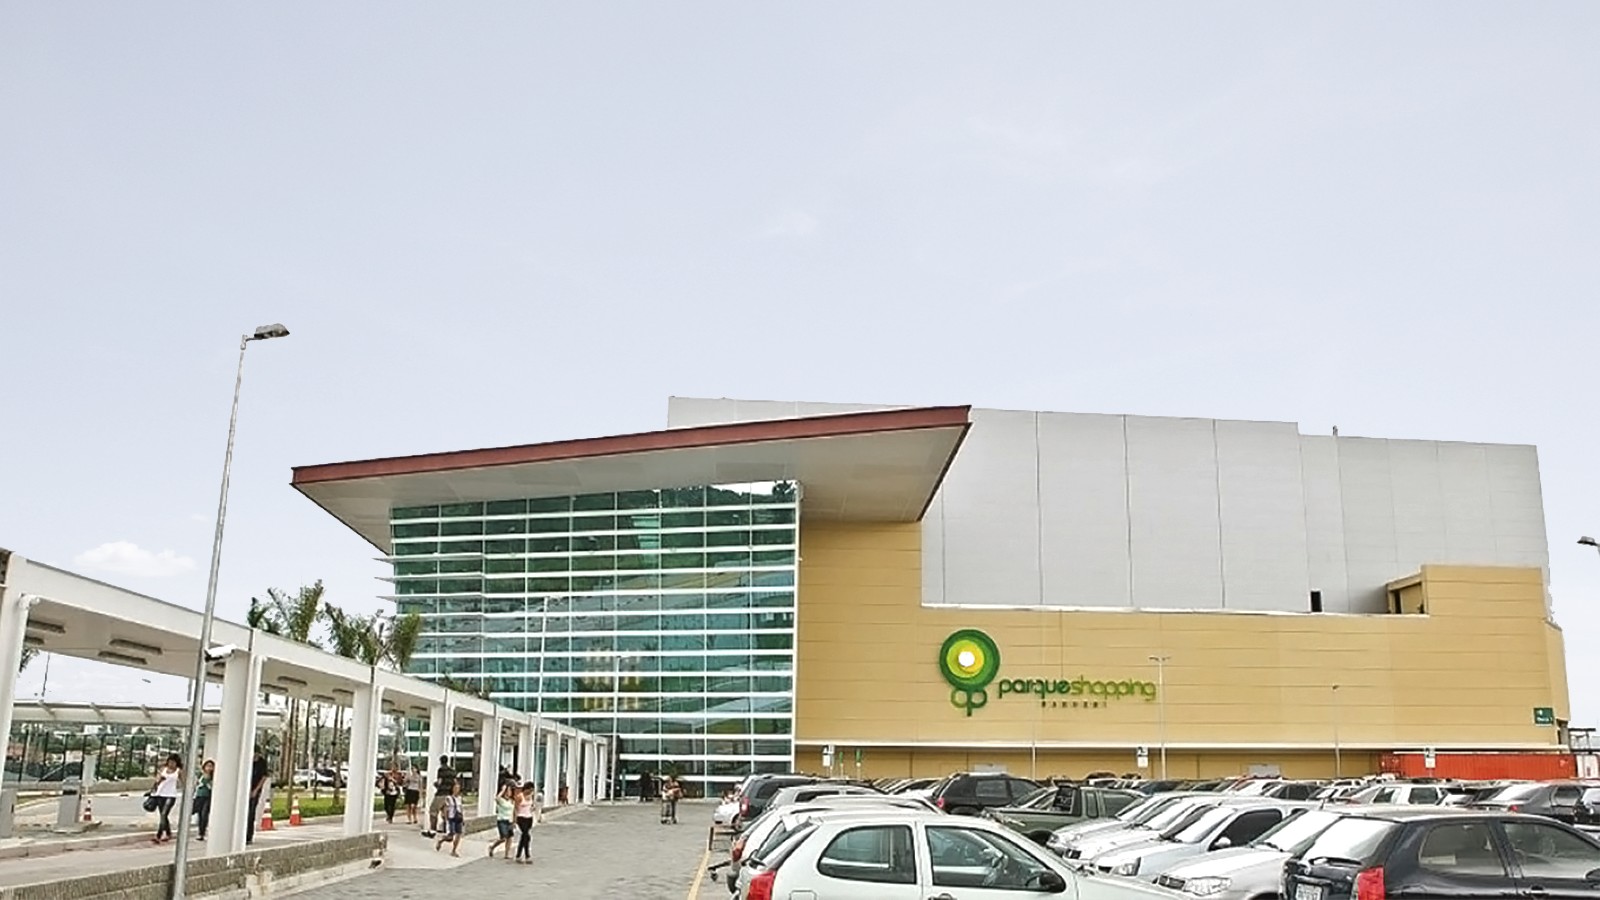
Central Plaza Shopping is located in Vila Prudente, eastern São Paulo, at Av. Dr. Francisco Mesquita, 1000. This modern neighborhood mall, opened around 2010, features an estimated GLA of 40,000 square meters with 240 stores distributed over three levels. The tenant mix is diverse, anchored by a hypermarket (such as Extra or similar), complemented by fashion outlets like Renner, C&A, and Hering; electronics from Fast Shop; beauty brands including O Boticário and Natura; over 30 F&B options ranging from McDonald"s and Burger King to casual eateries like Outback; entertainment via Cinemark cinema with multiple screens and a gym; plus services like banks and telecoms.
Occupancy hovers at 95%, consistent with São Paulo"s retail market where 2024 reports show 96% average occupancy and 3.2% sales growth year-over-year, supported by 2.5% regional GDP expansion and unemployment below 8%. The property serves a primary catchment of 500,000 residents within 5-10 km, mainly middle-class B2 households with average monthly incomes of BRL 5,000-8,000, drawn from residential areas, nearby universities, and industrial zones.
Accessibility benefits from the Tamanduateí metro station (Line 2-Green, 200 meters away), multiple bus lines, and 1,200 covered parking spots, facilitating 70% local and 30% regional traffic. However, congestion on surrounding avenues like Av. Radial Leste during peaks hampers impulse visits. In the competitive São Paulo landscape with over 100 malls, Central Plaza holds a solid local position, leveraging post-pandemic recovery and family-oriented programming, but contends with e-commerce"s 20% market share and rivals like Mooca Plaza Shopping (15 km north) and Shopping Ipiranga (5 km south), which offer similar mixes.
Leasing advantages include moderate rents of BRL 100-150 per sqm monthly plus 8-10% sales turnover, high footfall of approximately 1.8 million annually, and growth potential in leisure and services categories amid market stabilization. Drawbacks involve moderate infrastructure aging requiring capex, fashion category saturation risking 5-8% vacancies, and sensitivity to inflation (projected 4.5% in 2025) curbing discretionary spend, per Abrasce and CBRE insights.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 02:00 PM — 08:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment Area
Vila Prudente neighborhood and east zone environs encompass over 400,000 potential customers within a 5 km radius, featuring middle-income B2 demographics with family-oriented households and average incomes of BRL 6,000 monthly. Proximity to educational institutions like Universidade São Judas Tadeu and growing residential developments bolster consistent demand for convenience retail. São Paulo"s retail sector shows 2.9% footfall increase in 2024 per market data, yet Central Plaza"s local focus limits broader appeal compared to city-center destinations. Challenges include income disparities in the area, with 20% lower-income segments preferring discount formats, and rising e-commerce adoption (18% penetration) diverting 10-15% of sales from physical stores, as noted in regional reports.
Tenant Mix and Occupancy
Balanced tenant composition allocates 35% to anchors (hypermarket, cinema), 25% fashion/accessories, 20% F&B, 10% services, and 10% entertainment/leisure, promoting cross-traffic but exposing weaknesses in premium brands that could attract higher spenders. High occupancy of 95% indicates effective management and tenant retention, with modernized interiors, loyalty programs, and promotional events sustaining operational quality. Average sales per sqm reach BRL 9,000 annually, aligning with neighborhood benchmarks but trailing upscale malls" BRL 14,000. Risks involve 6% vacancy potential in oversaturated apparel segments and internal F&B competition eroding margins for smaller operators, per commercial real estate analyses.
Accessibility, Competition, and Lease Terms
Strong connectivity via metro (Tamanduateí station), buses, and parking supports efficient access, with 60% visitors arriving by public transport, though traffic bottlenecks on key roads reduce convenience during rush hours. Lease structures feature 3-5 year terms at BRL 120/sqm base rent plus 9% turnover, offering value for mid-tier retailers in a market with 4% rent growth. Competition from proximate centers like Anália Franco (larger GLA, 3 million footfall) and online platforms pressures performance, potentially capturing 12% of trade area traffic. Additional risks include infrastructure maintenance needs for the decade-old facility and macroeconomic factors like 4.5% inflation impacting consumer budgets, positioning it as a stable but cautious leasing opportunity.
Building Details
Detailed Market Analytics
City Snapshot
São Paulo, SP
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in São Paulo
Discover more shopping centers in São Paulo.

Popular in Brazil
Top retail destinations across Brazil.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
São Paulo, SP
Comprehensive market intelligence for retail expansion in this city