Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
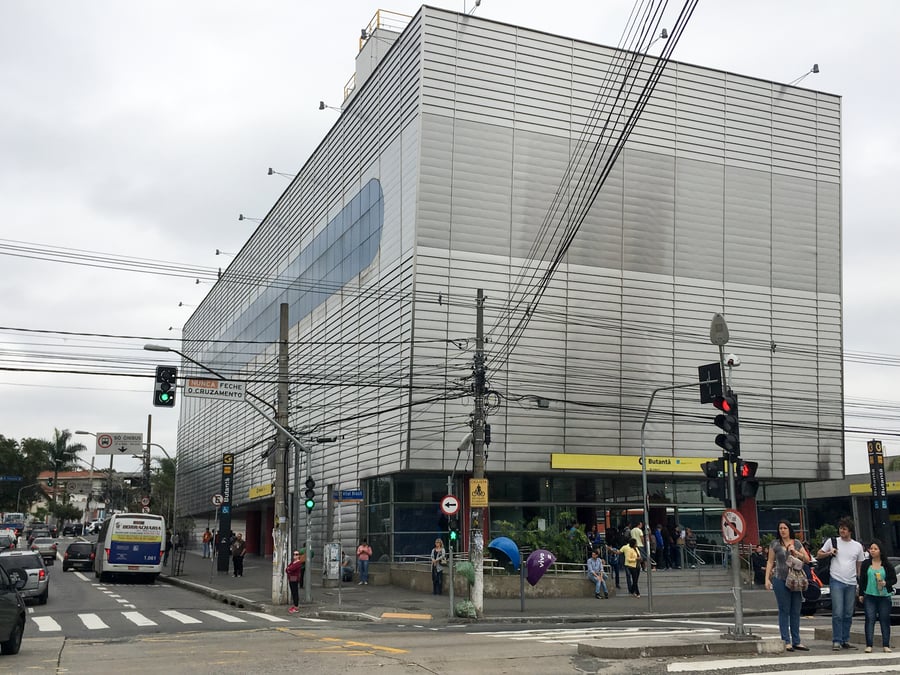
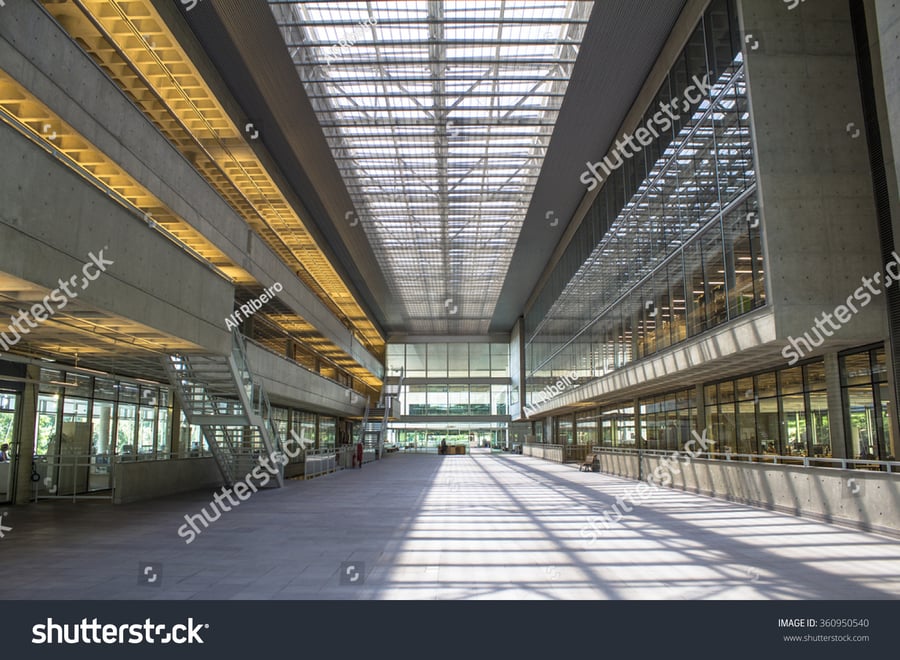
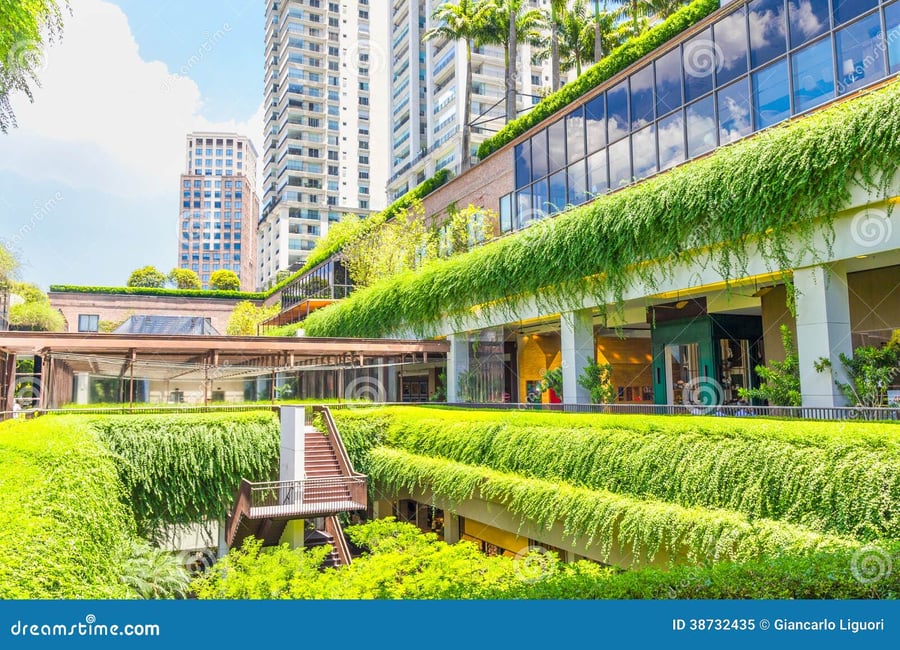
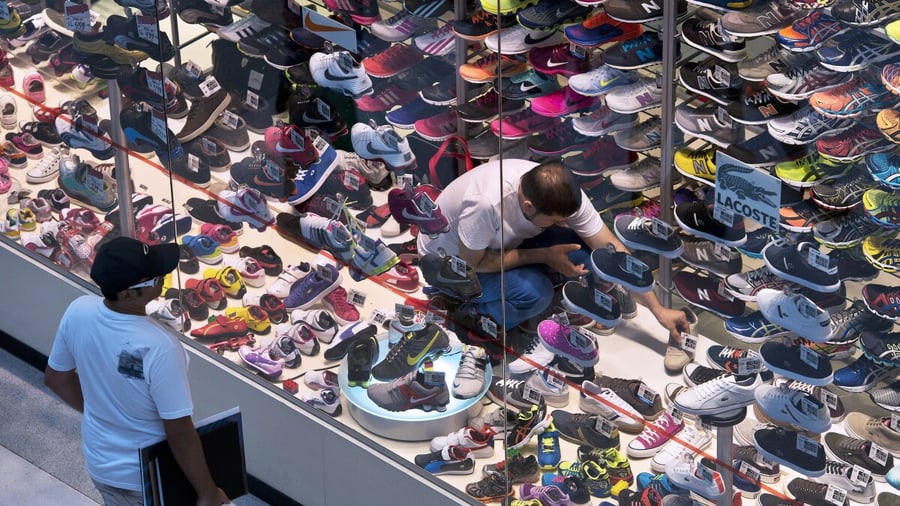
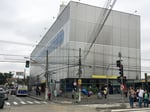
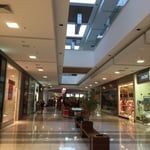
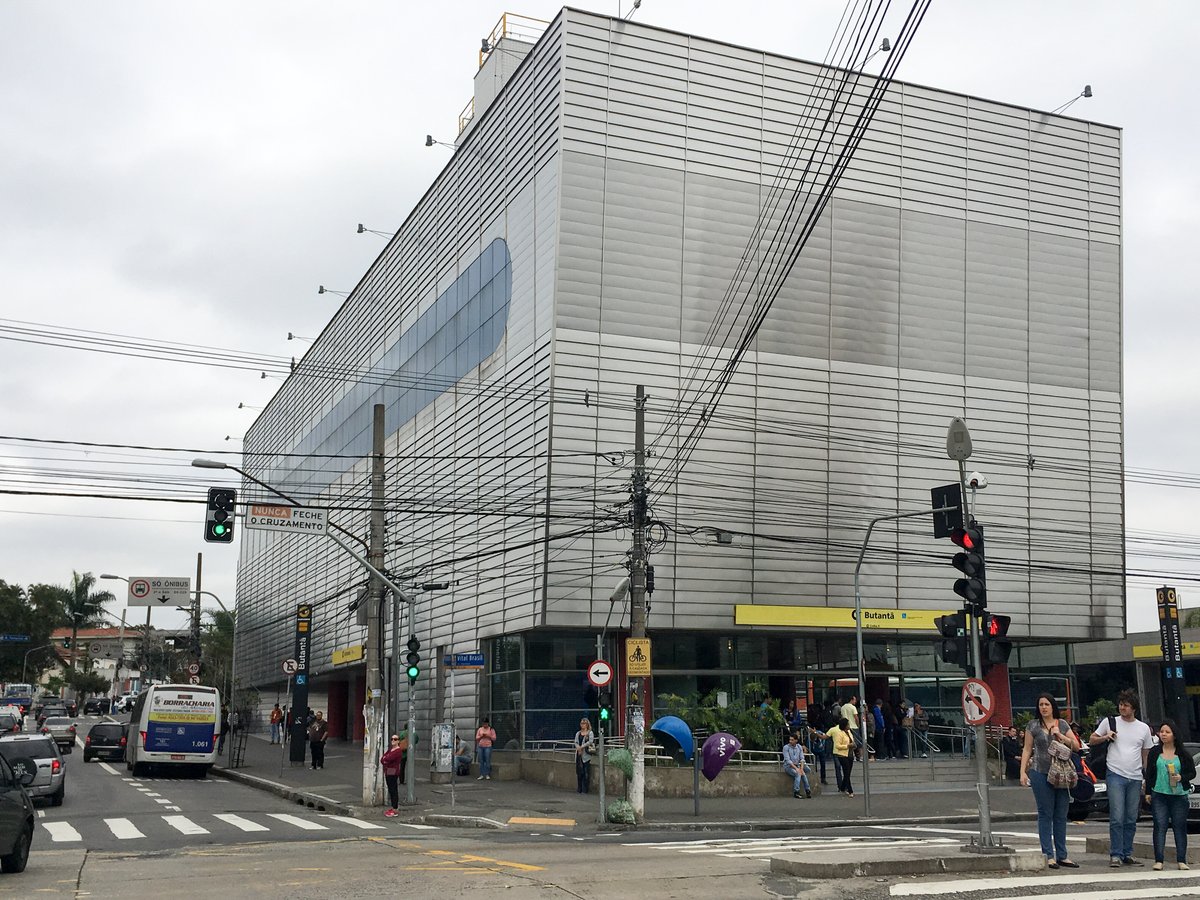
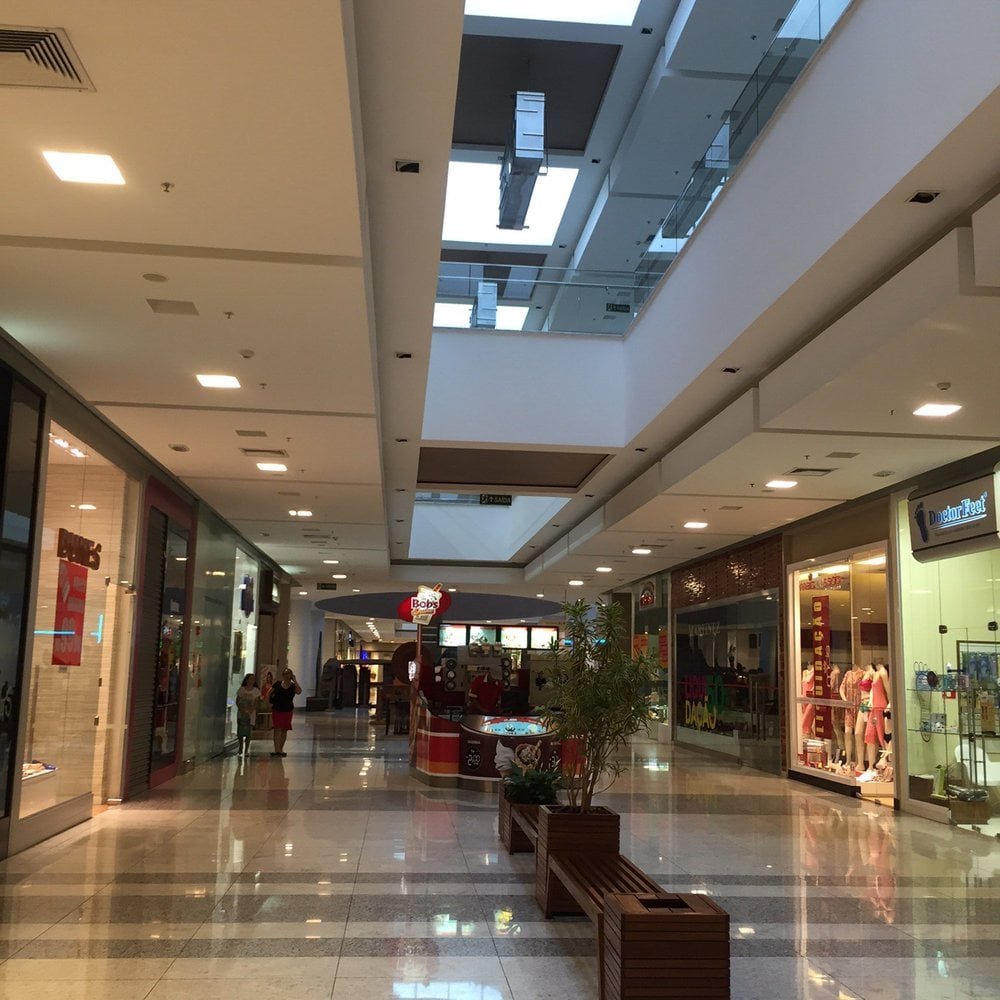
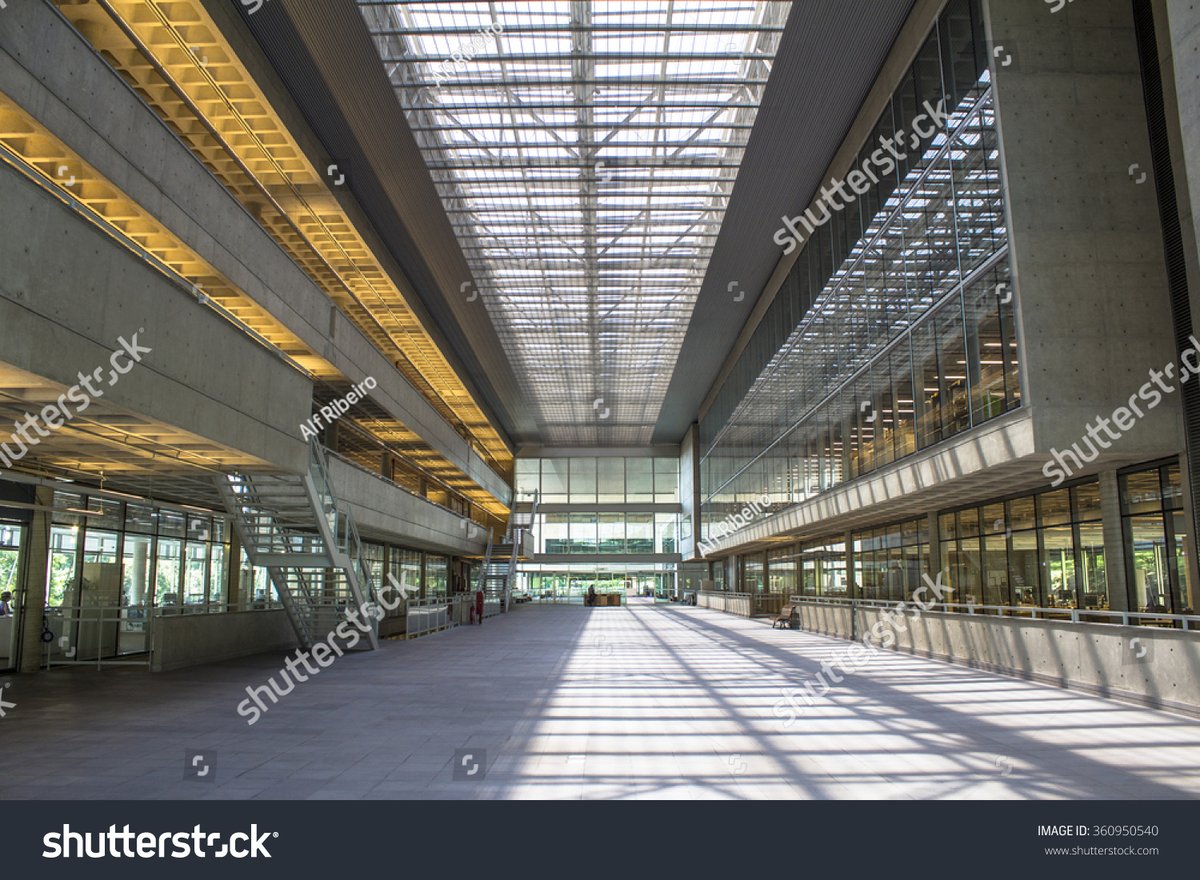
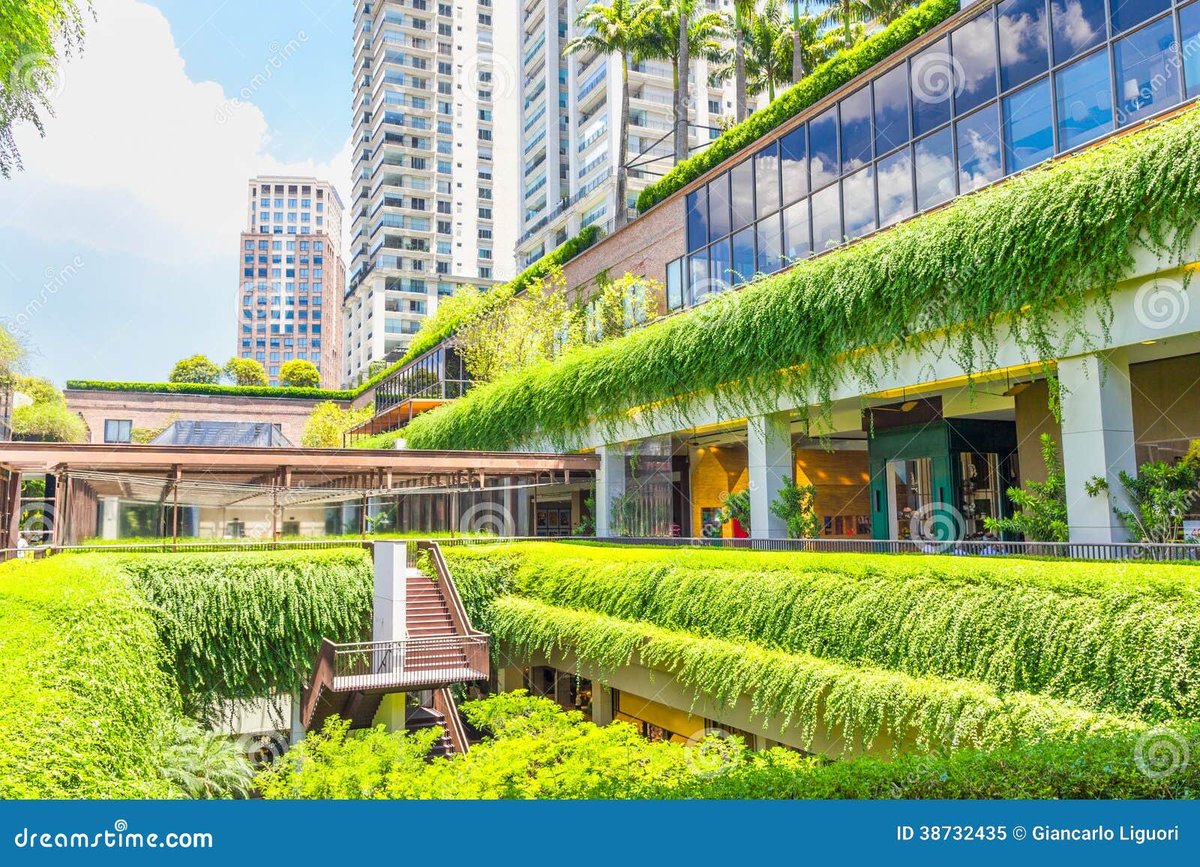
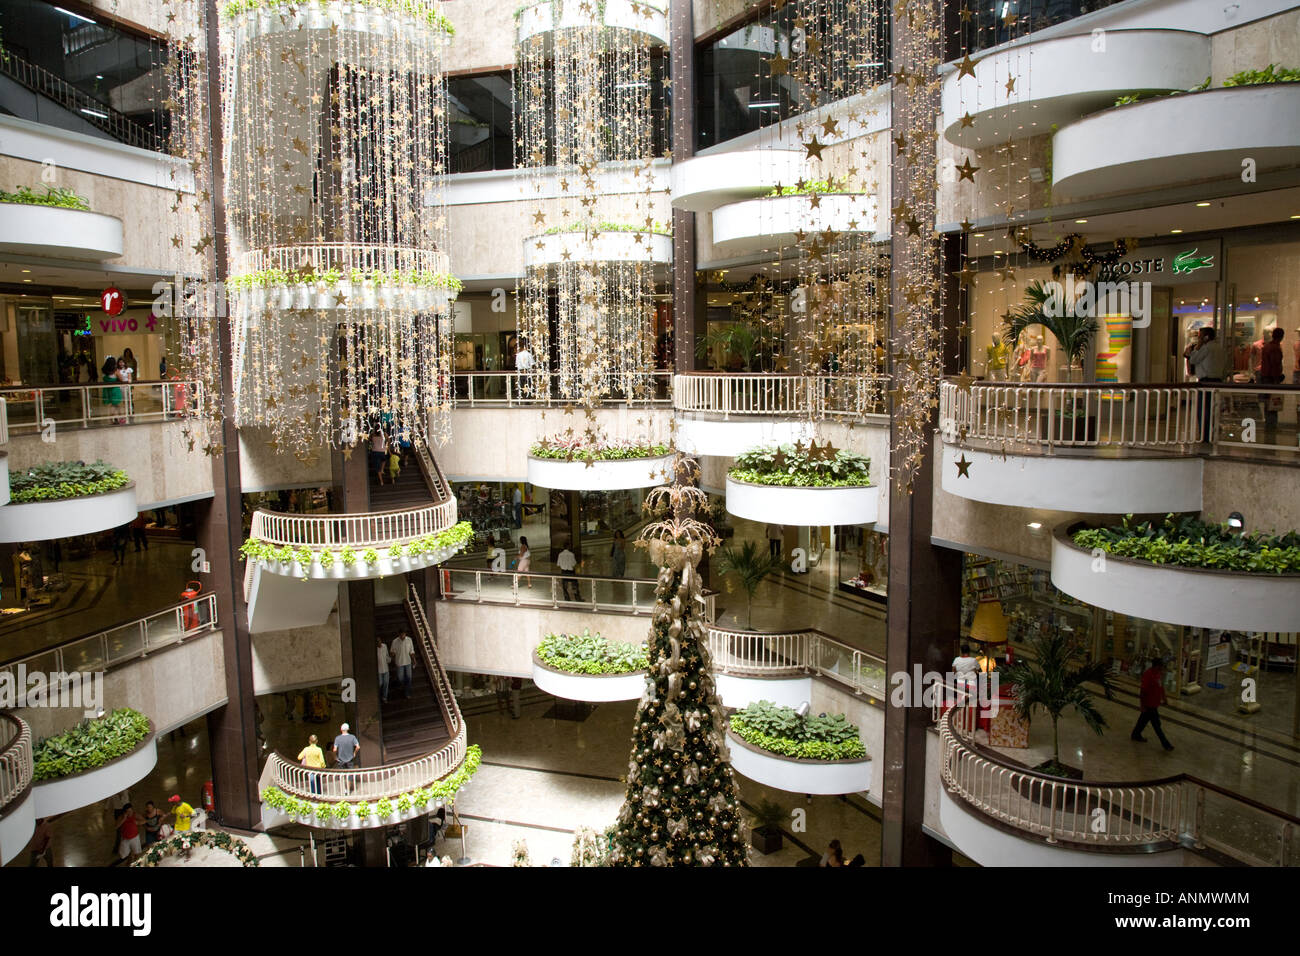
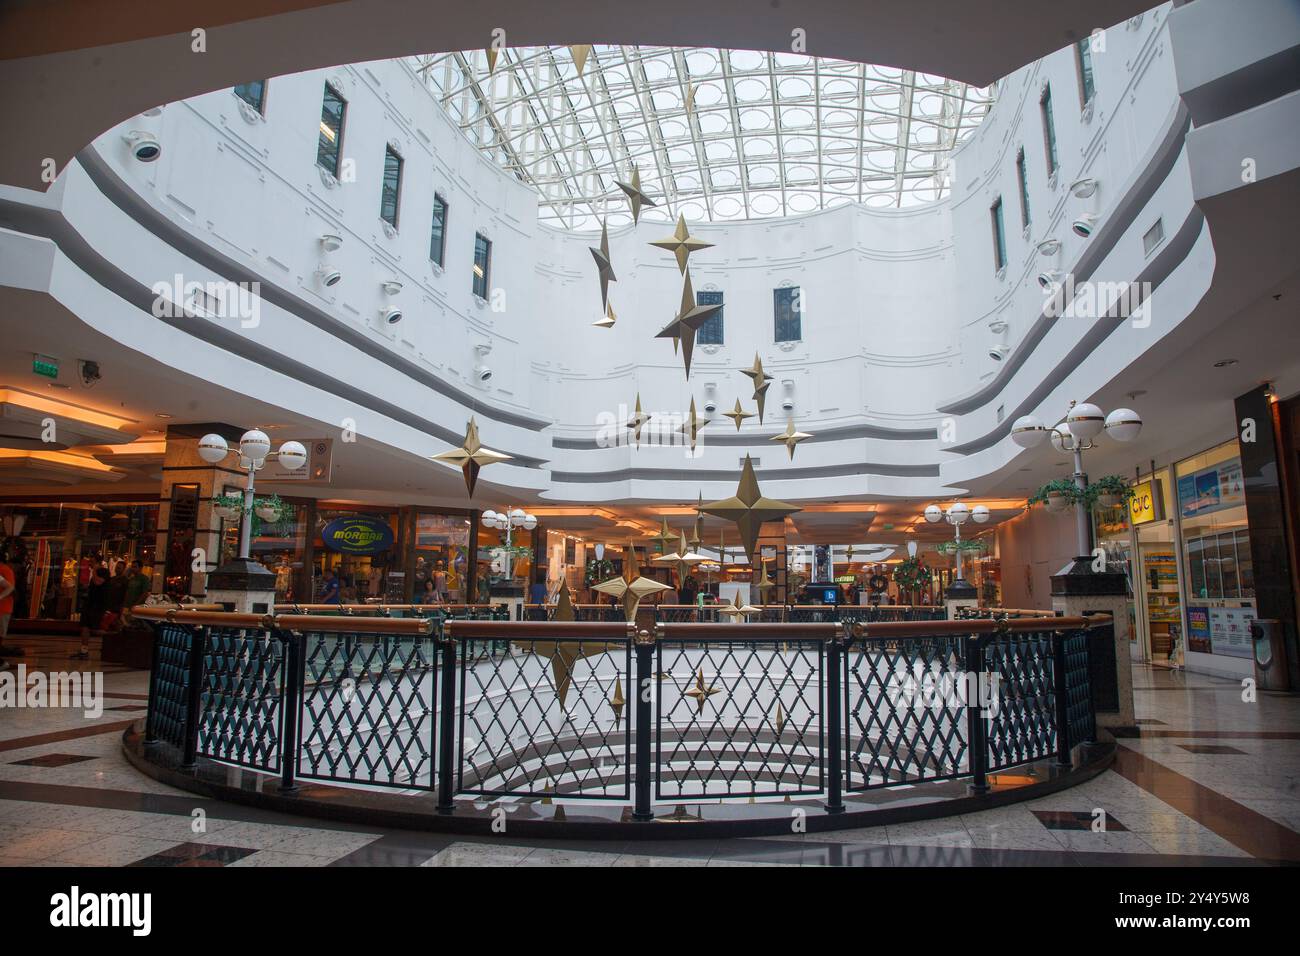
Butantã Shopping, located at Av. Prof. Francisco Morato, 2718, in the Butantã neighborhood of western São Paulo, Brazil, opened in 1994 and spans 118,000 square meters of built area with approximately 30,000 square meters of gross leasable area across three floors. Managed by Carrefour Property, it features over 160 stores, including anchor tenants such as the Carrefour hypermarket, Renner department store, Lojas Americanas, Daiso variety store, Preçolândia electronics, and Smart Fit gym.
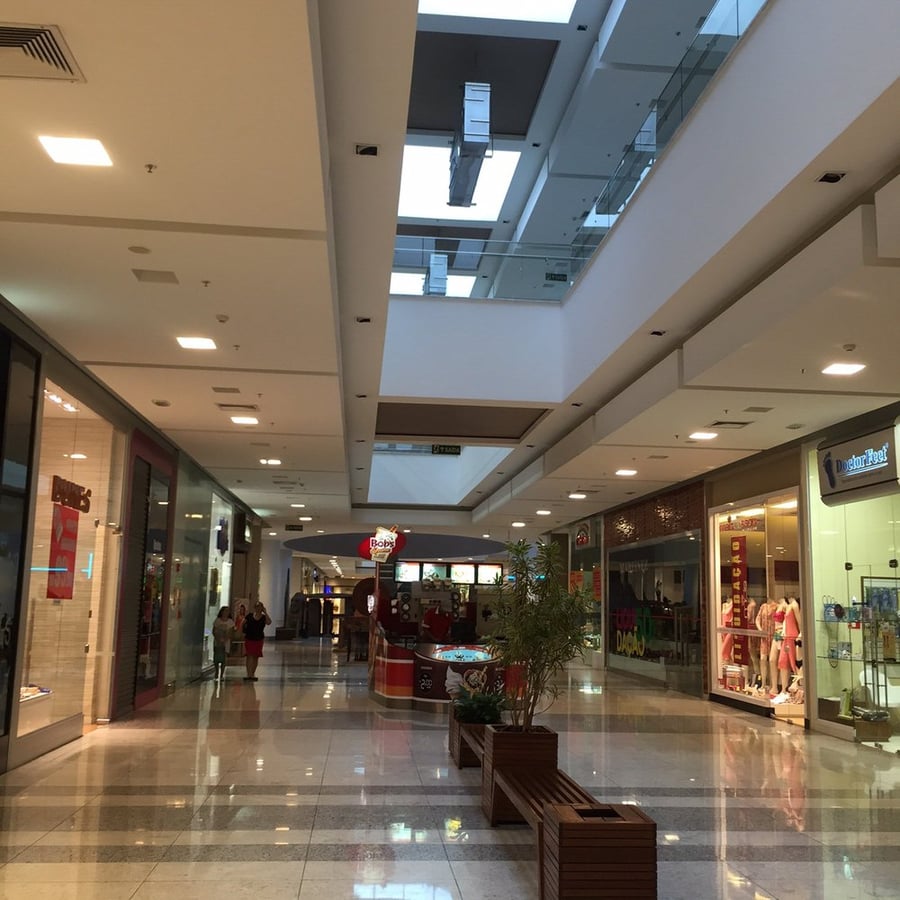
The tenant mix emphasizes everyday retail, fashion, and services, with a food court offering 454 seats and 25 kiosks for quick-service options.
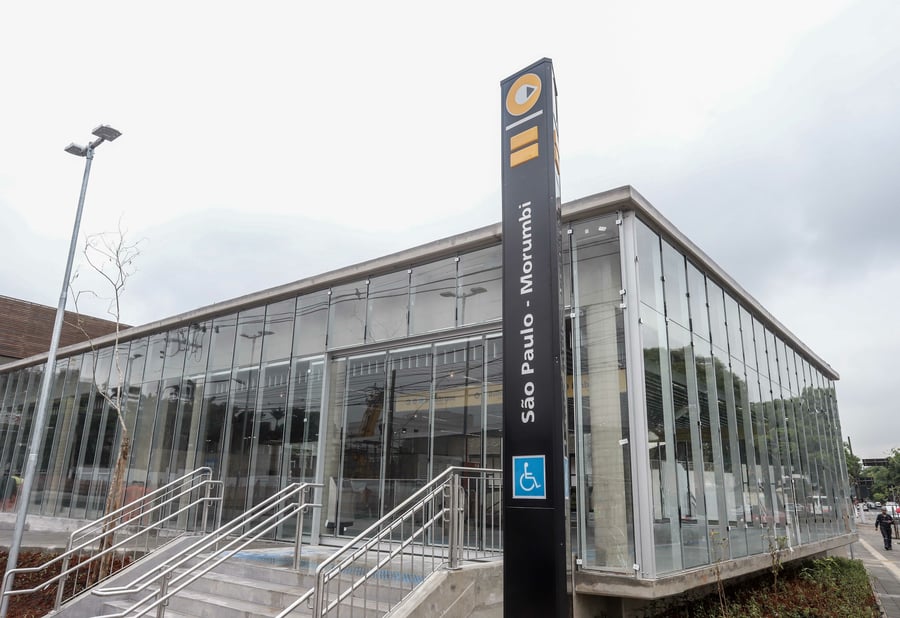
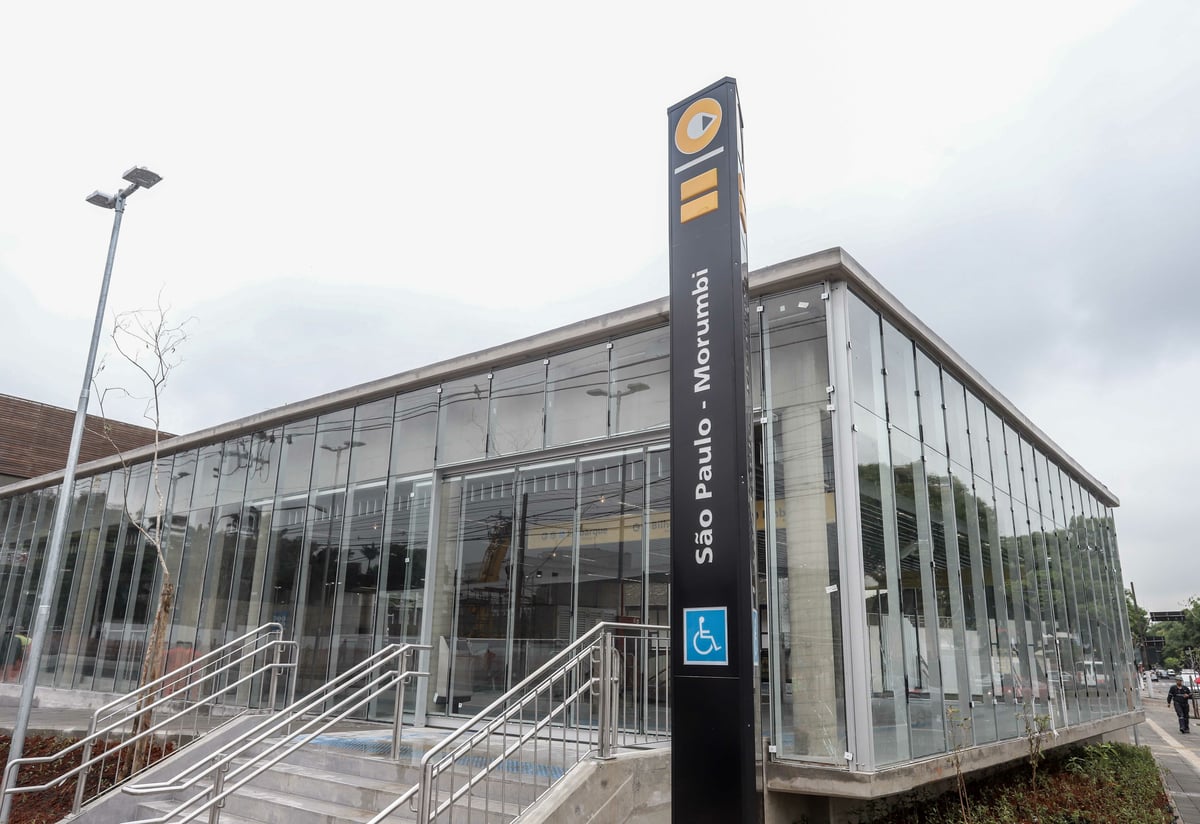
Accessibility is a key strength, with direct proximity to the São Paulo-Morumbi metro station on Line 4-Yellow, facilitating public transit use, alongside major roads like Av. Prof. Francisco Morato and ample parking for 1,852 vehicles, including covered and accessible spots. Annual footfall reaches 9.6 million visitors, averaging 800,000 monthly, driven by local residential draw. In the competitive São Paulo retail market, it positions as a neighborhood center serving middle-income demographics in Butantã, Vila Sônia, and Morumbi districts, where population density supports consistent traffic but faces saturation from nearby upscale venues like Morumbi Shopping.
Occupancy rates align with city averages around 90-95%, per general commercial real estate reports from sources like Cushman & Wakefield, with rent levels for mid-tier spaces estimated at R$120-160 per square meter monthly, influenced by anchor pull and location.
Leasing advantages include stable traffic from metro integration and Carrefour synergy for grocery-driven visits, though challenges involve moderate sales per square meter (around R$2,500-3,500 annually, based on regional benchmarks) amid economic pressures on consumer spending.
Operational quality is solid with extended hours and free Wi-Fi, but aging infrastructure from 1990s build may require updates to compete with modernized peers.
Overall, it offers practical leasing for retailers targeting everyday essentials in a transit-oriented, community-focused setting, balanced against regional competition and urban density factors.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 02:00 PM — 08:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Footfall
The Butantã area features a middle-class demographic with a mix of families, young professionals, and students from nearby University of São Paulo (USP), estimating a catchment population of over 500,000 within 5 km radius, per urban planning data. Household incomes average R$4,000-6,000 monthly, supporting value-oriented retail. Footfall of 9.6 million annually reflects steady local patronage, bolstered by metro access reducing reliance on car traffic, though seasonal dips occur during university breaks. This profile suits mid-market tenants but limits luxury appeal compared to higher-income zones like Morumbi.
Competition and Market Position
Butantã Shopping operates in a saturated west São Paulo market, competing with larger centers like Morumbi Shopping (GLA 110,000 m², upscale mix, 20 million annual visitors) and Shopping Eldorado (GLA 120,000 m², strong fashion focus). Its neighborhood positioning emphasizes convenience over destination appeal, with tenant mix skewed toward essentials (40% grocery/services, 30% fashion, 20% food/entertainment per typical Carrefour portfolio). Market reports indicate moderate growth in regional retail, but e-commerce and economic volatility pose risks, potentially capping sales at 10-15% below city averages. Strengths lie in lower competition for daily needs, yet proximity to premium malls may divert discretionary spending.
Lease Terms and Risks
Lease structures typically involve minimum rents of R$120-160/m² plus 8-12% of sales turnover, aligned with São Paulo mid-tier benchmarks from ICSC and local brokerage insights. Terms favor long-term commitments (5-10 years) with Carrefour incentives like co-marketing. Risks include infrastructure aging (built 1994, potential maintenance costs), access congestion on surrounding avenues during peak hours, and category weaknesses in high-end dining or entertainment amid shifting consumer preferences toward experiential retail. Operational challenges from metro construction disruptions have historically impacted footfall, advising due diligence on renewal clauses and escalation caps tied to IGP-M inflation index.
Building Details
Detailed Market Analytics
City Snapshot
São Paulo, SP
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in São Paulo
Discover more shopping centers in São Paulo.

Popular in Brazil
Top retail destinations across Brazil.

Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
São Paulo, SP
Comprehensive market intelligence for retail expansion in this city