Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
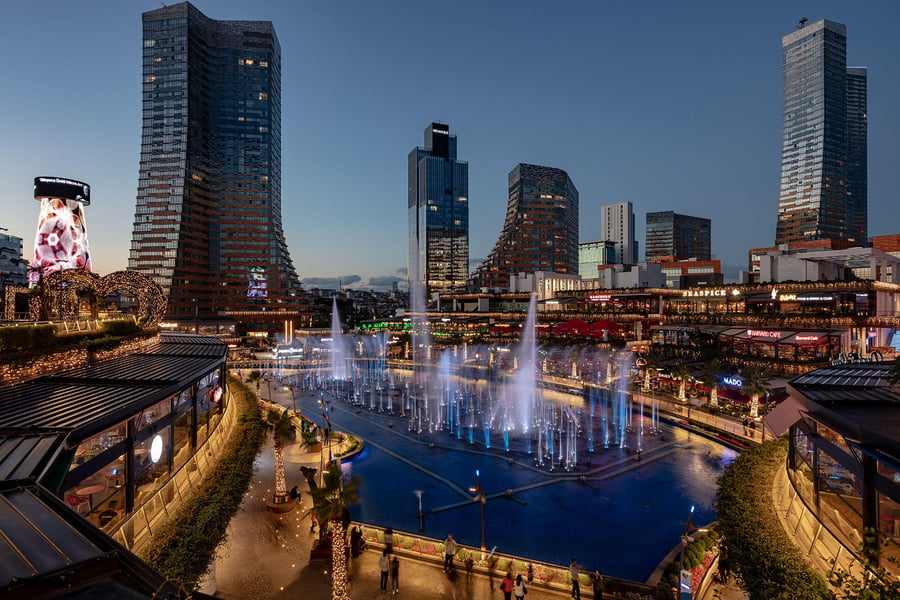
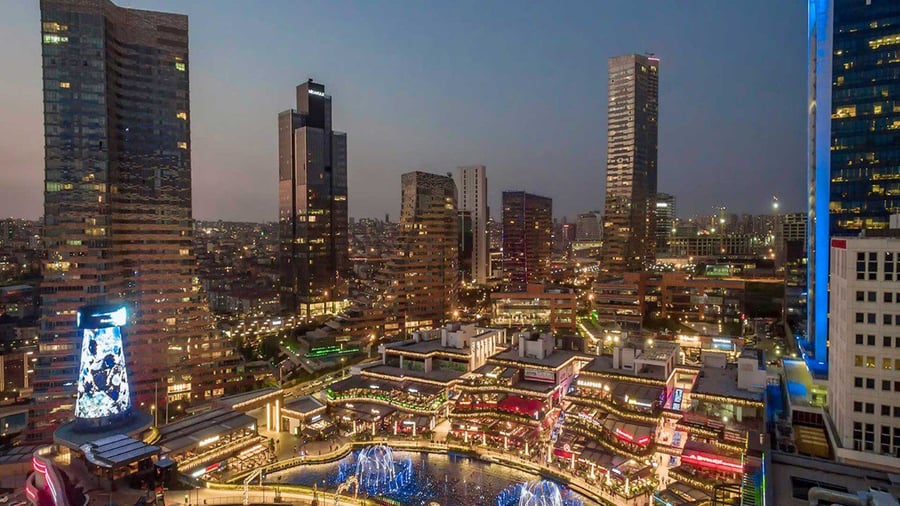
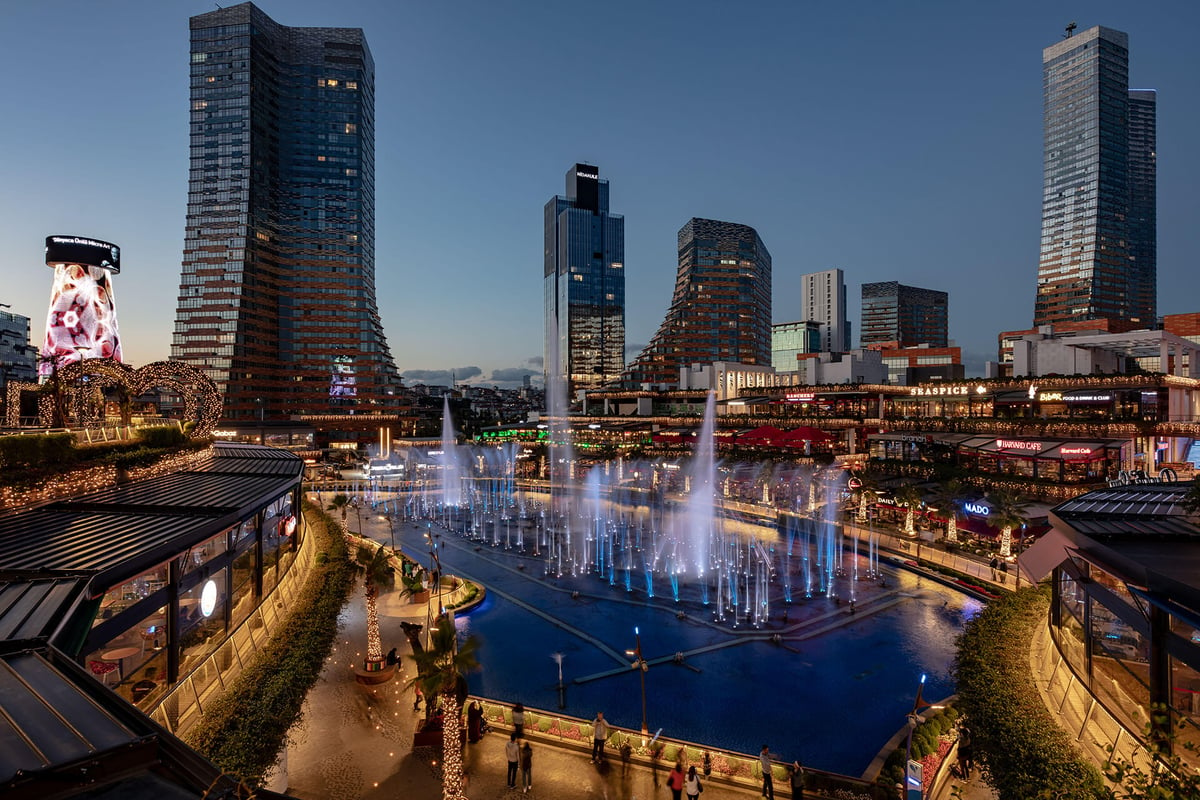
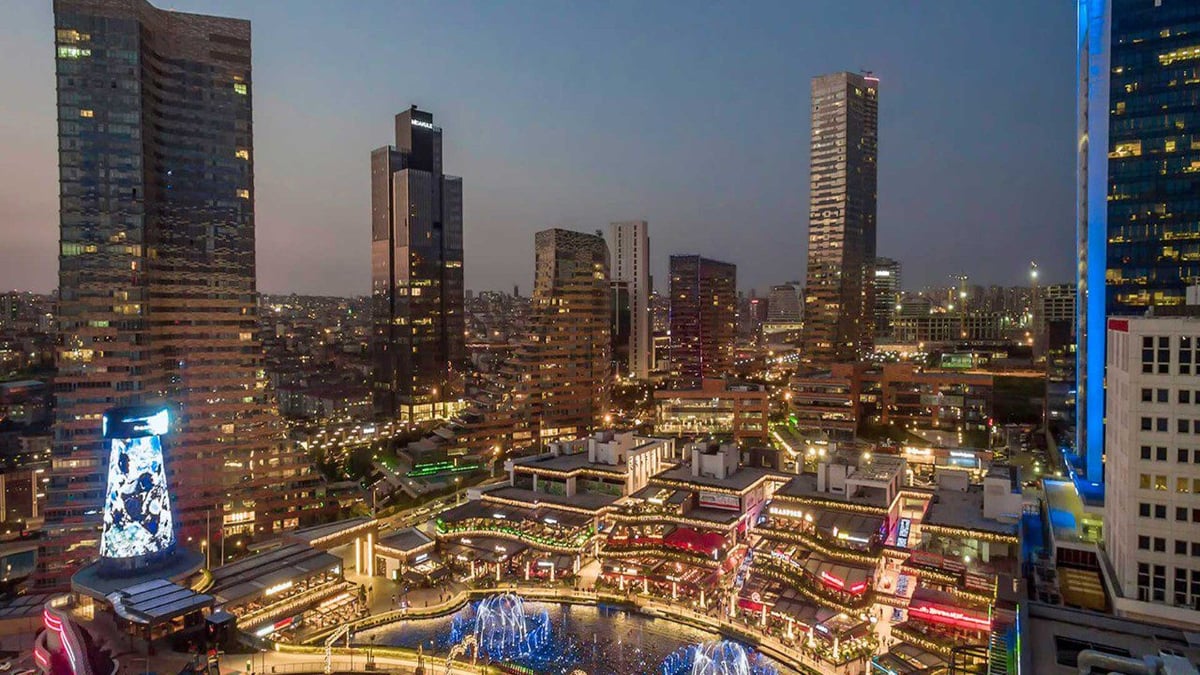
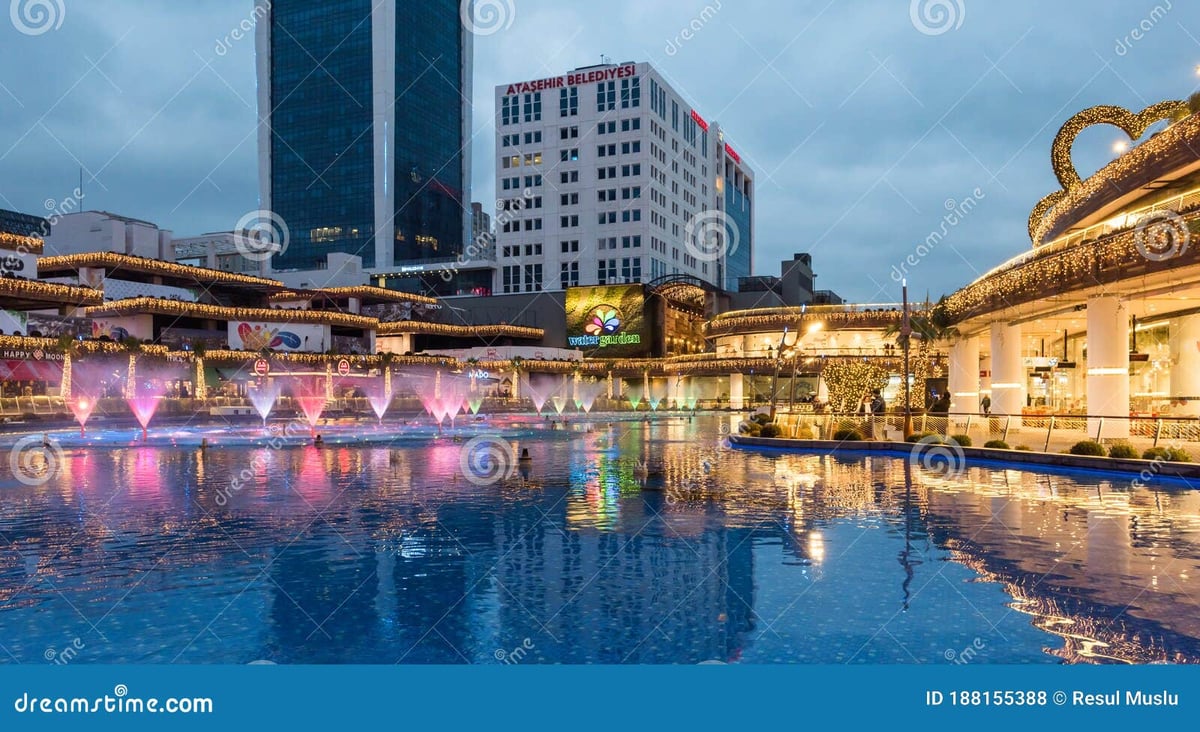
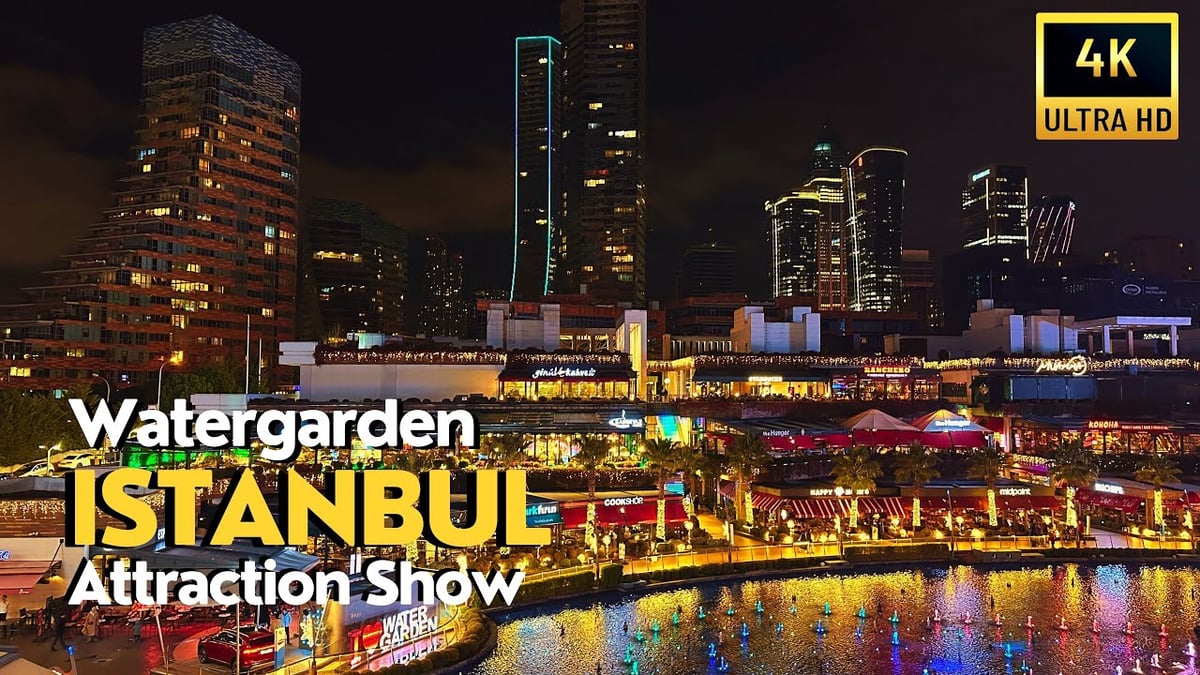
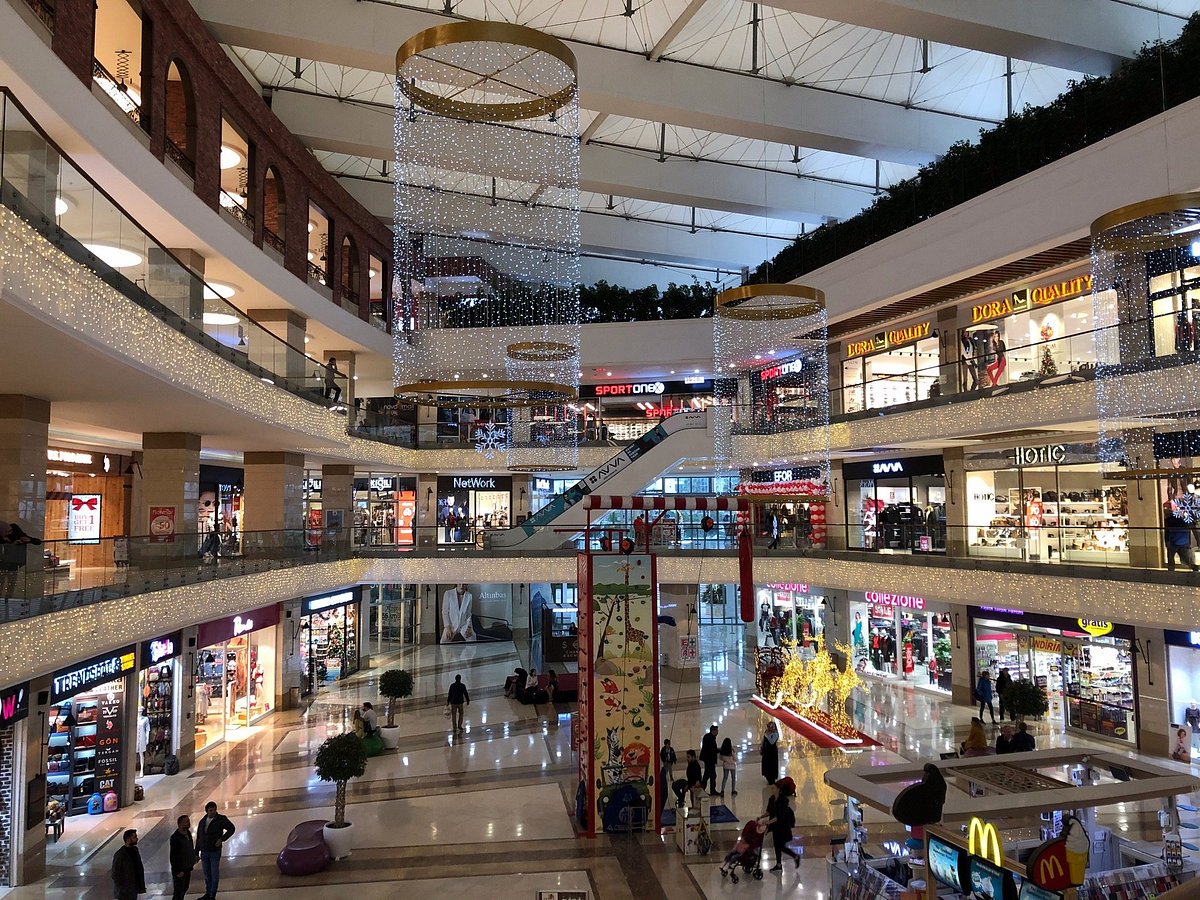
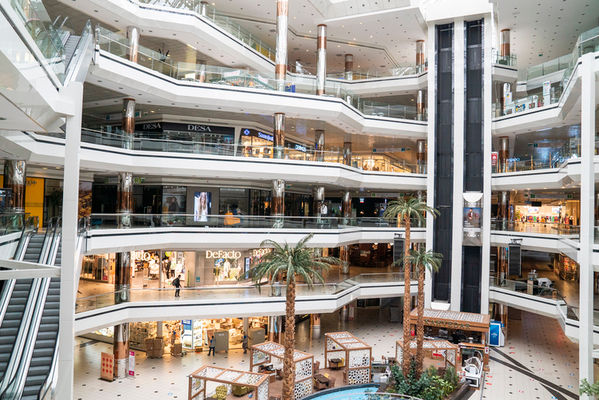
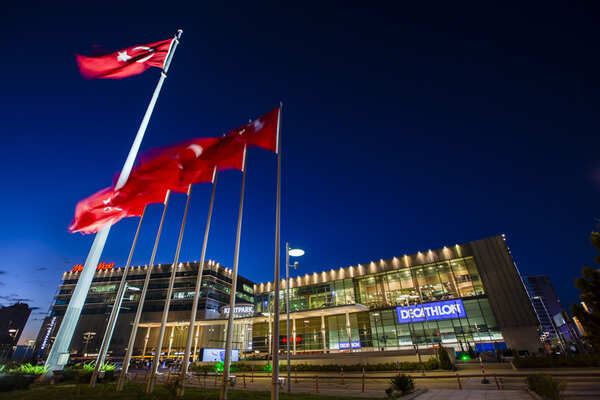
Watergarden AVM, located in the Bakırköy district of Istanbul on the European side, opened in 2015 as a 52,000 square meter gross leasable area (GLA) shopping center emphasizing a lifestyle and gastronomy focus. Positioned along the E-5 highway with proximity to Marmaray rail and Ataturk Airport (now closed, but still accessible via public transport), it benefits from strong regional accessibility serving a population of over 200,000 in Bakırköy and surrounding areas.
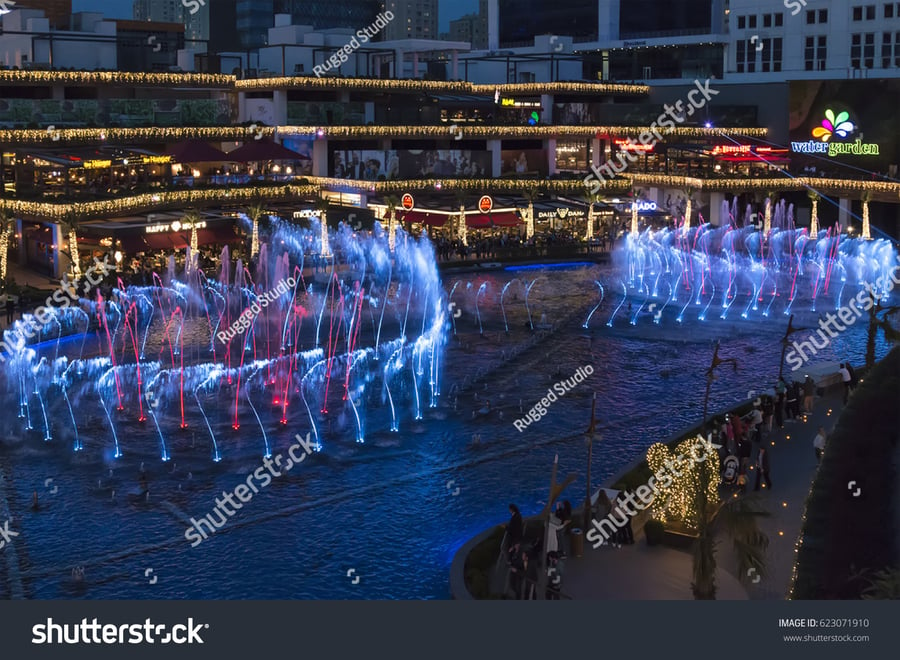
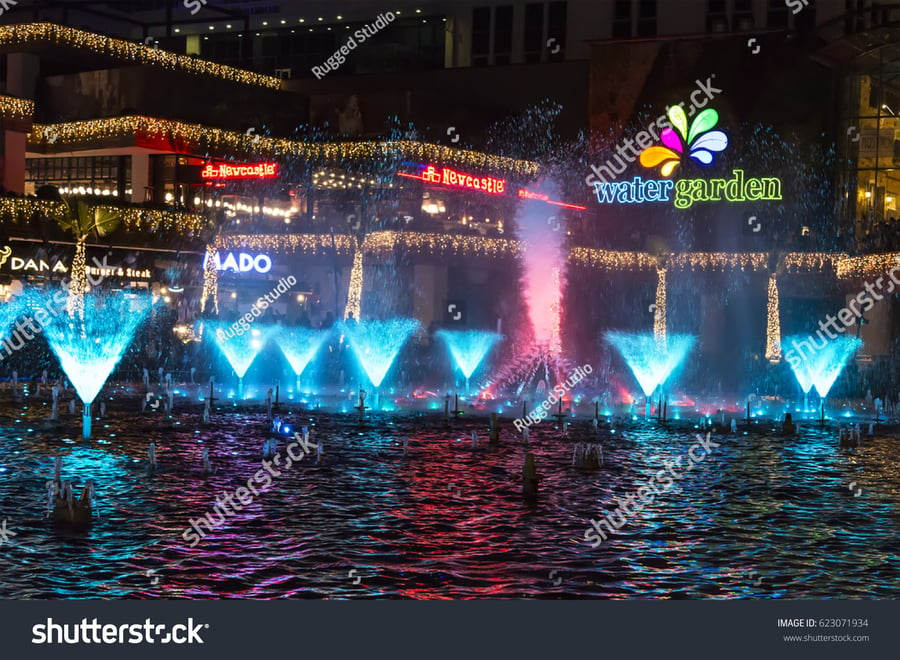
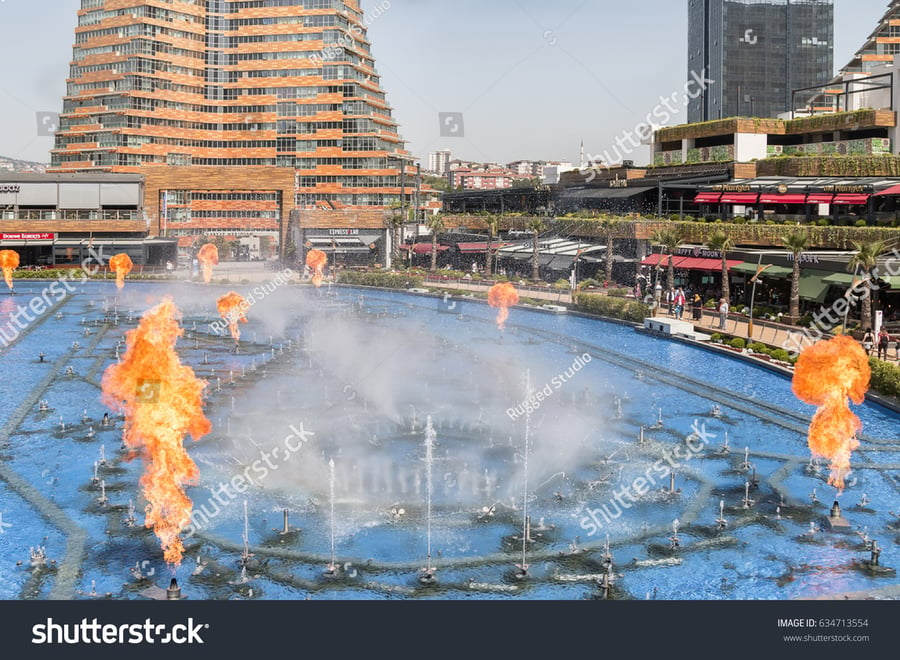
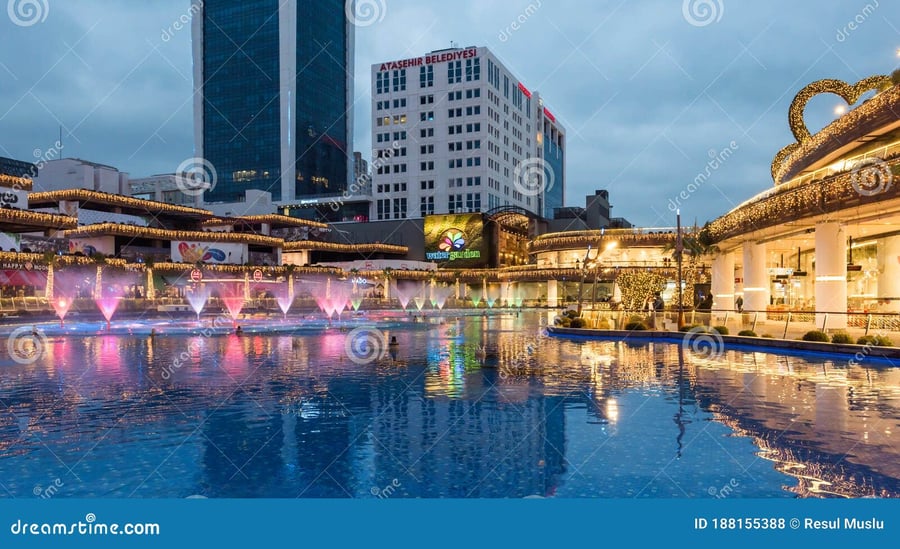
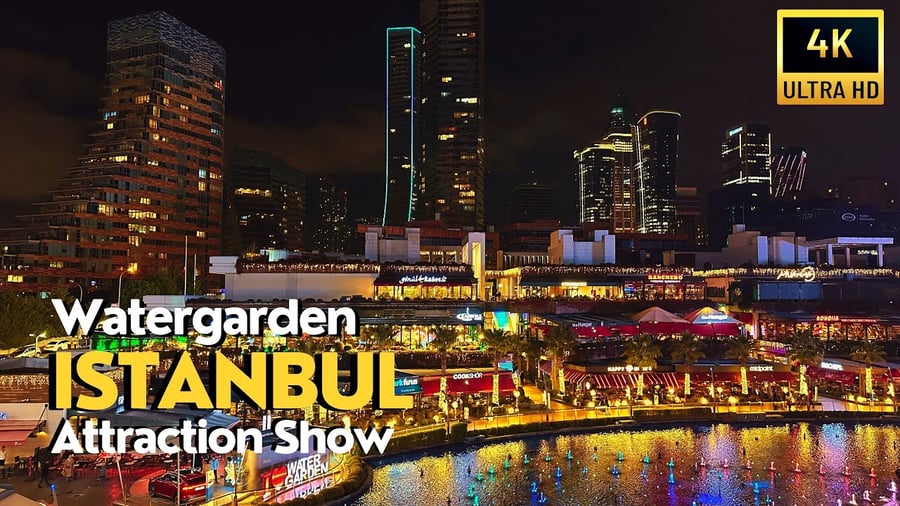
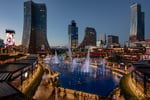
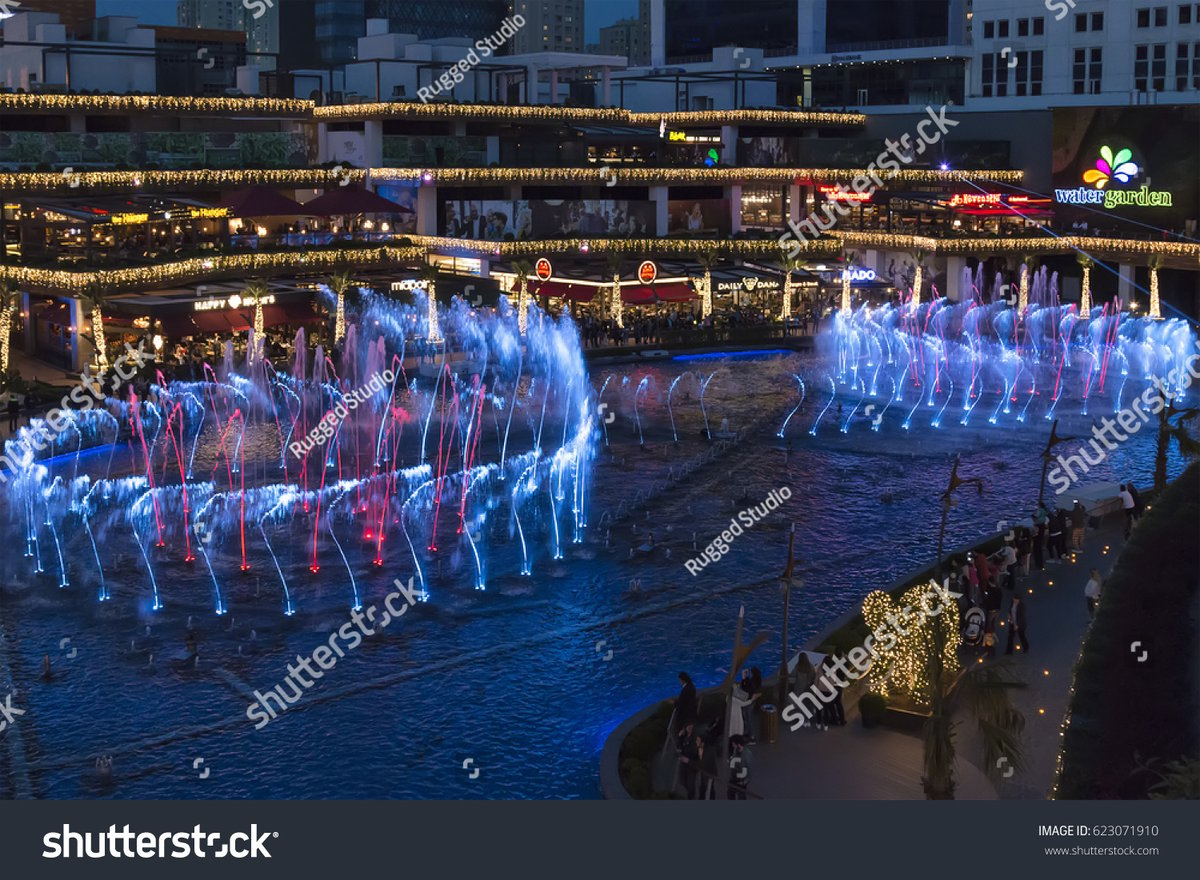
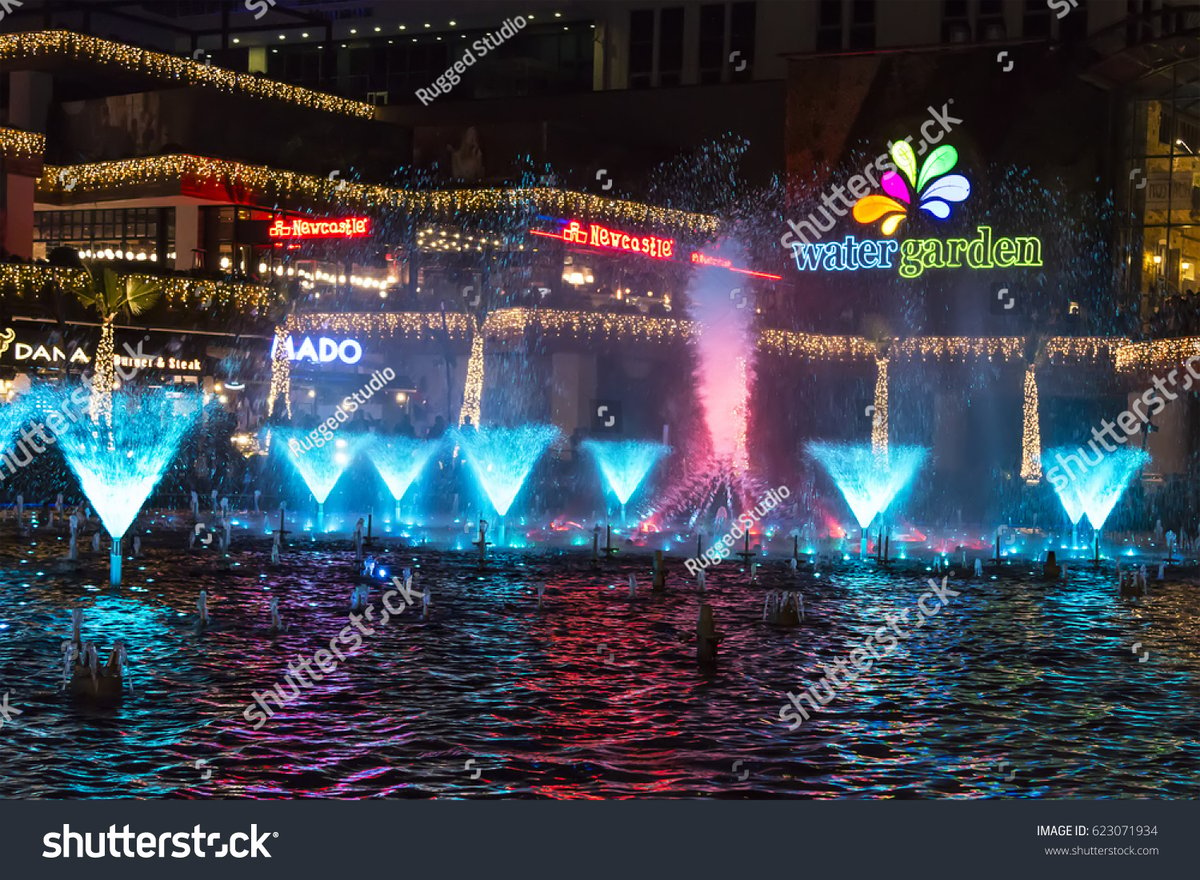
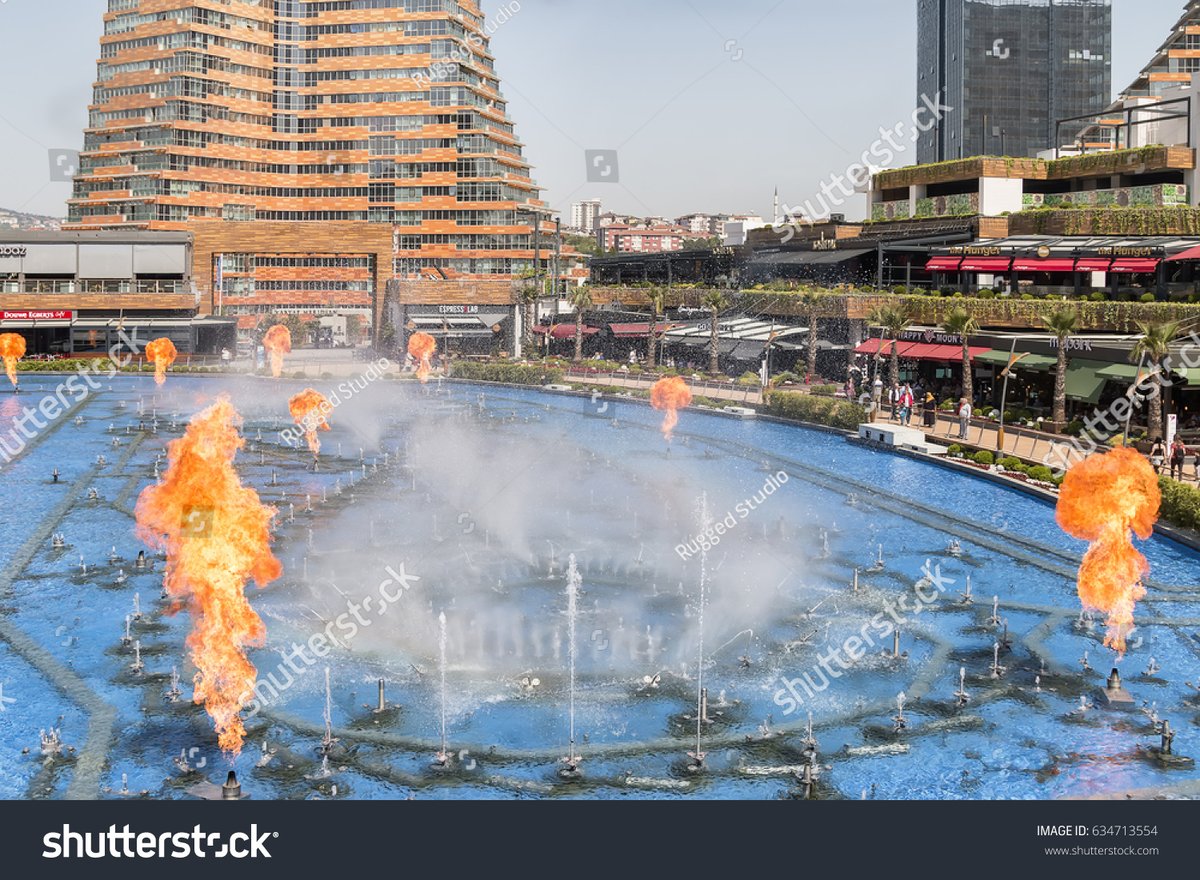
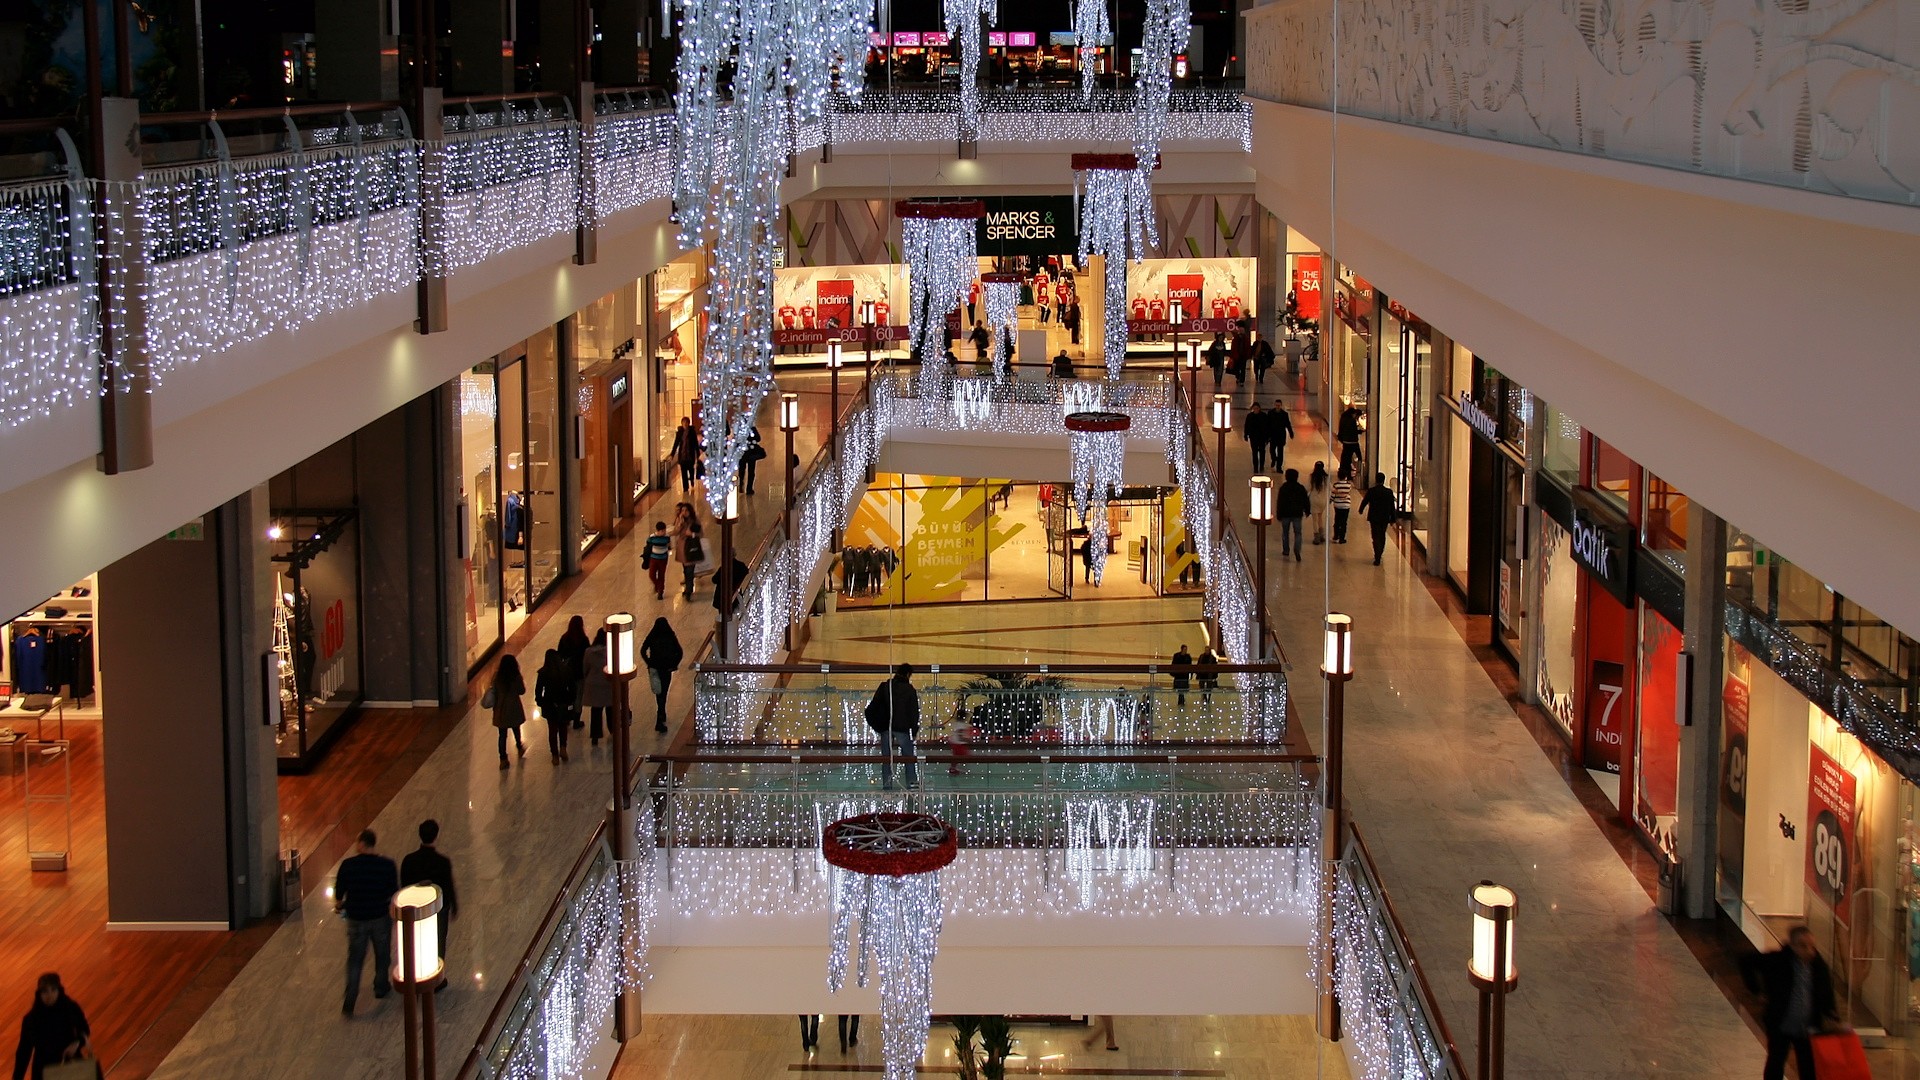
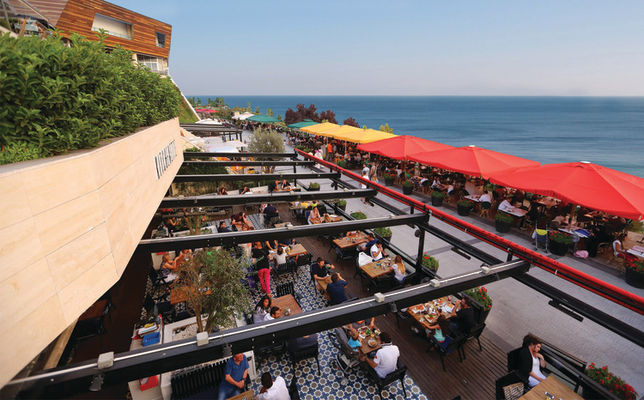
The tenant mix includes over 150 stores across fashion (Zara, H&M, LC Waikiki), electronics (MediaMarkt), home goods (IKEA Express), and a robust F&B sector with 40+ outlets featuring international chains like Starbucks, Burger King, and local eateries, complemented by a 10-screen CineMax cinema and entertainment zones. Unique features include a central water garden with dancing fountains, retractable roof for semi-outdoor experiences, and event spaces for live performances and markets, enhancing dwell time.
Market position is solid in the mid-tier segment, with reported annual footfall exceeding 10 million visitors pre-pandemic, though recovery has been gradual amid Turkey's economic volatility. Occupancy stands at approximately 92% as of recent reports, reflecting stable demand but sensitivity to inflation-driven rent adjustments.
Leasing advantages include flexible unit sizes from 50 to 5,000 sqm, turnover rents averaging 12-15% of sales, and base rents of €25-35 per sqm monthly in prime areas, supported by a diverse demographic of middle-income families (average household income around TRY 15,000 monthly) and young professionals aged 25-45. Drawbacks involve intense local competition from nearby Capacity AVM and Metroport, potential traffic congestion on access routes, and broader market saturation in Istanbul's retail sector, where e-commerce growth has pressured physical sales by 10-15% annually.
Operational quality is high with modern infrastructure, but aging elements like parking (1,500 spaces) may require upgrades.
Overall, it suits retailers targeting experiential shopping and F&B, though economic risks like currency depreciation could impact consumer spending.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Accessibility
Bakırköy's demographic profile features a population of about 230,000, with 70% aged 15-64, including young families and urban professionals with median household incomes of TRY 12,000-18,000 monthly. The area attracts middle-class shoppers from western Istanbul suburbs, supported by high education levels (over 40% university graduates). Accessibility is a strength via E-5 highway and Marmaray station within 1 km, facilitating 500,000+ daily commuters, but peak-hour traffic delays average 20-30 minutes, posing risks for time-sensitive retail. Footfall metrics indicate 8-10 million annual visitors, bolstered by events, yet competition from online platforms reduces conversion rates to 2-3%. This mix supports steady traffic but highlights vulnerability to economic downturns affecting discretionary spending.
Tenant Mix and Occupancy
The tenant mix balances anchors like Zara and MediaMarkt (occupying 30% of GLA) with mid-tier fashion, beauty (Sephora, The Body Shop), and a gastronomy emphasis comprising 25% of space, drawing food-focused visitors. Occupancy at 92% reflects resilient demand post-2023 recovery, with low vacancy in prime zones but higher turnover in peripheral units due to category saturation in apparel. Strengths include complementary mix reducing intra-mall competition, while weaknesses involve over-reliance on F&B (vulnerable to rising food costs) and limited luxury presence compared to upscale malls like Istinye Park. Operational quality is evident in 95% uptime for facilities, aiding retailer performance, though market reports note average sales per sqm of €4,000 annually, below Istanbul averages of €5,500 amid inflation pressures.
Lease Terms and Market Risks
Base rents range €25-35 per sqm monthly for ground-floor units, with turnover components at 10-15% of gross sales, offering flexibility for variable performance retailers. Lease terms typically span 5-10 years with 3-5% annual escalations tied to CPI, plus common area maintenance fees of €5-7 per sqm. Advantages include promotional support via mall events boosting visibility, but drawbacks encompass high competition from 20+ malls within 10 km radius, leading to 5-10% sales cannibalization. Broader risks include Turkey's retail market saturation (over 400 centers nationally), economic instability with 50%+ inflation in 2024 eroding purchasing power, and infrastructure challenges like limited public parking expansion. Retailers should negotiate capex contributions for fit-outs to mitigate aging elements in a 10-year-old property.
Building Details
Detailed Market Analytics
City Snapshot
İstanbul
Comprehensive market intelligence for retail expansion in this city

Other Retail Destinations in İstanbul
Discover more shopping centers in İstanbul.
Popular in Türkiye
Top retail destinations across Türkiye.


Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
İstanbul
Comprehensive market intelligence for retail expansion in this city